Runs in your browser. Nothing you type is sent or saved.
The car payment calculator above tells you four things most dealer quotes leave out: the real amount you finance after sales tax and fees, your monthly payment, the total interest over the life of the loan, and the all-in cost of the car including your down payment and trade-in. Before you start, have the vehicle price, your down payment, the trade-in value and payoff on your current car, your state’s sales tax rate, and the APR and term from any loan offer you have in hand.
How to use the calculator
- Enter the Vehicle price ($) from the window sticker or the dealer’s written quote, before any taxes or fees.
- Enter your Down payment ($), meaning the cash you will actually hand over, not the deposit the dealer suggested.
- Enter the Trade-in value ($) you have been offered in writing, then the Still owed on the trade-in ($) from your current lender’s ten-day payoff letter, not your last statement balance.
- Enter your state’s Sales tax (%) and the Title, registration and dealer fees ($) from the itemized buyer’s order. Ask for that sheet if you have not seen it.
- Enter the Interest rate (APR) (%) and Loan term (months) from the Truth in Lending disclosure on your loan offer, or from a preapproval letter from your bank or credit union.
- Read the monthly payment, then the total interest line, then the total cost line. Change one input at a time to see what moves the number.
Before you borrow
The payment the calculator shows is only the loan. Full-coverage insurance, which lenders require on a financed car, plus fuel and repairs can add several hundred dollars a month on top of it, and a car loan is secured debt: miss payments and the lender can repossess the vehicle and still bill you for any shortfall after it is sold.
Every field explained, and the input mistakes that skew the result
Vehicle price ($). This is the agreed selling price of the car, nothing else. The default is $30,000. The most common mistake is typing in the “out-the-door” number a salesperson quoted, which already includes tax and fees. Do that and the calculator taxes your taxes. Use the bare price and let the other fields add the rest.
Down payment ($). Cash paid at signing, default $3,000. Manufacturer rebates and dealer cash incentives work the same way, so if you have a $1,500 rebate and $3,000 in cash, enter $4,500. Do not include your trade-in here; it has its own field.
Trade-in value ($). The amount the dealer will credit you for your current car, default $0. Use the written offer, not the online estimate. A dealer can quietly lower a trade-in figure while raising a discount elsewhere, so check the final buyer’s order against this number.
Still owed on the trade-in ($). Your current loan’s payoff balance, default $0. If you owe more than the car is worth, the difference is negative equity and the calculator rolls it into the new loan, exactly as a dealer would. Use the official payoff quote from your lender, which includes interest accrued through the payoff date and usually runs a little higher than the balance on your statement.
Sales tax (%). Default 6%. The calculator applies the rate to the full vehicle price. Many states, including Texas and Illinois among others, tax only the difference between the price and your trade-in, and a few states charge no sales tax on vehicles at all. If your state taxes the net amount, the calculator will overstate your tax slightly when you have a trade-in; your state’s department of revenue or DMV site tells you which method applies.
Title, registration and dealer fees ($). Default $800. Title and registration fees are set by the state. Dealer documentation fees are set by the dealer and are capped by law in some states and uncapped in others, so they range from under $100 to several hundred dollars or more. Ask for the itemized list and leave out anything optional, such as extended warranties, paint protection or GAP coverage, unless you have genuinely decided to buy them.
Interest rate (APR) (%). Default 7%. Use the annual percentage rate, which under the Truth in Lending Act must appear on every loan offer. A dealer may quote a “rate” or a payment without an APR; if you cannot find the APR on paper, you do not yet have an offer you can compare.
Loan term (months). Default 60. Longer terms produce lower payments and higher total interest, and they keep you upside down longer because the car depreciates faster than you pay it off in the early years.
How the car payment calculator does the math
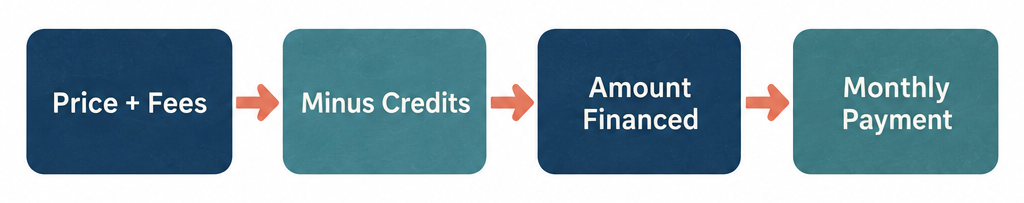
The page runs three equations in order.
First, sales tax equals vehicle price multiplied by the tax rate.
Second, amount financed equals price plus sales tax plus title, registration and dealer fees, minus your down payment, minus your trade-in value, plus whatever you still owe on the trade-in.
Third, the monthly payment uses the standard amortization formula: payment equals amount financed multiplied by r, divided by (1 − (1 + r) to the power of −n). Here r is the monthly rate, which is the APR divided by 12 and then by 100, and n is the term in months. The formula produces a fixed payment where the interest portion is largest in month one and shrinks each month as the balance falls.
Total cost then equals your down payment plus your trade-in value, minus the amount owed on it, plus every monthly payment.
The default example, step by step
With the default inputs:
- Sales tax: $30,000 × 6% = $1,800.00.
- Amount financed: $30,000 + $1,800 + $800 − $3,000 − $0 + $0 = $29,600.00.
- Monthly rate: 7 ÷ 12 ÷ 100 = 0.0058333.
- (1 + 0.0058333) raised to the −60 power is about 0.70541, so the denominator 1 − 0.70541 = 0.29459.
- Payment: $29,600 × 0.0058333 ÷ 0.29459 = $586.12.
- Total of all payments: 60 × $586.12 (unrounded) = $35,166.93.
- Total interest: $35,166.93 − $29,600.00 = $5,566.93.
- Total cost: $3,000 down + $0 trade-in − $0 owed + $35,166.93 = $38,166.93.
Notice that the $30,000 car costs $38,166.93 by the time the title is yours. Nearly 19% of what you pay out never touches the car’s price.
A second example: a used car with negative equity
Say you are buying an $18,500 used SUV. You have $2,000 cash, the dealer offers $6,000 for your current car, and you still owe $4,500 on it. Your state’s tax rate is 7%, fees total $500, and because the car is used and your credit is mid-range, the APR is 10% over 48 months.
- Sales tax: $18,500 × 7% = $1,295.00.
- Amount financed: $18,500 + $1,295 + $500 − $2,000 − $6,000 + $4,500 = $16,795.00.
- Monthly rate: 10 ÷ 12 ÷ 100 = 0.0083333.
- (1.0083333) to the −48 power is about 0.67143, so the denominator is 1 − 0.67143 = 0.32857.
- Payment: $16,795 × 0.0083333 ÷ 0.32857 = $425.96.
- Total of all payments: about $20,446.30.
- Total interest: $20,446.30 − $16,795.00 = $3,651.30.
- Total cost: $2,000 + $6,000 − $4,500 + $20,446.30 = $23,946.30.
Try one change: pay off the $4,500 on the old car yourself instead of rolling it in. The amount financed drops to $12,295 and the payment to about $311.84. The negative equity alone costs you $114 a month and roughly $978 in extra interest across the loan.
Quick reference: what rate and term do to the default loan
These tables apply the calculator’s formula to the default amount financed of $29,600. Figures are rounded to the nearest dollar; run your own numbers above for cents.
Monthly payment on $29,600 financed
| Term | 4% APR | 7% APR | 10% APR | 14% APR |
|---|---|---|---|---|
| 36 months | $874 | $914 | $955 | $1,012 |
| 48 months | $668 | $709 | $751 | $809 |
| 60 months | $545 | $586 | $629 | $689 |
| 72 months | $463 | $505 | $548 | $610 |
| 84 months | $405 | $447 | $491 | $555 |
Total interest on $29,600 financed
| Term | 7% APR | 10% APR |
|---|---|---|
| 36 months | $3,303 | $4,784 |
| 48 months | $4,422 | $6,435 |
| 60 months | $5,567 | $8,135 |
| 72 months | $6,735 | $9,883 |
| 84 months | $7,927 | $11,677 |
Stretching the 7% loan from 60 to 84 months lowers the payment by $139 and raises the interest bill by $2,360. Going from 7% to 10% at 60 months adds only $43 a month, which is why a dealer can make a bad rate feel cheap by talking about the payment alone.
Extra payments on the default loan ($29,600 at 7% for 60 months)
| Extra each month | New payment | Paid off in | Total interest | Interest saved |
|---|---|---|---|---|
| $0 | $586.12 | 60 months | $5,567 | $0 |
| $50 | $636.12 | 55 months | $5,035 | about $530 |
| $100 | $686.12 | 50 months | $4,597 | about $970 |
| $200 | $786.12 | 43 months | $3,920 | about $1,650 |
Interest figures in the extra-payment table are approximate because the final partial payment varies with the exact posting date. The pattern is what matters: extra money goes entirely to principal on a simple-interest auto loan, so every $100 a month shaves most of a year off the default loan.
Reading your result
What counts as a high payment
A budget guideline widely used by credit counselors, sometimes called 20/4/10, suggests putting at least 20% down, financing for no more than four years, and keeping total vehicle costs including insurance under 10% of gross income. It is a rule of thumb, not a law, and the default example fails two of three tests: 10% down and a five-year term. For a household earning $70,000 a year, 10% of gross income is $583 a month for everything car-related, so the $586 default payment leaves nothing for insurance or fuel.
A more useful check is the total interest line. If interest is more than 15% to 20% of the amount financed, either the rate or the term is doing damage. In the default example interest is 18.8% of the loan. In the 84-month, 14% scenario it is more than 57%.
Compare offers on amount financed and APR, never on monthly payment. A dealer who asks “what payment are you comfortable with” is setting up a longer term, a higher rate, or both. Reset the calculator with each written offer and compare total cost.
Cheaper and safer options to check first
A preapproval from a credit union or bank before you visit the dealer gives you a benchmark APR. Dealers arrange financing through lenders and are often allowed to add to the rate the lender approved, a practice called dealer markup or dealer reserve, so a preapproval in your pocket is leverage. Federal credit unions are subject to a statutory interest-rate ceiling set by the National Credit Union Administration, which has held it at 18% in recent years, and many price well under that for members with fair credit.
A larger down payment is the cheapest way to lower the result, because it cuts both the balance and the interest. Selling a trade-in privately, rather than through the dealer, often brings more than a dealer allowance, though you lose any tax credit on the trade-in in states that tax the net price.
If you are being quoted a very high APR because of credit, a smaller or older car, a cosigner, or a few months spent fixing credit-report errors under the Fair Credit Reporting Act will usually do more for the payment than any negotiating trick. An unsecured option is rarely cheaper for a car purchase, but if you are comparing, our “loan calculator” and “personal loan calculator” use the same amortization math so the numbers line up.
Make the calculator do the negotiating
Run three versions before you sign: the dealer’s offer as written, the same car at your preapproved APR, and the same car with 12 fewer months on the term. The gap between the first and second total-cost lines is the dealer’s markup. The gap between the first and third is what the “low payment” pitch is really costing you.
Using this page as a refinance or payoff calculator
The fields are built for a purchase, but they double as a car refinance rate calculator with four substitutions. Enter your current payoff balance as the Vehicle price ($), set Sales tax (%) to 0, set Down payment ($), Trade-in value ($) and Still owed on the trade-in ($) to 0, and enter any title-transfer or lien fee the new lender charges in the fees field. Then enter the APR and term you are being offered. Compare the total interest line with the interest left on your current loan, which your current lender can tell you or which you can estimate by running your original terms and subtracting the payments you have already made.
Two cautions on refinancing. Resetting a 60-month loan with 40 months left to a fresh 60 months lowers the payment but can raise total interest even at a lower rate, so match the new term to your remaining months when you compare. And if you owe more than the car is worth, many lenders will not refinance at all, or will only do so at a higher rate.
For payoff planning, use the extra-payment table above or run the calculator with a shorter Loan term (months) to see the payment that retires the loan on your schedule. Before sending extra money, ask your lender in writing whether extra amounts are applied to principal or treated as early payments of future installments, and check your contract for any prepayment penalty; most auto loans do not have one, but some subprime contracts do.
Payoff quotes expire
A payoff figure is only good through a stated date, usually ten days. If you are trading in or refinancing, get a fresh quote within that window, enter it in the Still owed on the trade-in field, and make sure the dealer or new lender pays it off within the period the state allows. A late payoff can trigger a missed-payment mark on your credit report for a loan you thought was gone.
The US rules that protect car buyers
Truth in Lending Act and Regulation Z (12 CFR 1026). Before you sign a closed-end loan, the creditor must disclose the APR, the finance charge in dollars, the amount financed, the total of payments and the payment schedule. These are the same figures the calculator produces, and they let you catch a quote that quietly changed between the showroom and the finance office. If the disclosed APR or amount financed does not match what you entered, stop and ask why before you sign.
Equal Credit Opportunity Act. A lender cannot price or deny a loan based on race, sex, national origin, religion, marital status, age (if you are old enough to contract) or because your income comes from public assistance. If you are denied, or approved on worse terms than you asked for, you have the right to a written statement of the specific reasons.
Fair Credit Reporting Act. You are entitled to free copies of your credit reports, and if a lender gives you a worse rate than its best customers based on your report, it must send a risk-based pricing notice or a credit-score disclosure. Dispute errors before you shop; a wrongly reported late payment can move you into a higher rate tier.
Military Lending Act and the Servicemembers Civil Relief Act. The Military Lending Act caps most consumer credit to active-duty members and dependents at a 36% Military Annual Percentage Rate, but the Department of Defense rule at 32 CFR Part 232 exempts loans made specifically to buy a vehicle when the loan is secured by that vehicle. So a standard dealer-arranged purchase loan is generally outside the cap, while some cash-out or add-on arrangements may not be. The Servicemembers Civil Relief Act separately caps interest at 6% on debts you took on before entering active duty, including an existing car loan, if you request it in writing with a copy of your orders.
State law. Auto loan rates are governed mostly by state retail installment sales acts and usury statutes, and the caps vary widely; some states set tiered maximum rates based on the vehicle’s age, others set none for licensed lenders. Documentation fees are capped in some states and not others. Your state attorney general or financial regulator publishes the rules, and dealers and finance companies must hold the appropriate state license, which you can check with that regulator before you sign.
Repossession and deficiency balances. Under Article 9 of the Uniform Commercial Code as enacted in each state, a lender that repossesses must sell the car in a commercially reasonable way and send you notice, and you remain liable for any deficiency. A deficiency that goes to a third-party “debt collector” is covered by the Fair Debt Collection Practices Act, which limits how and when the collector can contact you and gives you the right to request validation of the debt in writing.
Paying with crypto. If you sell cryptocurrency to raise a down payment, the IRS treats crypto as property under IRS Notice 2014-21, so the sale is a taxable event and any gain since you acquired the coins is a capital gain for the year of sale. Brokers now report these dispositions on Form “1099-da“, and the proceeds are what you enter in the Down payment ($) field, not the amount you originally paid for the coins.
FAQ
Is this the same as a loan calculator for a car from a bank?
Yes, with one addition. Bank calculators usually ask only for the loan amount, rate and term, and leave you to figure out the loan amount yourself. This car payment calculator builds the amount financed for you from the price, sales tax, fees, down payment and trade-in, which is where most people underestimate what they are borrowing.
How do I estimate a car payment before I have a rate?
Use the APR from a recent preapproval letter if you have one. If you do not, run the calculator at three rates that bracket your credit profile, for example 5%, 8% and 12%, and treat the middle result as a planning number. The quick-reference tables above show how much each three-point move in rate changes the default payment.
Does the used car loan calculator math differ from new?
The formula is identical. What changes are the inputs: used cars usually carry higher APRs, lenders cap terms by the vehicle’s age and mileage, and the price-to-value gap is smaller, so you are less likely to be deeply upside down. Enter the actual used-car APR you are quoted rather than the promotional rate advertised for new models.
Can I use this as an interest rates calculator for a car I already own?
Yes. Enter your current payoff as the Vehicle price ($), zero out tax, down payment and trade-in fields, and enter your current APR and remaining months. The total interest line shows what the rest of the loan costs you, which is the number to beat when you look at refinancing.
How does a car loan payoff calculator handle extra payments?
On a simple-interest auto loan, every dollar above the scheduled payment reduces principal, which shrinks the interest charged the following month. The extra-payment table above shows the effect on the default loan: $100 extra per month pays it off ten months early and saves about $970. Confirm with your lender that extra amounts are applied to principal and not held as prepaid future installments.
What does a car loan amortization calculator show that this one does not?
An amortization schedule lists each month’s interest and principal split and the remaining balance. This page gives you the totals. You can approximate month one yourself: on the default loan, the first month’s interest is $29,600 × 0.0058333 = $172.67, and only the remainder of the first payment after that interest reduces the balance. By the final month the split is nearly reversed.
What should I do with the result if the payment is more than I can afford?
Change the inputs that are actually under your control: a cheaper car, a larger down payment, paying off negative equity separately, or a lower APR through a credit-union preapproval. Avoid covering a car payment with a “payday loan” or an app advance; those products cost far more per dollar than any car loan and turn a one-month shortfall into a recurring one. If you are already behind, ask the lender about a hardship deferral before the account is 30 days late, and a nonprofit credit counselor certified by the National Foundation for Credit Counseling can review your full budget at no charge.
Comments are closed