Category: Crypto Basics

  • Nominated proof of stake (NPoS) explained

    Nominated proof of stake (NPoS) explained

    NPoS stands for nominated proof of stake, the consensus system Polkadot and Kusama use to choose which computers validate transactions. Token holders called nominators back validators with their coins, an election algorithm picks the validator set, and both sides share the rewards and the penalties. This guide explains how that flow works, what you can lose, and how US tax rules treat the rewards.

    Full nameNominated proof of stake
    Used byPolkadot and Kusama
    Two rolesValidators and nominators
    Nominations per account16 on Polkadot
    Unbonding period28 days on Polkadot
    Reward taxOrdinary income when received

    The short definition

    In plain words, nominated proof of stake means you vote with your coins for the validators you trust, and you put those coins at risk if your picks misbehave.

    That second half is what separates NPoS from most “delegated” systems. On Polkadot, a nominator is not a passive voter. Your stake is bonded, it earns a share of the validator’s reward, and it can be slashed alongside the validator’s own stake.

    The design comes from Web3 Foundation research. Its stated goals are to spread stake evenly across as many independent validators as possible, to keep hardware costs low enough that ordinary operators can run a node, and to make it expensive for any one group to capture the network.

    How NPoS works, step by step
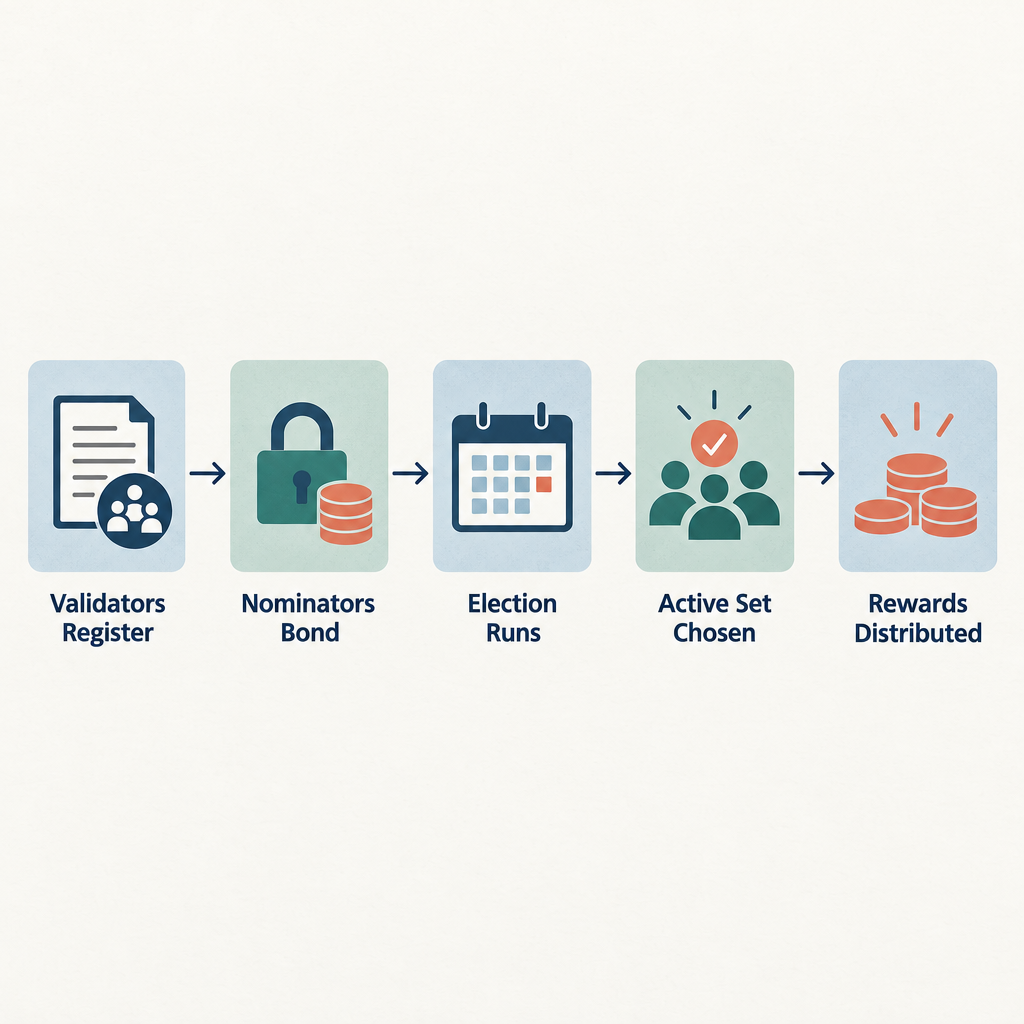
    Flow diagram showing five steps: Validators Register, Nominators Bond, Election Runs, Active Set Chosen, Rewards Distributed

    Polkadot runs staking in rounds called eras. An era lasts 24 hours on Polkadot and 6 hours on Kusama. At the boundary of each era, the chain reruns the validator election.

    What happens in one Polkadot era

    1. Validators advertise themselves, set a commission rate and post their own bonded stake.
    2. Nominators bond DOT and name up to 16 validators they are willing to back.
    3. The election algorithm selects the active set and splits each nominator’s stake across their winning picks.
    4. Active validators produce blocks, check parachain data and vote on finality, earning era points.
    5. At the era’s end, rewards are calculated per validator and shared with nominators after commission.
    6. Any misbehavior recorded during the era is flagged for slashing, which applies after a delay.

    Validators

    Validators run the software that produces blocks and finalizes them. They also verify the data coming from Polkadot’s parachains, which is the heavier job. Each validator sets a commission, a percentage of the total reward it keeps before splitting the rest with nominators. Commission ranges from 0% to 100%, and a validator at 100% keeps everything.

    The number of active validators is a governance parameter. Polkadot has run a few hundred active validators since launch and has raised the count through referendums more than once. Kusama, the faster-moving test network, runs roughly a thousand.

    Nominators

    Nominators are the backers. You lock DOT, choose up to 16 validators, and let the algorithm decide how your stake is distributed among the ones that win. You can change your list at any time, but the change only takes effect at the next election.

    Your reward depends on which of your picks actually get elected, how much total stake they carry, and their commission. If none of your 16 picks are elected, you earn nothing that era.

    The election algorithm

    This is the part that makes NPoS distinct. Polkadot uses a sequential version of the Phragmén method, a proportional voting system worked out by the Swedish mathematician Edvard Phragmén in the 1890s. The research team later published a refinement called Phragmms.

    The algorithm has two aims:

    • Elect a set that reflects nominator preferences proportionally, so a group holding 20% of the stake can secure about 20% of the seats and not more.
    • Maximize the minimum backing of any elected validator, so there is no weakly staked validator that an attacker could cheaply knock out.

    Because of that second goal, the chain does not simply hand seats to the richest validators. It actively moves nominator stake toward less-backed candidates. You see the result when you check your account: your stake usually ends up concentrated on one or two of your 16 picks rather than spread evenly.

    How rewards are split

    Rewards in NPoS are not proportional to a validator’s total stake. Each active validator earns era points for the work it performs, and validators that do similar work earn similar points. A validator backed by 2 million DOT and one backed by 1.8 million DOT earn close to the same payout.

    That reward is then split in this order:

    1. The validator takes its commission off the top.
    2. The remainder is divided among everyone backing that validator, including the validator’s own bond, in proportion to stake.

    The arithmetic means nominators on a lightly backed validator earn a higher percentage return than those on a heavily backed one. Say two validators each earn 100 DOT in an era, both charge 5% commission, and one has 1 million DOT behind it while the other has 2 million. Backers of the first share 95 DOT across 1 million, or 0.0095% for the era. Backers of the second get half that rate. This is deliberate. It pushes stake toward smaller operators and keeps the set decentralized.

    Overall yield depends on how much DOT is being issued and what share of all DOT is staked. Polkadot’s inflation schedule is set by on-chain governance and has been changed by referendum, so you should treat any single APY figure you see online as a snapshot rather than a promise.

    Slashing: what you can actually lose

    Slashing is the enforcement mechanism. When a validator is caught misbehaving, a percentage of its bonded stake is destroyed, and the same percentage is taken from every nominator backing it.

    Two offenses matter in practice:

    • Unresponsiveness. A validator that goes offline for most of a session is flagged. A single offline validator is not slashed. The penalty only kicks in when more than 10% of the set is offline at once, because that pattern looks like a coordinated failure rather than one operator’s bad night.
    • Equivocation. Signing two conflicting blocks or two conflicting finality votes. This is the serious one. Penalties start small for an isolated incident and scale toward 100% when many validators equivocate together, since that is what an attack on the chain looks like.

    Slashes on Polkadot do not apply instantly. They sit in a queue for about 27 days, and Polkadot’s governance can cancel a slash during that window if it was caused by a software bug rather than bad intent. That has happened. The delay protects honest operators, but it also means a pending slash can hit you after you have already decided to leave.

    Nominators have one more exposure to understand. Your reward share and your slash share come from the same proportion of stake. If you are a large part of a validator’s backing, you take a large part of any penalty.

    Bonding, unbonding and the 28-day lockup

    Once you bond DOT, it stays locked while it is staking. If you decide to stop, you unbond, and then you wait 28 days on Polkadot (7 days on Kusama) before the coins become transferable. You earn no rewards during that wait.

    The length of that lockup is the biggest practical difference between staking and simply holding. If the price falls 40% in week two of your unbonding period, you watch it happen with no way to sell. Any plan to stake should assume you cannot touch the coins for a month after you change your mind.

    Polkadot added a fast-unstake option for accounts that have been bonded but never actually exposed to a validator. If your picks were never elected, you may be able to withdraw without the full wait. Accounts that were actively backing elected validators still serve the 28 days.

    Nomination pools for small holders

    Direct nomination on Polkadot has a practical floor. The chain limits how many nominators can be counted in an era, and only the largest bonds above a dynamic threshold earn rewards. That minimum active bond has often sat in the low hundreds of DOT, which prices out small accounts.

    Nomination pools, launched on Polkadot in late 2022, solve that. A pool combines many small bonds into one nominating account run by a pool operator. The minimum to join is 1 DOT. You keep the same slashing exposure and the same unbonding period, and the pool operator picks the validators on your behalf. You are trusting that operator’s judgment on validator selection, so you should find out who runs it and how long it has been active.

    NPoS compared with other staking designs

    The names sound similar, so it helps to see the differences side by side.

    Feature NPoS (Polkadot) Delegated PoS (EOS, Tron) Plain PoS (Ethereum)
    Who validates Elected set, a few hundred Small elected set, often 21 to 27 Anyone with 32 ETH
    How stake is assigned Algorithm spreads it proportionally Votes go to top-ranked producers Each validator stakes its own
    Do backers get slashed Yes, same rate as validator Usually no No backers in the base protocol
    Payout per validator Roughly equal regardless of stake Varies by rank Per validator, scales with count
    Exit wait 28 days Varies, often days Queue-based, varies

    The key difference from delegated proof of stake is accountability. In most DPoS chains, you vote for block producers but face no direct penalty if they cheat. In NPoS you do. Polkadot’s designers argue that shared risk makes nominators pick carefully, which keeps bad operators out of the set.

    Consensus design also does not, on its own, determine throughput. How many “transactions per second” a chain handles depends far more on block size, block time and the parachain or sharding layout than on how validators are chosen.

    The risks in plain terms

    Before you stake DOT or any NPoS token

    Staking locks your coins for 28 days after you decide to leave, and a validator’s mistake can destroy part of your stake. The coins themselves can lose all of their value, and nothing about staking is insured by the FDIC or SIPC.

    Beyond price risk and slashing, watch for these:

    • Commission changes. A validator can raise commission at any time. Some set 0% to attract nominators, then move to 100% and pocket the entire reward. The chain now flags sharp commission jumps in many wallet interfaces, but the responsibility to check is yours.
    • Validator churn. Your 16 picks may stop being elected. Rewards drop to zero until you choose new ones.
    • Custodial staking. If you stake through an exchange rather than on-chain, you hold an IOU from that company. If it fails, you are an unsecured creditor. Customers of FTX, Celsius and Voyager learned this in 2022.
    • Phishing. Fake “Polkadot staking” sites ask you to enter your seed phrase. No legitimate staking process ever requires it on a website.

    US rules and taxes on staking rewards

    The IRS treats crypto as property under IRS Notice 2014-21. Staking rewards are addressed directly in Revenue Ruling 2023-14, issued July 31, 2023. It says rewards are ordinary income in the year you gain dominion and control over them, valued at fair market value on that day. On Polkadot, control usually arrives when the payout lands in your account, not when it is calculated.

    That income becomes your cost basis. When you later sell the rewarded DOT, the difference between the sale price and that basis is a capital gain or loss. Record the date and dollar value of every payout. With daily eras, that can mean 365 small income events per year.

    If you stake through a US exchange, the exchange may send you a Form 1099-MISC for rewards above $600. Separately, brokers must report crypto sales on Form “1099-DA” for transactions from January 1, 2025 onward, with cost basis reporting phasing in for 2026 sales. Those forms cover sales, not the staking income itself, so you still need your own records.

    On securities law, the picture has shifted. In February 2023, Kraken paid $30 million to settle SEC charges over its staking-as-a-service program and shut that program for US customers. In May 2025, the SEC’s Division of Corporation Finance published a staff statement saying that certain protocol staking activities, including self-staking and some custodial arrangements, do not involve securities offerings. That statement is staff guidance, not a rule or a court ruling, and it can change. Web3 Foundation has said publicly that it believes DOT is not a security, which is the foundation’s position rather than an SEC finding.

    If you want to verify a US company offering staking, check FinCEN’s MSB registrant search and your state’s money transmitter license lookup. Report suspected fraud at FTC ReportFraud or the FBI’s IC3 portal.

    Other things “npos” can mean

    The search term is shared by a few unrelated fields, so here is a quick sort in case you landed in the wrong place.

    • string::npos in C++ is a constant that means “no position.” Functions like find() return it when they cannot locate a substring. Its value is the largest possible size_t, which is why comparing a position against it works as a not-found check.
    • NPO in medicine is Latin for nil per os, meaning nothing by mouth. It is a fasting instruction before surgery or certain tests, and the length of time varies by procedure.
    • NPO as an organization type means nonprofit organization.

    None of those relate to crypto staking, and nothing in this article applies to them.

    FAQ

    Is NPoS the same as delegated proof of stake?

    No. Both let token holders back validators, but NPoS slashes nominators alongside validators and uses a proportional election algorithm to spread stake. Most DPoS chains do neither.

    How much DOT do I need to nominate?

    Direct nomination only earns rewards above a dynamic minimum that has often been in the low hundreds of DOT. Nomination pools accept as little as 1 DOT. Both carry the same slashing risk and 28-day unbonding wait.

    Can I lose my whole stake as a nominator?

    In theory yes. Equivocation slashes scale toward 100% when a large share of validators misbehave together. In practice, slashes on Polkadot have been rare and small, and governance has reversed some caused by bugs. Rare is not never.

    Are staking rewards taxed if I never sell them?

    Yes. Under Revenue Ruling 2023-14, rewards are income when you gain control of them, at that day’s dollar value, regardless of whether you sell.

    Why does my stake only show on one or two validators when I picked 16?

    The Phragmén election assigns your stake where it best balances the network, not evenly. Your 16 picks are a list of validators you are willing to back, not a split you control.

    Is staked DOT insured?

    No. Crypto is not covered by FDIC or SIPC insurance, and a staking position can fall to zero in value.
  • Transactions per second: how fast blockchains really are

    Transactions per second: how fast blockchains really are

    Transactions per second (TPS) is the number of transactions a network confirms in one second, averaged over some window. For blockchains it is the most quoted speed metric, and also the most abused. Bitcoin handles single digits, Ethereum’s base layer a few dozen, and Solana claims tens of thousands, yet none of those numbers mean what the marketing suggests until you know how they were measured.

    Bitcoin typical TPSabout 3 to 7
    Ethereum base layerroughly 15 to 30
    Solana claimed peak65,000
    Visa stated capacity65,000 messages per second
    Counting methodvaries by chain
    As oflate 2025

    Define TPS: what transactions per second actually measures

    TPS is a throughput figure. Take the total number of transactions a system processed over a period, divide by the number of seconds in that period, and you have it.

    The word “transaction” is doing a lot of work in that sentence. In a bank’s database it might mean one debit. On a blockchain it can mean a payment, a token swap, a contract call, or an internal housekeeping message that moves no money at all.

    So the TPS definition is simple arithmetic, but the inputs are not. Two chains reporting “1,000 TPS” can be describing completely different amounts of useful work.

    TPS outside crypto

    The term predates Bitcoin by decades. Database engineers and performance testers use TPS to measure how many operations a server, payment switch or API can complete under load.

    In load testing, a team ramps up simulated users and watches TPS climb until response times degrade or errors appear. That peak is the system’s practical capacity. Visa uses the same framing when it says VisaNet can handle more than 65,000 transaction messages a second, a figure from the company’s own fact sheet.

    Blockchains borrowed the vocabulary. The difference is that a blockchain’s ceiling is set by consensus rules everyone can read, not by how many servers a company bought.

    How a blockchain’s TPS is set

    Every public blockchain has three dials that determine throughput. Change any one and TPS changes.

    Block size or gas limit. This caps how much data or computation fits in one block. Bitcoin caps block weight at 4 million weight units, which works out to a bit under 1 MB of typical transaction data. Ethereum uses a gas limit, which stood at 30 million for years and was raised in stages during 2025 to 45 million.

    Block time. This is how often a new block is produced. Bitcoin targets ten minutes. Ethereum produces a block every 12 seconds. Solana targets a 400-millisecond slot.

    Transaction size. A simple Bitcoin payment with one input and two outputs takes roughly 140 virtual bytes. On Ethereum a plain ETH transfer costs 21,000 gas, while a token swap through a decentralized exchange can burn 100,000 to 150,000 gas or more.

    Divide capacity per block by transaction size, then divide by block time, and you get a theoretical ceiling. Here is that math for the two largest networks.

    Network Capacity per block Typical transaction Max per block Block time Theoretical TPS
    Bitcoin (pre-SegWit math) 1,000,000 bytes ~250 bytes ~4,000 600 s ~7
    Bitcoin (SegWit payments) ~1,000,000 vbytes ~140 vbytes ~7,000 600 s ~12
    Ethereum, simple transfers 45,000,000 gas 21,000 gas ~2,140 12 s ~178
    Ethereum, DEX swaps 45,000,000 gas ~150,000 gas ~300 12 s ~25

    Notice how Ethereum’s “TPS” swings from 178 to 25 depending on what people are doing. That is why observed throughput sits well below any theoretical figure. Real blocks hold a mix of cheap and expensive transactions, and blocks are not always full.

    The famous “Bitcoin does 7 TPS” line comes from the first row. It was a fair ceiling in 2016. Since the SegWit upgrade in 2017 the practical limit is a bit higher, but typical observed throughput is still in the 3 to 7 range because blocks carry plenty of larger multi-input transactions.

    Theoretical versus live TPS

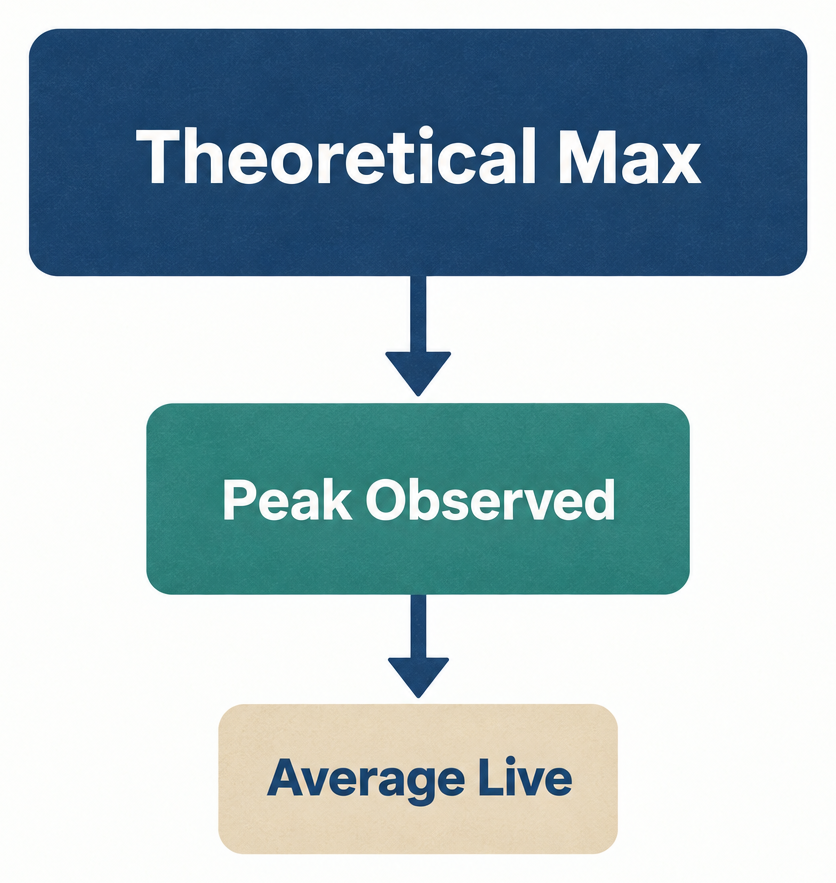
    Flow diagram showing three levels of blockchain TPS measurement: theoretical maximum, peak observed, and average live throughput

    We think of three different numbers whenever anyone quotes TPS.

    Theoretical maximum. What the rules allow if every block were stuffed with the smallest possible transactions. This is the number in whitepapers and marketing decks.

    Peak observed. The highest sustained rate seen on the live network, usually during a congestion event such as a popular token launch.

    Average live. What the chain actually does on a normal day. This is the only number that tells you what using the network feels like.

    Solana illustrates the gap. The project’s documentation and marketing have long cited a theoretical figure of 65,000 TPS. Explorer data over 2024 and 2025 shows total throughput commonly in the low thousands per second, and a large share of that total consists of validator vote transactions. Strip those out and user transactions typically land somewhere in the hundreds to low thousands.

    That is still far faster than Ethereum’s base layer. It is just not 65,000.

    Why vote transactions matter

    Solana validators vote on the chain’s state by sending transactions, and those votes are counted in the headline TPS on many dashboards. The votes are real work for the network, but they are not payments or trades. A reader comparing Solana’s number to Ethereum’s, where consensus votes travel outside the transaction count, is comparing different things.

    The honest comparison uses “non-vote” or “user” transactions. Most Solana explorers now show both.

    Ethereum rollups and “operations”

    Ethereum’s layer 2 networks introduced another wrinkle. A single transaction on a rollup can bundle several user actions. L2BEAT, the most widely used independent tracker, therefore reports “user operations per second” rather than raw TPS, and the combined figure across Ethereum rollups ran into the hundreds of operations per second during 2025.

    Again, useful data. Again, not directly comparable to a raw transaction count elsewhere.

    TPS across different blockchains

    The table below gives structural facts that do not change often, plus the observed ranges we consider defensible from public explorer data as of late 2025. Live figures move by the hour, so treat the ranges as orientation and check an explorer before relying on them.

    Network Block or slot time Typical observed TPS Claimed or theoretical ceiling Time to strong finality
    Bitcoin ~10 minutes 3 to 7 ~7 to 12 ~60 minutes (6 confirmations)
    Ethereum (layer 1) 12 seconds 15 to 30 25 to ~178 depending on mix ~13 minutes (2 epochs)
    Solana ~400 ms hundreds to low thousands (non-vote) 65,000 ~13 seconds (32 slots)
    Arbitrum One (optimistic rollup) sub-second sequencer tens to hundreds thousands 7-day challenge window for L1 withdrawals
    Base (optimistic rollup) 2 seconds tens to hundreds thousands 7-day challenge window for L1 withdrawals
    Bitcoin Lightning off-chain, instant not meaningfully capped not capped instant between channel partners

    A few observations.

    Bitcoin is slow by design. Ten-minute blocks and a small block size keep the cost of running a full node low, which is the point. Anyone with a modest laptop and a few hundred gigabytes of storage can verify the whole chain.

    Ethereum’s base layer deliberately stopped chasing raw TPS. Since the Dencun upgrade in March 2024, which added cheap “blob” data space for rollups, and the Pectra upgrade in May 2025, which doubled the blob target, the plan has been to scale through layer 2 networks rather than bigger layer 1 blocks.

    Solana’s speed comes from a different trade. Validators need powerful hardware and fast connections, which raises the cost of participating in consensus. Fewer people can run a validator, and the network has had several multi-hour outages between 2021 and February 2024.

    Lightning does not belong on the same axis at all. Payments happen in private channels and only the opening and closing touch the Bitcoin chain, so there is no block limit to divide by.

    Blockchains versus Visa, ACH and FedNow

    The “Visa does 65,000, Bitcoin does 7” comparison is everywhere. It is misleading in both directions.

    Payment rail Settlement model Stated or typical throughput What “final” means
    Visa (VisaNet) Authorization now, settlement in batches later Capacity of 65,000+ messages per second per Visa; average load in the low thousands per second based on reported annual volume Chargebacks possible for months
    ACH Batch files, settled same day or next day More than 30 billion payments a year per Nacha, processed in batches, so per-second rate is not the design goal Returns possible for days to 60 days
    FedNow (launched July 2023) Real-time gross settlement Designed for continuous instant payments Irrevocable on completion
    Bitcoin Global broadcast, probabilistic finality 3 to 7 TPS Practically irreversible after ~6 blocks
    Solana Global broadcast, fast finality Hundreds to low thousands (non-vote) Finalized in ~13 seconds

    Visa’s 65,000 is a capacity claim, not a daily average. The company reports annual volume in the hundreds of billions of transactions, and spreading that across a year works out to an average in the single-digit thousands per second.

    More importantly, a Visa authorization is a promise, not a settlement. Money moves between banks later, and the payment can be reversed. A confirmed Bitcoin or Solana transaction is settlement itself. Comparing a blockchain’s TPS to a card network’s message rate is a bit like comparing a courier’s deliveries to a call center’s phone calls.

    That said, the gap is real for retail payments. Nobody is going to run a coffee shop on Bitcoin’s base layer, which is exactly why Lightning and the Ethereum rollups exist.

    How layer 2 networks raise TPS

    A layer 2 is a separate network that processes transactions off the main chain and periodically posts a compressed record back to it. The main chain, or layer 1, becomes the court of final appeal rather than the place every trade happens.

    Optimistic rollups

    Arbitrum, Optimism and Base batch thousands of transactions, post the data to Ethereum, and assume the batch is valid. Anyone can challenge a fraudulent batch for a set period, typically seven days. Fast and cheap for users, but moving funds back to Ethereum through the standard bridge waits out that window.

    Zero-knowledge rollups zkSync, Starknet, Scroll and others post a cryptographic proof that the batch is valid. No challenge window is needed, so withdrawals to layer 1 can finish in hours. Generating proofs is computationally heavy, which has historically meant higher operating costs for the network.

    State channels

    Lightning is the clearest example. Two parties lock funds on-chain, exchange signed updates privately as often as they like, and settle once. Ideal for repeated small payments between known counterparties.

    Each approach lifts throughput by taking work off the base layer. The cost is new trust assumptions, which we cover under risks.

    Why TPS is the wrong single number

    Throughput tells you how many cars a highway moves per hour. It tells you nothing about how long your own trip takes, whether the road closes in bad weather, or who gets to add lanes.

    Latency and finality. A chain can confirm your transaction in a block within seconds yet not consider it final for minutes. Ethereum includes transactions every 12 seconds but reaches economic finality after about two epochs, roughly 13 minutes. Bitcoin never reaches absolute finality; the convention of waiting six blocks is a risk judgment, not a rule.

    Failed transactions. High TPS counts can include transactions that landed on-chain but did nothing useful. During the memecoin surge on Solana in April 2024, a large share of user transactions failed to execute because of network congestion, even as dashboards showed healthy throughput.

    Fees under load. Ethereum’s base layer processed roughly the same TPS in 2021 as it does today, but during the NFT boom a simple swap regularly cost more than $50 in gas. Throughput did not change; demand did. If you want the background on that boom, our “nft explained” piece covers what was actually being traded.

    Decentralization. The simplest way to raise TPS is to require bigger, faster validators. Every chain that advertises very high numbers has made that trade to some degree. Vitalik Buterin’s “scalability trilemma” framing, where you pick two of scalability, security and decentralization, is a simplification, but it is a useful one.

    Who is counting. We have already seen vote transactions, bundled operations and theoretical ceilings. Always ask what was counted and over what window.

    What TPS means for a US reader

    Most Americans interact with a blockchain’s throughput in two moments: when they move money during a busy period and when they file taxes.

    Congestion and your money

    When a market crashes, everyone tries to transact at once. Base-layer fees spike and transactions queue. During the May 2022 collapse of the Terra ecosystem, and again in the November 2022 FTX failure, users reported long waits and high fees across several networks while trying to move funds.

    If you are considering whether a sell-off has reached the point of forced selling, our “capitulation definition” explainer describes that stage of a market. The practical point here is that in those hours, the network’s advertised TPS is irrelevant. What matters is whether your transaction gets into a block at a fee you can stomach.

    Traders who rely on speed feel this most. A “scalping trading strategy” that depends on getting in and out within seconds is hostage to the chain’s latency and fee market, which is why most high-frequency crypto trading happens on centralized exchanges rather than on-chain.

    Taxes: every fast transaction is still a taxable event

    Under IRS Notice 2014-21, the IRS treats cryptocurrency as property. Every sale, swap or use of crypto to pay for something is a disposal that can trigger a capital gain or loss.

    A high-TPS chain does not change that rule. It changes how many taxable events you can create. Someone who makes 400 token swaps in a month on Solana or Base has 400 disposals to report, each with its own cost basis and holding period.

    Gas fees add another layer. Paying a fee in ETH or SOL is itself a disposal of that ETH or SOL. In practice most tax software adds fees to your cost basis or subtracts them from proceeds, but you still need the records.

    Starting with 2025 transactions, custodial brokers such as US exchanges report gross proceeds on Form 1099-DA, with cost basis reporting phasing in for 2026. Our “1099-da” guide walks through the form. Self-custody wallets and decentralized exchanges do not issue it, and the IRS rule that would have required certain DeFi front-ends to report was repealed by Congress in April 2025. The reporting burden for on-chain activity therefore sits with you.

    One more unsettled area: the IRS has not issued specific guidance on whether bridging the same asset from layer 1 to a layer 2 is a taxable event. Many practitioners treat a like-for-like bridge as a non-taxable transfer. Keep records either way.

    No deposit insurance, no required speed

    No federal law sets a minimum TPS for a blockchain, and no regulator certifies throughput claims. The figures in a project’s marketing are not audited disclosures.

    More broadly, crypto held on-chain or at an exchange is not FDIC insured and not SIPC protected. Both agencies have said so publicly. A fast chain that halts, gets exploited or simply loses user interest can leave holders with tokens worth nothing, and no insurance fund steps in.

    Before you rely on a fast chain

    A high TPS figure says nothing about whether a network stays online, whether your transaction will execute during a rush, or whether the token holds any value. Crypto can lose all of its value and is not FDIC or SIPC insured.

    Risks that scale with throughput

    Outages. Solana’s history shows that pushing hardware to the edge can bring the whole network down. Its February 2024 outage lasted around five hours. Bitcoin and Ethereum have had no comparable base-layer halts in years, partly because they ask less of each node.

    Layer 2 trust assumptions. Most rollups still run a single sequencer operated by the project, and many retain upgrade keys that could change the rules. L2BEAT publicly grades rollups on these points, and as of late 2025 only a minority had reached its most decentralized stage. Your transactions are fast, but a centralized operator sits in the path.

    Bridges. Moving assets between chains to chase throughput means using bridges, which have been the single largest source of crypto theft. The Ronin bridge lost roughly $600 million in March 2022 and the Wormhole bridge about $320 million in February 2022. A high-TPS destination is worthless if the route there is unsafe.

    Spam and inflated metrics. Because TPS is a marketing number, some networks have seen bursts of near-zero-value transactions that lift the count without lifting adoption. A dashboard spike is not proof of real users.

    Validator concentration. Heavy hardware requirements concentrate validators in data centers run by a handful of hosting providers. That is a censorship and availability risk that no TPS chart shows.

    How to check a TPS claim yourself

    You do not need special tools. Every public chain has a block explorer, and the arithmetic takes a minute.

    How to verify a blockchain's TPS

    1. Open a public block explorer for the chain and find the latest blocks.
    2. Note the average time between blocks over the last 20 or so blocks.
    3. Note the number of transactions in each of those blocks, and exclude validator votes if the explorer separates them.
    4. Divide total transactions by total seconds to get live TPS.
    5. Compare that figure with the project’s advertised number and with the theoretical ceiling from its block size and block time.

    If the advertised number is ten or a hundred times what you just calculated, you are looking at a theoretical ceiling or a testnet result, not the live network.

    Common TPS calculation pitfalls

    We see the same mistakes repeated in articles, pitch decks and forum posts.

    Mixing windows. A one-second peak during a token launch is not an average. Insist on the window: one minute, one hour, one day.

    Counting consensus traffic. Validator votes, system transactions and internal calls can double or triple a headline number.

    Quoting testnets. Test networks run on controlled hardware with simulated load. Mainnet, with adversarial traffic and real economic stakes, is always slower.

    Ignoring failures. A transaction that lands but reverts still counts on many dashboards. Useful throughput is lower.

    Comparing settlement to messaging. Visa messages, ACH batches and blockchain confirmations are different units. Line them up only after defining what each one guarantees.

    Treating TPS as speed. Throughput and latency are separate. A chain with 2,000 TPS and 15-minute finality can feel slower for a single withdrawal than one with 30 TPS and quick finality.

    Where blockchain throughput is heading

    Ethereum’s roadmap continues to add blob capacity for rollups, with data-availability sampling in development to let the network carry far more rollup data without raising hardware requirements for ordinary nodes. The stated goal is to scale through layer 2 rather than inflate base-layer blocks.

    Solana’s developers have been working on an alternative validator client and network upgrades aimed at both higher throughput and better resilience under load, after the congestion problems of 2024.

    Bitcoin’s base layer is unlikely to change meaningfully. Throughput growth there happens on Lightning and other second-layer systems.

    None of this tells you what any token will be worth, and we do not make price calls. It does mean that the TPS tables above will keep moving, and the counting conventions will keep shifting with them. The habit worth keeping is to ask three questions of every number: what was counted, over what window, and on which network.

    FAQ

    What is transactions per second in simple terms?

    It is the number of transactions a network confirms every second, averaged over some period. For a blockchain, the ceiling is set by how much fits in a block and how often blocks are produced.

    Which blockchain has the highest TPS?

    Among major networks, Solana consistently shows the highest observed throughput, in the hundreds to low thousands of user transactions per second once validator votes are excluded. Its 65,000 figure is a theoretical ceiling, not a daily average. Several newer chains claim higher ceilings, but claims and live mainnet data are different things.

    Why does Bitcoin only handle about 7 transactions per second?

    Bitcoin produces a block roughly every ten minutes and limits block weight to 4 million units. Divide the roughly 2,000 to 7,000 transactions that fit in a block by 600 seconds and you get single digits. The limit is deliberate, to keep the cost of running a full node low.

    Is a higher TPS always better?

    No. Higher throughput usually requires more powerful validators, which reduces the number of people who can participate in consensus, and it does not guarantee uptime or low fees during a rush. Finality time, fee stability and decentralization matter as much as the raw count.

    Does a blockchain’s TPS affect my US taxes?

    Indirectly. The IRS treats crypto as property under Notice 2014-21, so each swap or sale is a taxable event regardless of the chain. Fast, cheap networks make it easy to rack up hundreds of disposals that all need cost-basis records. Custodial exchanges report proceeds on Form 1099-DA; on-chain and self-custody activity you must track yourself.

    How does TPS differ from finality?

    TPS is how many transactions get processed per second. Finality is how long until a transaction cannot be reversed. Ethereum includes transactions every 12 seconds but finalizes after about 13 minutes, while Bitcoin’s six-confirmation convention takes about an hour. A withdrawal from an optimistic rollup to Ethereum through the standard bridge waits a seven-day challenge window no matter how fast the rollup itself runs.