Financial dispute resolution covers every method of settling a money disagreement short of a full trial: a written complaint, regulator mediation, private mediation, binding arbitration and small claims court. For most borrowers the cheapest and fastest route is a dated written dispute under the law that covers the product, followed by a complaint to the Consumer Financial Protection Bureau if the company stonewalls. Arbitration and court come last because they cost time and money, and your loan contract often decides which of the two you can use.
Cheapest routeWritten dispute, no fee
CFPB response target15 days
Credit report dispute30-day investigation
Small claims limits$2,500 to $25,000
As ofOctober 2026
What counts as a financial dispute
A financial dispute is any disagreement with a lender, bank, card issuer, servicer, debt collector or broker about money you owe or money owed to you. Common borrower cases include fees charged that the contract never disclosed, payments applied late or lost, a loan reported inaccurately to the credit bureaus, and a debt collector chasing a balance you already paid or never owed.
The amount in play is usually small, which is exactly why the process you choose matters. Here is what a typical disputed loan looks like.
Amount
Fee or APR
Term
Total repaid
$500 payday loan
$75 fee, about 391% APR
14 days
$575
Same loan, rolled over twice
$225 in fees
42 days
$725
The APR math is plain: $75 on $500 is 15% for two weeks, and there are about 26 two-week periods in a year, so 15% times 26 is roughly 391%. If the lender rolled the loan without your consent, the extra $150 in fees is the sum in dispute, and that figure should drive how much time and money you spend recovering it.
Before you borrow
Most loan and card contracts contain a mandatory arbitration clause that waives your right to sue in court or join a class action. Read for it before signing, and check whether the contract lets you opt out in writing within 30 to 60 days.
Route 1: A written dispute under the law that applies
Federal consumer law gives you dated deadlines that force a response, and you need no lawyer to use them.
Credit card billing errors: under the Fair Credit Billing Act, write to the issuer within 60 days of the statement; it must acknowledge within 30 days and resolve the matter within two billing cycles, never more than 90 days.
Unauthorized or wrong electronic payments: under the Electronic Fund Transfer Act and Regulation E (12 CFR 1005), report within 60 days; the bank generally has 10 business days to investigate or must give provisional credit.
Credit report errors: under the Fair Credit Reporting Act, the bureau must investigate within 30 days, or 45 days if you send extra information.
Collection claims: under the Fair Debt Collection Practices Act and Regulation F, a written dispute within 30 days of the validation notice means the debt collector must stop collecting until it verifies the debt.
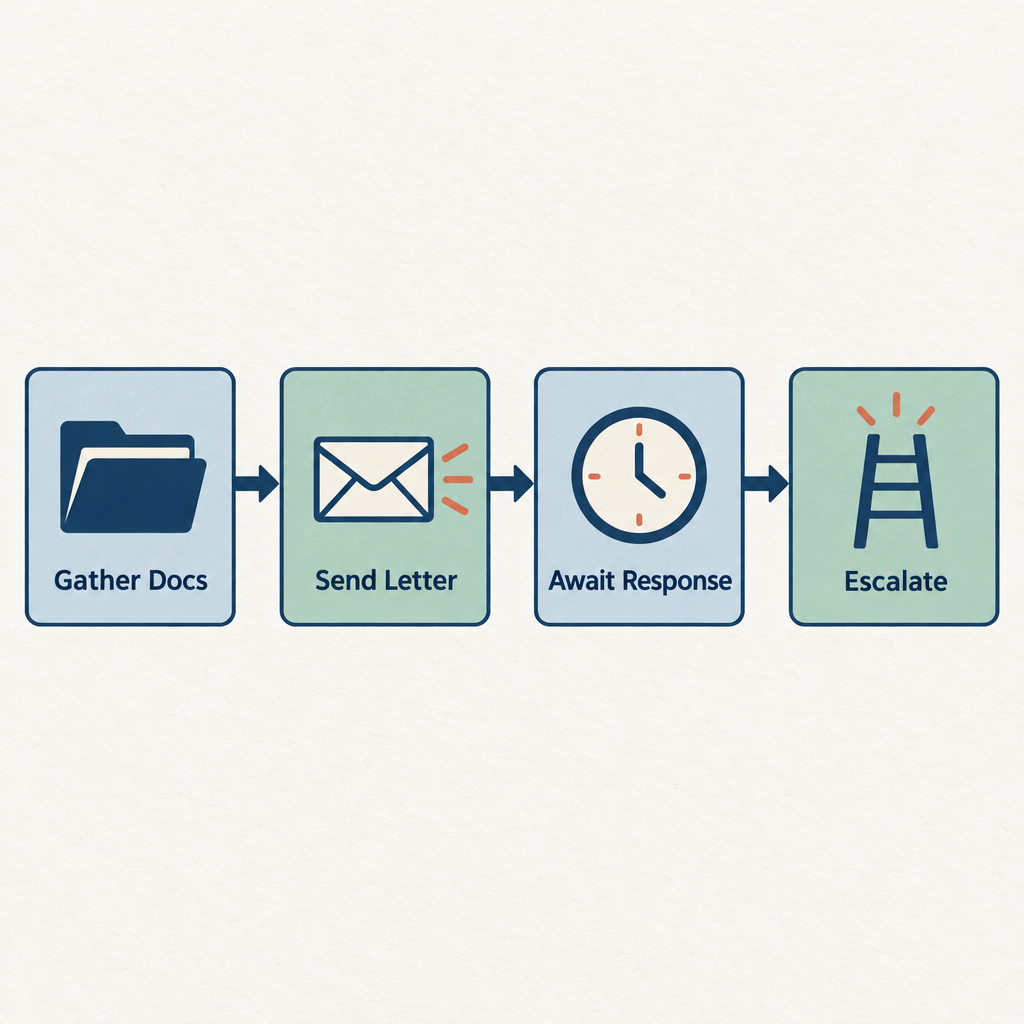
Send every dispute by a method that gives you proof of delivery, keep copies of statements, contracts and screenshots, and date everything. Those documents become your case file for every later step.
Route 2: Regulator complaints
The CFPB complaint portal forwards your complaint to the company, which is expected to respond within 15 days, and if that initial response is not final, the company has up to 60 days to provide a final response. Banks answer to the Office of the Comptroller of the Currency, the Federal Reserve or the FDIC, credit unions to the National Credit Union Administration, and licensed lenders to your state regulator, whose license lookup also tells you whether the company is legally operating at all. Brokers and investment accounts fall under FINRA and the Securities and Exchange Commission.
Route 3: Mediation
Mediation is voluntary and non-binding; a neutral mediator helps both parties reach a settlement without ruling on who is right. FINRA runs a mediation program for investor disputes, the American Arbitration Association offers consumer mediation, and many counties have community mediation centers that charge little or nothing. If no deal emerges, you lose nothing but time and keep every other option.
Route 4: Arbitration
Arbitration is private and binding: an arbitrator hears both sides, reviews the documents and issues an award. Under the Federal Arbitration Act, a court will enforce that award and will vacate it only on narrow grounds such as fraud or arbitrator misconduct, so you get one real opportunity to present your evidence. AAA’s Consumer Arbitration Rules cap the consumer’s share of filing fees at a few hundred dollars and put the rest on the business, and FINRA’s simplified process for smaller claims is decided on documents alone with no hearing.
Two groups keep their court rights no matter what the contract says. The Military Lending Act bans mandatory arbitration for active-duty servicemembers and their dependents, and the Servicemembers Civil Relief Act adds protections on rates and default judgments.
Route 5: Small claims court
Small claims court is for borrowers whose contract has no arbitration clause, who opted out, or who are being sued. Filing fees vary widely by state, from roughly $20 to $60 in Kentucky to $42 to $300 in Tennessee once local litigation taxes are added, lawyers are usually optional, and the dollar limit ranges from about $2,500 in Kentucky to $25,000 in Tennessee. Judges here will also apply state usury laws, which is why a lender that charged an illegal rate often settles rather than defend it.
State availability
A payday loan is banned or capped at 36% in roughly 20 states and the District of Columbia, so a lender collecting payday fees there has a weak position in any forum. Courts will generally strike an arbitration clause that explicitly waives your statutory rights under state lending law, but arbitration can still limit what you recover in practice by barring class actions, capping damages or restricting remedies, and arbitrators are not always bound to apply state law the way a judge would.
Cheaper options first
Start with a free written dispute and a CFPB complaint before paying any filing fee.
Nonprofit credit counseling agencies and legal aid offices handle borrower disputes at no cost.
Your state attorney general’s consumer office mediates many lender complaints for free.
How to escalate a borrower dispute
Send a dated written dispute citing the law that applies and keep proof of delivery.
File a CFPB complaint if the deadline passes without a real answer.
Report the company to the state regulator and check its license.
Offer mediation in writing.
Choose arbitration or small claims court based on the contract and the amount at stake.
FAQ
What are the three types of dispute resolution?
Negotiation, mediation and arbitration. Negotiation is direct talks between the parties, mediation adds a neutral who helps but does not decide, and arbitration adds a neutral who issues a binding decision. Court litigation is the fourth, formal option.
What happens after a dispute resolution hearing?
The arbitrator issues a written award, which FINRA generally requires within 30 business days of the record closing. The losing party must pay or comply, and under the Federal Arbitration Act you have three months to ask a court to vacate the award on limited grounds.
How much does it cost to hire a private FDR?
“FDR” is mostly a UK family-court term. In the US, private mediators bill hourly and the parties usually split the cost, while community mediation centers and regulator programs are often free. Consumer arbitration fees are capped by the forum’s rules, with the business paying most of them.
What is a financial dispute?
Any disagreement over money with a lender, bank, servicer, collector or broker, from an undisclosed fee to an inaccurate credit entry. Most are resolved by a written dispute under federal consumer law, and only a minority ever reach arbitration or court.
Fast money is possible, but the honest version looks like selling things, working shifts that pay quickly, and claiming cash you already own. This list ranks 17 ways to make money fast by how soon the money hits your account, how much you can realistically clear, and what each one costs you. We also show what borrowing instead would cost, so you can compare before you decide.
Fastest payoutsame day, in cash
Realistic one-day range$50 to $500
Typical gig app cash-out feeunder $2
Payday loan APRabout 391%
Credit union PAL APR cap28%
As of2026
Before you chase fast cash
Any offer that asks you to pay first, deposit a check and send part of it back, or buy gift cards to “unlock” earnings is a scam. Real work never costs you money up front, and real payouts never need a fee to release them.
How we ranked these
We scored every method on four things. Speed to first dollar matters most for someone who needs rent money by Friday. Then we looked at the realistic amount a first-timer can clear in a week, the fees and taxes that eat into it, and the risk of wasting your time or getting scammed.
Everything here is legal in all 50 states unless we say otherwise. Nothing requires a credit check, and nothing on this list is a loan except one pawn option that we flag clearly.
Our top pick is selling things you already own, locally, for cash. It beats every app on speed, has no fees, and does not create a tax bill in most cases. The rest of the list fills in once your closet and garage are empty.
Quick comparison
#
Method
First payout
Realistic first-week range
The catch
1
Sell items locally for cash
Same day
$50 to $500+
Buyers haggle and flake
2
Donate plasma
Same day (prepaid card)
$100 to $400 as a new donor
Health screening, twice-a-week limit
3
Same-day shift apps
1 to 3 days
$100 to $400
Shifts go fast, need photo ID
4
Food and grocery delivery
Same day with instant pay
$100 to $500
Gas, car wear, small cash-out fee
5
Sell gold, silver, jewelry
Same day
Depends on weight
Buyers pay below melt value
6
Pawn an item (a loan)
Same day
$20 to $300 typical
High interest, you can lose the item
7
Drive for Uber or Lyft
3 to 10 days
$200 to $600
Approval takes days, car costs
8
Odd jobs and TaskRabbit
1 to 7 days
$100 to $400
Physical work, builds slowly
9
Dog walking and pet sitting
2 to 7 days
$50 to $300
Rover keeps 20%
10
Babysitting
Same day if local
$60 to $300
Trust takes time to build
11
Extra shifts or overtime
Next paycheck
Varies
Only if your employer allows it
12
Tutoring
1 to 7 days
$50 to $300
Need a subject you can teach
13
Online freelance work
5 to 14 days
$0 to $500
Platform holds and fees
14
Paid studies and opinions
Same day to 2 weeks
$20 to $150
Low hourly rate, screen-outs
15
Resell online (eBay, Poshmark, Etsy)
3 to 14 days
$50 to $400
Fees, shipping, slower
16
Bank account bonuses
2 to 12 weeks
$100 to $300
Direct deposit rules, taxable
17
Claim money you are owed
2 to 12 weeks
$0 to thousands
Paperwork, waiting
Ways that can pay today
1. Sell things you already own, locally, for cash
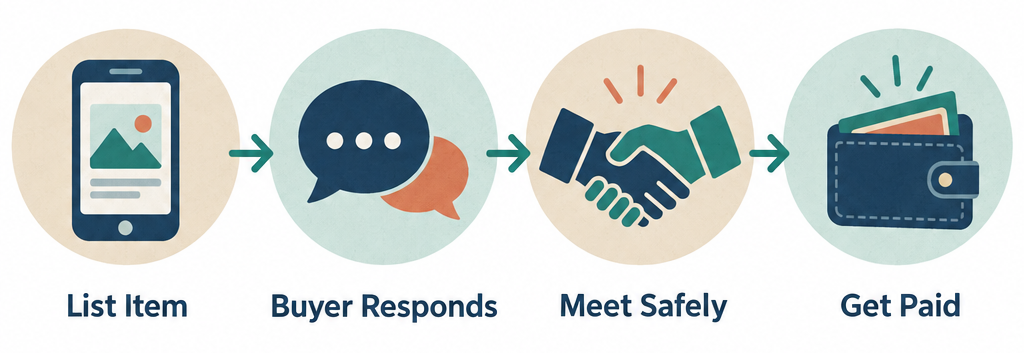
This is the top pick because nothing else is this fast or this free. Facebook Marketplace, Craigslist, and OfferUp charge no fee for local pickup sales. You list in the morning, meet in a public place in the afternoon, and walk away with cash or an instant transfer.
What sells the same day: working phones and laptops, game consoles, power tools, bikes, furniture, baby gear, and name-brand sneakers. Price 10% to 20% under the other listings in your area and say “pickup today” in the title. Buyers in a hurry search for that.
Three safety rules. Meet at a police station lot or a busy store entrance. Take cash or a transfer you can see land in your own banking app before you hand over the item. Never accept a check or an overpayment request.
Taxes are usually not an issue here. The IRS does not tax a loss, and most used household goods sell for less than you paid. If you sell a collectible or an item for more than you paid, that gain is reportable.
2. Donate plasma
Plasma centers pay on the day of your visit, typically to a prepaid debit card. Pay varies by city and company, but $30 to $100 per visit is the common range, and most centers run new-donor promotions that stack several hundred dollars across your first month.
Under FDA rules in 21 CFR 630.15, you can donate plasma no more than twice in a seven-day period. You need a valid government photo ID, proof of address, and a Social Security number. First visits include a physical and a health questionnaire, so plan on two to three hours. Repeat visits take about an hour.
Plasma pay is taxable income even though centers rarely send a tax form. Keep a simple record of what you received during the year.
3. Same-day shift apps
Apps like Instawork, Wonolo, and GigSmart list warehouse, event, catering, and cleaning shifts that start within hours. Many pay the day after the shift, some pay sooner, and the rates usually sit a few dollars above your state minimum wage.
You will need a photo ID, a smartphone, and reliable transportation. Shifts fill fast, so turn on notifications and claim early. Some shifts classify you as a W-2 employee of the staffing company and some as an independent contractor. Check which one before you accept, because contractors owe self-employment tax and get no overtime.
Local day-labor halls and temp agencies are the no-app version. Walk in early, bring ID, and ask about daily pay.
4. Deliver food or groceries with instant cash-out
DoorDash, Uber Eats, Instacart, and Amazon Flex all let you move earnings to a debit card the same day. DoorDash’s Fast Pay and Uber’s Instant Pay charge a small flat fee per transfer, usually under $2, while standard weekly deposits are free. Approval takes a few hours to a few days depending on how quickly the background check clears.
Delivery pays best on Friday and Saturday evenings and during bad weather. Gross earnings of $15 to $25 an hour are common in busy metros. Subtract gas and wear on your car and the net is lower. The IRS standard mileage rate exists for exactly this, so track every mile from your first delivery to your last.
Amazon Flex works a bit differently. You reserve delivery blocks, typically two to four hours, and pay goes out twice a week. It is slower to start but the pay per block is posted before you accept.
5. Sell gold, silver, or jewelry
Gold moves at the spot price, and buyers pay a percentage of melt value based on weight and purity. A reputable buyer tests the metal in front of you and quotes a price per gram. Get two or three quotes, because the spread between a local jeweler, a coin shop, and a mail-in buyer can be wide.
Mail-in gold services pay slower and you lose leverage once the package is gone. Local coin shops usually pay the same day in cash or check. Never sell at a hotel “gold party” event.
Sterling silver flatware, old class rings, broken chains, and single earrings all count. Gemstones usually add little unless they are certified.
6. Pawn an item (this one is a loan)
A pawn shop hands you cash the same day against an item you leave as collateral. No credit check, no income check. If you repay the loan plus interest within the term, usually 30 to 90 days, you get the item back. If you do not, the shop keeps it and the debt ends there. Nothing goes to your credit report either way.
Pawn interest is set by state law and the range is huge, from a few percent a month in some states to much higher in others. Under the Truth in Lending Act and Regulation Z, the shop must give you a written disclosure of the finance charge and APR. Read it before you sign.
Pawning is better than a payday loan only because the downside is capped at losing the item. Selling the item outright usually pays more than pawning it.
Ways that can pay this week
7. Drive for Uber or Lyft
Rideshare pays more per hour than delivery in most cities, but it starts slower. You need a car that passes the company’s age and inspection rules, a clean driving record, and a background check that can take several days to clear. After that, instant cash-out works the same way it does for delivery.
Airport runs, early mornings, and surge pricing after concerts and games move the needle. Full-time drivers in large metros report gross earnings in the $20 to $30 per hour range before expenses. Your real number depends on your city and how much you drive during slow hours.
Rideshare background checks are consumer reports under the Fair Credit Reporting Act. If you are rejected based on the report, the company must send you a copy and a chance to dispute errors.
8. Odd jobs through TaskRabbit, Nextdoor, and neighbors
Moving help, furniture assembly, yard cleanup, snow shoveling, gutter cleaning, and junk hauling all pay the same day in cash or Venmo when you book directly with a neighbor. Post in your local Nextdoor or Facebook group with a short list of what you do and your rate.
TaskRabbit adds structure and a steady flow of clients, but it takes a few days to get approved and the site collects payment and releases it after the task is complete. Taskers set their own hourly rates, and furniture assembly and moving help are the categories with the most demand.
Bring your own tools, show up on time, and ask for a review. Three good reviews in your first week turn this into a reliable side income line.
9. Walk dogs and pet-sit
Rover connects you with owners who need dog walking, drop-in visits, and overnight boarding. The company keeps 20% of each booking and pays you two days after a service completes. Walks commonly run $15 to $30 and overnight boarding $30 to $75 a night, with you setting the price.
Getting your first booking takes a few days because owners read profiles and want to meet you. Skip the app and ask neighbors directly if you need money sooner. Cat drop-ins while people travel are the easiest entry point.
Boarding dogs in your home may violate a lease or a local ordinance, so check first.
10. Babysit or do evening childcare
Families pay in cash or by app the same night, and rates of $15 to $25 an hour are normal in most of the country, higher in big cities. Care.com and Sittercity list jobs, but the fastest route is telling every parent you know that you are available this weekend.
Date-night sitting, school pickup, and overnight care for parents who work hospital shifts fill up first. A CPR certification from the Red Cross or American Heart Association takes a few hours and lets you charge more.
11. Pick up extra shifts, overtime, or an employer advance
The quickest raise is more hours at the job you already have. Under the Fair Labor Standards Act, nonexempt employees earn at least one and a half times their regular rate for every hour over 40 in a workweek. Ask your manager for open shifts, holiday coverage, or a temporary second role.
Also ask payroll about earned wage access. Some employers let you draw part of your earned pay before payday at no cost. That is the cheapest advance in existence. If the option goes through a third-party app that charges express fees or asks for tips, treat it like the cash advance apps in our cost table below.
12. Tutor a subject you know well
Parents pay $25 to $50 an hour for in-person help with math, reading, SAT prep, and languages, and they pay by app or cash after each session. Wyzant, Varsity Tutors, and local Facebook parent groups generate leads. College students, teachers, and anyone with a technical background can start this week.
Online tutoring platforms pay less per hour and hold payment for a week or more. Direct clients pay faster and you keep the whole rate.
13. Freelance work online
Upwork, Fiverr, and Freelancer.com let you sell writing, design, data entry, bookkeeping, video editing, and admin work from anywhere. The catch is speed. Upwork holds payment for days after a client approves a milestone, and both big platforms take a percentage of what you earn. Your first client can take a week to land and your first dollar two weeks.
This is a stronger medium-term answer than a this-week answer. Price competitively on your first three jobs to collect reviews, then raise rates.
Two scam red flags: a “client” who wants to move the conversation off the platform right away, and any job that sends you a check to buy equipment.
14. Paid research studies, user tests, and opinions
UserTesting pays about $10 for a recorded 20-minute website test, and live interviews pay more. Respondent and User Interviews list paid research sessions that often pay $50 to $150 for an hour, though you have to qualify through a screener. University psychology departments and medical schools run paid studies you can find through ClinicalTrials.gov and campus job boards.
Survey sites that pay for your opinions are the weakest option here. Points add up slowly, cash-out minimums delay payment, and the effective hourly rate often lands below minimum wage. Use them while waiting for something better, not instead of it.
Ways that pay in two to six weeks
15. Resell online through eBay, Poshmark, or Etsy
Online resale reaches more buyers than a local post, but money moves slower and fees take a slice. Poshmark keeps a flat $2.95 on sales under $15 and 20% on sales of $15 or more. Etsy charges a $0.20 listing fee plus a 6.5% transaction fee, then payment processing on top. eBay’s final value fee runs in the low to mid teens as a percentage in most categories, and payouts land in your bank a few days after the sale.
Shipping, packaging, and returns add cost and time. Clothing, collectibles, electronics, and handmade goods do best. If you need money this week, sell locally first and move the leftovers online.
16. Bank account bonuses
Banks pay $100 to $300 to open a checking account and meet a direct deposit requirement within 60 to 90 days. Credit unions and regional banks often match the big names. Read the fine print for monthly fees, minimum balances, and how long you must keep the account open to avoid a clawback.
The bonus is interest income and the bank sends you a Form 1099-INT if the total reaches $10. Bonuses are slow money, but they are nearly risk-free compared with everything else on this list.
17. Claim money you are already owed
Every state treasurer runs an unclaimed property database. Old utility deposits, forgotten bank accounts, uncashed paychecks, and insurance refunds sit there until someone claims them. Search your name at your state’s official site and at MissingMoney.com, which several states feed. Claims take weeks, but they are free.
Check these too: a federal or state tax refund you never filed for, class action settlements at the official settlement site, a security deposit a landlord still owes you, and pay stubs for unpaid overtime. If you lost work, file for unemployment insurance the same week. Benefits are taxable but they are yours.
How to vet any fast-cash offer in five minutes
Search the company name plus “scam” and “FTC”.
Confirm you never pay anything up front, including training or equipment.
Refuse any job that sends you a check and asks you to forward money.
Check how and when you get paid, in writing, before you start.
Verify a lender on NMLS Consumer Access and your state regulator’s license lookup.
If earning is not enough: what borrowing really costs
Sometimes the number you need is bigger than what one week of hustle can cover. Compare the real cost of each quick borrowing option before you reach for one. The APR figures below use the standard formula: fee divided by the amount, divided by the days, times 365.
Option
Amount
Fee or APR
Term
Total repaid
Credit union payday alternative loan
$300
28% APR plus $20 application fee
3 months
About $334
Credit card cash advance
$300
5% fee plus about 30% APR
30 days
About $322
Cash advance app
$100
$5 express fee plus $2 tip
10 days
$107, about 256% APR
Payday loan
$300
$15 per $100 borrowed
14 days
$345, about 391% APR
The payday math in plain words: $45 on $300 is 15%. A 14-day term fits into a year about 26 times. Fifteen percent times 26 is roughly 391%. The CFPB uses this same example to explain why a payday loan is the most expensive line on the table, and its research found that most payday borrowers roll over or re-borrow within two weeks.
Cash advance apps look cheap at $7 on $100 until you annualize it. The CFPB’s 2024 analysis of earned wage access products found an average APR above 100% once express fees and tips were counted, and heavy users took more than two dozen advances a year.
Credit card cash advances have no grace period. Interest starts the day you take the cash, and most issuers charge a higher APR for advances than for purchases.
The credit union loan wins on cost. The National Credit Union Administration caps payday alternative loans at 28% APR, with an application fee of no more than $20, amounts from $200 to $1,000, and terms of one to six months. You need to be a member, and some credit unions require a month of membership first.
Cheaper options first
Ask your employer about a no-fee pay advance before any app.
Call utilities, landlords, and lenders for a hardship plan; many have one.
Dial 211 for local rent, food, and utility assistance, and check LIHEAP and SNAP.
A nonprofit credit counselor can set up a plan at little or no cost.
Leave retirement money alone if you can. Pulling from a 401(k) or IRA before age 59½ triggers income tax plus a 10% additional tax under Internal Revenue Code Section 72(t) in most cases. A 401(k) loan, if your plan offers one, avoids the penalty but puts your retirement savings at risk if you leave the job and cannot repay quickly.
State rules that change the picture
Payday lending is not available everywhere. New York, Pennsylvania, New Jersey, Massachusetts, and a growing group of other states cap small-loan rates at or near 36% APR, which keeps storefront payday lenders out. Those caps come from state usury laws, and the ceiling is different in every state, so a lender that is legal in Texas can be a felony operation in New York.
Plasma donation is legal in every state, but centers set their own age minimums, usually 18, and a few states require 19. Pawn interest rates and redemption periods are set state by state. Gig driving rules on minimum pay, insurance, and worker classification differ too, with California, Washington, and New York City each having their own regimes. Check your state before you count on a specific rate.
Members of the military and their dependents get extra protection. The Military Lending Act caps most consumer loans at a 36% military APR, including payday loans and some cash advance products.
Taxes on fast money
The IRS taxes income from gig work, freelancing, plasma, tutoring, and resale profits, with or without a tax form. If your net self-employment earnings reach $400 for the year, you file Schedule SE and pay self-employment tax of 15.3% on top of income tax. If you expect to owe $1,000 or more, the IRS wants quarterly estimated payments.
Tax forms are less common than people think. Under the tax law signed in July 2025, the Form 1099-K threshold for payment apps and marketplaces returned to $20,000 and more than 200 transactions. The same law raises the Form 1099-NEC threshold from $600 to $2,000 for payments made in 2026. Not getting a form does not make the income tax-free. It just means you have to track it yourself.
Keep mileage, phone, and supply records. Those deductions are the difference between a gig that nets $18 an hour and one that nets $12.
Your rights while earning fast
Employees, including temp and shift-app workers paid on a W-2, are covered by the Fair Labor Standards Act. That means at least the federal minimum wage of $7.25 or your higher state minimum, overtime past 40 hours, and pay on the regular schedule your state requires. Unpaid wages can be reported to the Department of Labor’s Wage and Hour Division or your state labor agency.
Independent contractors on gig apps have fewer protections, but a few still apply. Background checks run by Checkr or similar companies fall under the Fair Credit Reporting Act, so you get a copy of the report and a chance to dispute mistakes before you are deactivated. Deposits to a debit card are electronic fund transfers, and the Electronic Fund Transfer Act gives you the right to dispute errors with your bank within 60 days of the statement.
If you borrow instead, the Truth in Lending Act requires a written disclosure of the APR and total finance charge before you sign. The Equal Credit Opportunity Act bars lenders from treating you differently because of race, sex, age, marital status, or because your income comes from public assistance.
Report scams to the FTC at ReportFraud.ftc.gov and to the FBI’s Internet Crime Complaint Center. Complaints about lenders, cash advance apps, and debt collectors go to the CFPB’s complaint portal. The FTC’s 2024 fraud data showed reported losses topping $12.5 billion, with job and business opportunity scams among the fastest growing. Any “investment” that promises daily returns from a stranger online is almost always a ponzi scheme and should be treated as one.
FAQ
How to make $1,000 dollars ASAP?
Stack the fastest items on this list. Sell electronics, tools, and furniture locally for $300 to $500 in a day, donate plasma twice in a week for roughly $100 to $150 at standard rates, more if a new-donor bonus applies, and run delivery or same-day shifts for the rest. One week is realistic for most people with a car and a closet full of things they do not use. Without a car, pair selling with shift apps and odd jobs for neighbors.
How do I make money right now ASAP?
Same-day cash comes from three places: selling something locally, a plasma center, and a pawn shop. Delivery apps pay the same day too once you are approved, which can take hours to days. Everything else on this list takes at least a day or two.
How can I make $100 a day?
Four to six hours of delivery during peak meal times clears $100 gross in most cities, before gas. Two dog walks and a drop-in visit on Rover get there. A single same-day warehouse or event shift at a few dollars above minimum wage usually lands close. Combining two of these is the most reliable path on days when one is slow.
How to make $1,000 a day fast?
No legitimate method on this list produces $1,000 in a day from a standing start. Selling a car, a high-end bike, or a watch can, but that is converting an asset, not earning. Anyone promising $1,000 a day from a phone, a course, or a crypto “opportunity” is selling the promise, not the income. Treat the claim as a red flag and report it if money is requested up front.
A credit union is a not-for-profit financial cooperative owned by the people who keep money in it, and joining usually takes one small deposit plus proof that you fit its membership rules. This explainer covers what a credit union is, who qualifies, what membership actually costs, the loan rate caps that make credit unions cheaper than many lenders, and the federal laws that protect you once you are a member.
Ownershipmembers, one vote each
Typical joining deposit$5 to $25
Federal loan rate cap18% APR
Payday alternative loan cap28% APR
Deposit insurance$250,000 per member
As ofOctober 2026
What a credit union is
The credit union definition in federal law is a cooperative association organized to promote thrift among its members and create a source of credit for provident purposes. That language comes from the Federal Credit Union Act, passed in 1934 and still the governing statute for every federally chartered credit union.
In plain words, a credit union is a bank-like institution that its customers own. When you join, you buy one share, usually priced between $5 and $25, and that share makes you a part owner with one vote at the annual meeting. There are no outside shareholders. Any surplus goes back to members as lower loan rates, higher savings yields, fewer fees, or occasional bonus dividends.
Credit unions offer most of what a bank does: checking (called a share draft account), savings (a share account), certificates (the credit union version of a CD), credit cards, auto loans, mortgages, personal loans and mobile banking. Many smaller ones also offer services banks rarely bother with, such as free financial counseling or small emergency loans.
The National Credit Union Administration (NCUA) charters and supervises federal credit unions. State-chartered credit unions answer to their state regulator, and nearly all of them also carry NCUA insurance. NCUA data shows roughly 4,400 federally insured credit unions serving more than 140 million members as of 2025.
Credit union vs bank: the differences that matter
Feature
Credit union
Bank
Who owns it
Members
Shareholders
Profit goal
Return value to members
Return profit to investors
Who can use it
People who meet eligibility rules
Anyone
Deposit insurance
NCUSIF, up to $250,000
FDIC, up to $250,000
Federal cap on loan rates
18% APR for federal credit unions
No federal cap for most loans
Federal income tax
Exempt
Taxed
Primary regulator
NCUA or state regulator
OCC, FDIC, Federal Reserve or state
The tax exemption is real, and it is why credit unions can run thinner margins. Federal credit unions are exempt under Internal Revenue Code section 501(c)(1), and state-chartered ones under section 501(c)(14). The trade-off is that credit unions must restrict who can join, which brings us to eligibility.
Who can join: the field of membership
Every credit union has a “field of membership,” a set of rules approved by its regulator that says who is eligible. The Federal Credit Union Act allows three basic types.
Single common bond. One employer, one union, one church, one association. The classic example is a credit union that serves employees of a hospital or a school district.
Multiple common bond. Several unrelated groups under one roof. A credit union might serve employees of 300 different companies plus members of a dozen associations.
Community. Anyone who lives, works, worships or attends school in a defined geographic area, often a county or a metro region. These are the easiest to qualify for if you live in the right place.
Most credit unions also extend eligibility to the family of a member. “Family” is usually defined broadly to include spouses, parents, children, siblings, grandparents, grandchildren and anyone living in the member’s household. If your sister belongs, you likely qualify too.
The association route
Here is the part many people miss. A large share of credit unions include one or more associations in their field of membership, and some of those associations exist mainly so people can join. You pay a one-time membership fee or donation, often $5 to $20, to a nonprofit the credit union partners with, and that makes you eligible. The credit union will tell you on its eligibility page which associations count. Check the fee before you commit; you are paying it on top of the share deposit.
Once a member, always a member
Most federal credit unions adopt a bylaw provision that keeps you eligible even after you leave the employer, move out of the area or drop the association. As long as you keep your share account open with the minimum balance, your credit union membership continues for life. Ask about this before you join if you expect to move.
How to become a member
Joining is a short process, usually online, that takes about 15 minutes.
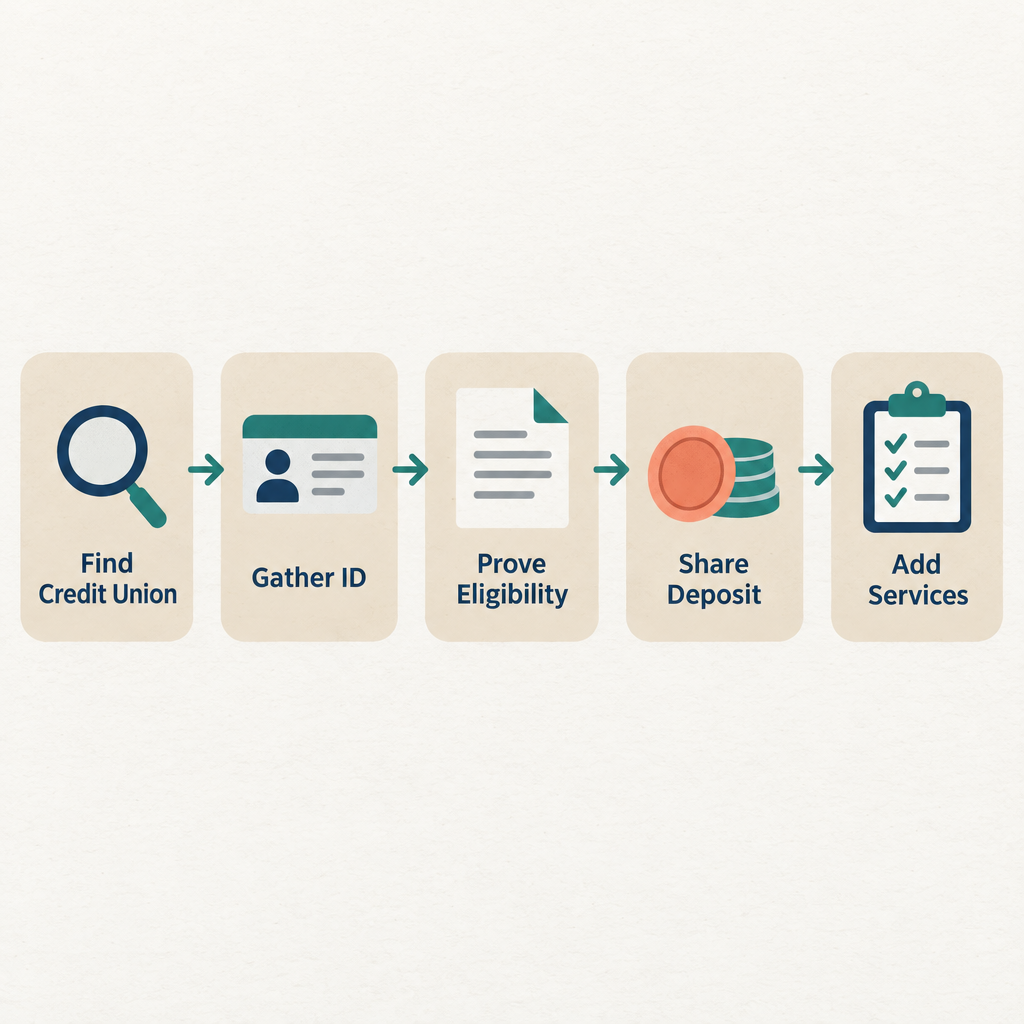
How to join a credit union
Find a credit union whose field of membership you fit, using the NCUA’s Credit Union Locator or the credit union’s own eligibility page.
Gather a government photo ID, your Social Security number or ITIN, and a current address.
Provide proof of eligibility if asked: a pay stub, an address in the service area, a relative’s membership, or an association receipt.
Pay the par value share deposit, typically $5 to $25, into a savings account to open your membership.
Add checking, a card or other services once the share account is open.
Two things to know before step four. First, the share deposit is yours, but it usually has to stay in the account to keep your membership active. Second, many credit unions screen new members through ChexSystems or Early Warning Services, the same consumer reporting agencies banks use. Under the Fair Credit Reporting Act you can request a free copy of your ChexSystems report and dispute errors, which matters if a past overdraft is blocking you. Some credit unions offer a “second chance” checking account for people with a rough ChexSystems history.
What membership costs
The honest answer: usually almost nothing. The share deposit is refundable when you close the account. Monthly fees on basic checking are often zero, and when they exist they tend to be lower than at large banks. Where credit unions really separate from other lenders is on loan pricing, because of two federal caps.
The Federal Credit Union Act sets a 15% ceiling on loan rates but lets the NCUA board raise it temporarily. The board has held the ceiling at 18% APR since 1987, renewing it in 18-month blocks. That cap applies to credit cards, personal loans and nearly every other loan a federal credit union makes. State-chartered credit unions follow their own state’s usury laws instead, which are often similar or stricter.
The second cap covers Payday Alternative Loans, or PALs, which the NCUA created so members have a cheaper substitute for a payday loan. Under 12 CFR 701.21(c)(7), a PAL I is $200 to $1,000 with a one to six month term, and a PAL II is up to $2,000 with a one to twelve month term. Both carry a maximum APR of 28% and an application fee of no more than $20. PAL I requires one month of membership first; PAL II does not.
A worked example: PAL vs payday loan
Product
Amount
Fee or APR
Term
Total repaid
Credit union PAL
$500
28% APR plus $20 fee
6 monthly payments
About $562
Storefront payday loan
$500
$15 per $100 borrowed (about 391% APR)
14 days
$575
Credit union personal loan
$1,000
18% APR
12 monthly payments
About $1,100
Here is the math in plain words. At 28% APR, the monthly rate is 28 divided by 12, or about 2.33%. A $500 loan paid over six months works out to roughly $90 a month, so you pay around $42 in interest, plus the $20 fee, for a total near $562. The payday loan costs $75 for two weeks, which sounds smaller, but a $75 charge on $500 for 14 days is a 391% annual rate. If you roll it over twice, you have paid $225 in fees and still owe the original $500.
A credit union credit card at the 18% cap compares the same way. If you want to see how that rate turns into a monthly charge, “credit card apr explained” walks through the daily interest math.
Before you borrow
A credit union loan is still a loan. Missing payments damages your credit report, and the credit union can take money from your share accounts to cover a defaulted balance, a right it reserves in most loan agreements. Borrow only what you can repay on schedule.
Credit unions for military members
Service members, veterans and their families have some of the largest fields of membership in the country open to them. Navy Federal Credit Union, the biggest credit union in the US by assets, serves active duty, reserve and retired members of every branch, Department of Defense and Coast Guard civilians, veterans, and their family and household members. Pentagon Federal Credit Union opens its doors to anyone who makes a small savings deposit, so military affiliation is not required. Service Credit Union, Andrews Federal Credit Union and Security Service Federal Credit Union also serve military communities and typically have branches on or near bases.
A note on USAA: it is a bank and insurer, not a credit union, though it serves a similar population.
Two federal laws add protection for military borrowers at any lender, credit unions included. The Military Lending Act caps the Military Annual Percentage Rate at 36% on most consumer credit extended to active duty service members and their dependents, and it bans mandatory arbitration on those loans. The Servicemembers Civil Relief Act caps interest at 6% on debts you took on before entering active duty, once you give the lender written notice and a copy of your orders.
Cheaper options first
Ask your credit union about a PAL before any payday or online installment loan.
Many employers and some credit unions offer no-fee small advances or hardship plans.
Nonprofit credit counseling agencies can set up a debt management plan at little or no cost.
State availability and insurance
Credit unions exist in every state and the District of Columbia, but the specific one you want may not serve your area. Community charters are geographic, so a credit union in Ohio generally cannot take a member in Texas unless that person qualifies through an employer, an association or a family tie.
Insurance is the other state wrinkle. Every federal credit union is insured by the National Credit Union Share Insurance Fund, which covers up to $250,000 per member, per credit union, per ownership category, backed by the full faith and credit of the United States. Most state-chartered credit unions carry the same NCUA insurance. A small number of state credit unions in a handful of states are privately insured instead, with no federal backing. Those credit unions must disclose this at the branch and on their website under federal rules. Before you deposit, confirm NCUA coverage using the NCUA’s Research a Credit Union tool.
Your rights as a credit union member
Credit unions follow nearly the same consumer protection rules as banks.
Truth in Lending Act and Regulation Z (12 CFR 1026) require clear disclosure of the APR, finance charge and payment schedule on every loan and credit card.
Truth in Savings Act, applied to credit unions through NCUA regulation 12 CFR Part 707, requires disclosure of dividend rates, fees and minimum balances on share accounts.
Electronic Fund Transfer Act and Regulation E limit your liability for unauthorized debit card and electronic transactions when you report them promptly, and give you dispute rights.
Equal Credit Opportunity Act bars the credit union from denying you a loan based on race, sex, religion, national origin, age, marital status or receipt of public assistance.
Fair Credit Reporting Act governs how the credit union reports your accounts to credit bureaus and gives you the right to dispute errors.
Fair Debt Collection Practices Act does not usually cover the credit union collecting its own loans, but it does apply to any third-party debt collector the credit union hires.
You also hold governance rights no bank customer has: one vote per member for the board of directors, the right to attend the annual meeting, and the right to nominate candidates.
Where to complain
For a federal credit union with under $10 billion in assets, file with the NCUA Consumer Assistance Center. Credit unions above $10 billion are supervised by the Consumer Financial Protection Bureau, which takes complaints about any credit union through its complaint portal. State-chartered credit unions answer first to the state regulator that chartered them. Suspected fraud goes to the FTC at ReportFraud and, for online scams, the FBI’s IC3.
FAQ
Can anyone join a credit union?
Almost everyone can join some credit union, but not every credit union. Between community charters, family eligibility and association-based routes, most people can find at least one they qualify for. The restriction is on which credit union, never on whether you qualify for any.
Is my money safe in a credit union?
Yes, if the credit union is federally insured. The NCUSIF protects up to $250,000 per member per ownership category, the same level as FDIC coverage at a bank. Verify coverage on the NCUA website before you deposit.
Does joining a credit union affect my credit score?
Opening a share account does not involve a credit inquiry at most credit unions. Applying for a loan or credit card triggers a hard inquiry just as it would anywhere else.
What does credit union membership cost per year?
Usually nothing beyond the one-time share deposit, which stays in your account and is returned if you close it. Some accounts carry monthly fees if you fall below a minimum balance, so read the fee schedule the credit union must give you under Truth in Savings rules.
Can I keep my membership if I change jobs?
At most credit unions, yes. The common “once a member, always a member” bylaw keeps your membership active as long as your share account stays open with the minimum balance.
Credit card APR, short for annual percentage rate, is the yearly interest rate your card issuer charges on any balance you do not pay off by the due date. Issuers apply it as a tiny daily rate, so a 24.99% APR works out to about 0.068% of your balance every day, and that adds up to roughly $20 a month on a $1,000 balance. Pay the full statement balance on time and the purchase APR never touches you at all.
What APR measuresyearly interest cost
How it is chargeddaily, on unpaid balance
Typical purchase APRhigh teens to low 30s
Federal averageabove 20% (Fed G.19)
Avoid it bypaying in full each month
As ofOctober 2026
What credit card APR actually means
APR is the number lenders must show you under the Truth in Lending Act and its implementing rule, Regulation Z (12 CFR 1026). It is written as a yearly figure so you can compare cards, but your issuer never charges it once a year.
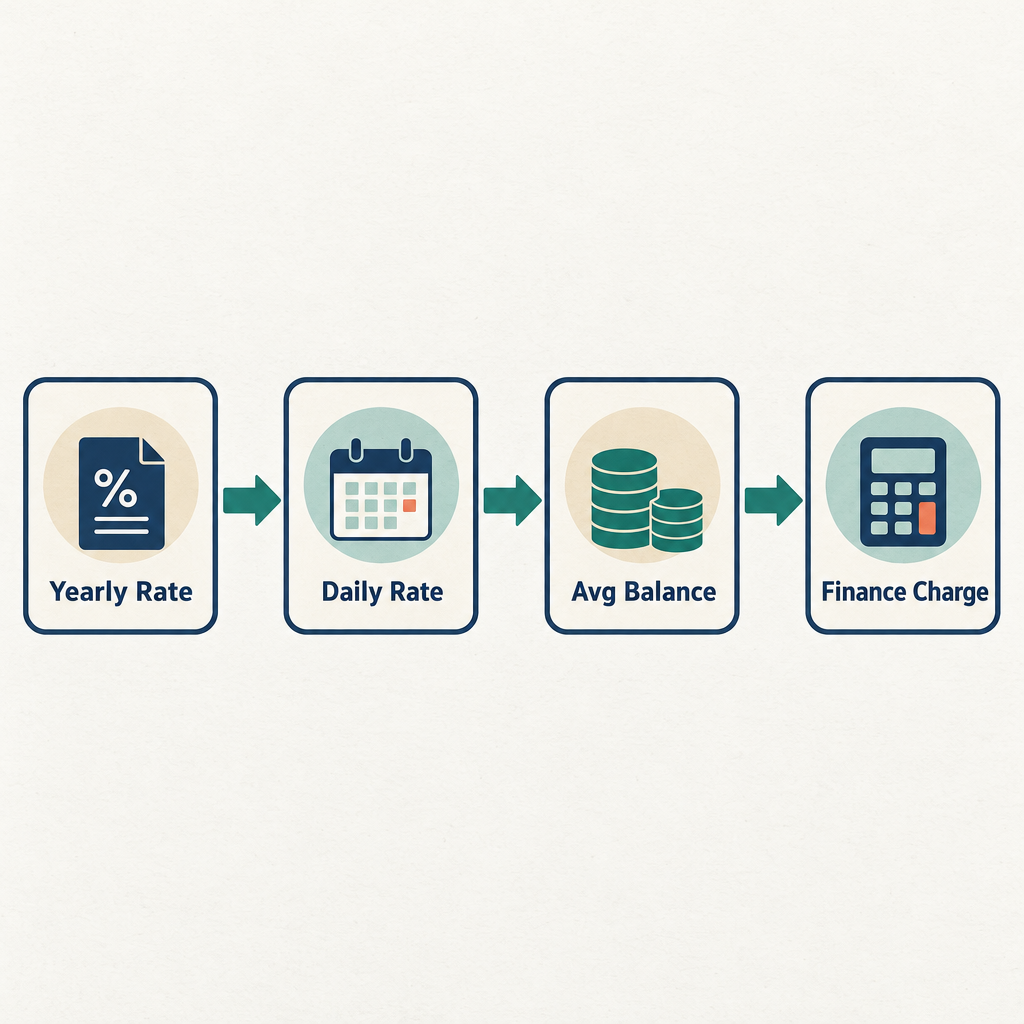
Instead, the issuer divides the APR by 365 to get a daily periodic rate. That daily rate is applied to your balance every day of the billing cycle, and the results are added up on your statement as the finance charge.
For a credit card, APR and the interest rate are the same thing. That is different from a mortgage or a car loan, where the APR includes closing costs and fees on top of the interest rate. A card’s annual fee, late fee or foreign transaction fee is charged separately and is not folded into the APR.
Most card APRs are also variable. Your rate is built from an index, almost always the U.S. prime rate, plus a fixed margin the issuer sets based on your credit. The prime rate moves with the Federal Reserve’s target rate, so when the Fed raises or cuts rates, your card APR follows within a billing cycle or two.
The different APRs on one card
A single card usually carries four or five separate rates. The cardholder agreement lists them in a federally required table often called the Schumer box, and each one applies to a different kind of balance.
Type of APR
What it applies to
What makes it different
Purchase APR
Everyday spending
Only charged if you carry a balance past the grace period
Balance transfer APR
Debt moved from another card
Often a 0% intro rate, plus a 3% to 5% transfer fee
Cash advance APR
ATM withdrawals, cash-like transactions
Higher rate, no grace period, plus a fee
Penalty APR
Your whole balance after a serious misstep
Can top 29.99%; triggered by payments 60+ days late
Introductory or promotional APR
New purchases or transfers for a set window
Expires on a fixed date, then the regular rate applies
Under Regulation Z (12 CFR 1026.53), when you pay more than the minimum, the issuer must apply the extra to the balance with the highest APR first. That rule matters if you have a cash advance sitting at 29.99% next to purchases at 0%.
How the grace period lets you skip interest entirely
Your statement closes, then you have a window before the payment is due. If you paid the previous statement in full, new purchases made during that cycle carry no interest as long as you also pay this statement in full by the due date. That window is the grace period.
Federal law requires issuers to deliver your statement at least 21 days before the due date (12 CFR 1026.5(b)(2)(ii)), so the grace period on purchases is typically 21 to 25 days.
Two things kill the grace period. Carry even a small balance into the next cycle and interest starts on new purchases from the day you buy. Take a cash advance and interest starts the same day, grace period or not. Once you lose it, most issuers require two consecutive statements paid in full before it comes back.
How to calculate credit card interest using APR
The math behind your finance charge is simple once you see it laid out. Issuers use the average daily balance method, which means every day’s balance counts, not just the number on the statement.
How to estimate a month of interest
Divide your APR by 365 to get the daily periodic rate (24.99% ÷ 365 = 0.0685%).
Add up your balance at the end of each day in the cycle and divide by the number of days to get the average daily balance.
Multiply the average daily balance by the daily rate, then by the days in the cycle.
Compare the result with the “interest charged” line on your statement to check the issuer’s figure.
Using those steps, a $1,000 average daily balance at 24.99% APR over a 30-day cycle costs about $20.50. Many issuers compound daily, meaning each day’s interest is added to the balance before the next day’s charge, which nudges that figure slightly higher.
What carrying a balance really costs
The headline APR looks abstract. The total you repay does not. Here is what happens to a $1,000 purchase balance at 24.99% depending on how you pay it down, with a cash advance added for comparison.
Scenario
Amount
APR and fees
Time to pay off
Total repaid
Pay in full by due date
$1,000
24.99%, grace period applies
1 month
$1,000
Pay $100 a month
$1,000
24.99%
About 12 months
About $1,120
Pay $30 a month (near minimum)
$1,000
24.99%
About 58 months
About $1,725
Cash advance, paid over 12 months
$1,000
29.99% plus 5% fee ($50)
12 months
About $1,220
The $30-a-month row is the one that traps people. Nearly $725 in interest on a $1,000 balance, spread over almost five years, is why the CARD Act of 2009 requires every statement to show how long it will take to clear your balance making only minimum payments (12 CFR 1026.7(b)(12)). Look for that box on your next statement.
The scale is enormous nationally. The CFPB’s 2023 Consumer Credit Card Market Report found cardholders paid more than $100 billion in interest in 2022, and the Federal Reserve’s G.19 consumer credit release has shown the average rate on accounts assessed interest sitting above 20% since 2023.
Before you carry a balance
Once you carry a balance, you lose the grace period and pay interest on every new purchase from the day you make it. Minimum payments at a 25% APR can stretch a modest balance into years of repayment and nearly double the original cost.
What counts as a good APR
There is no single good number, because your rate is priced on your credit profile. Issuer disclosures for 2025 and 2026 show a consistent pattern: rewards cards for strong credit typically start in the high teens, mainstream cards for fair credit land in the mid to high 20s, and store cards and cards for rebuilding credit often sit at or above 30%.
A useful benchmark is the federal credit union ceiling. The Federal Credit Union Act caps loan rates at federal credit unions at 15% unless the NCUA board raises the limit, and the board has set that ceiling at 18% for many years. A card rate under 18% is genuinely competitive. Anything above the Fed’s reported average deserves scrutiny.
Your APR only matters if you carry a balance. If you pay in full every month, a 29.99% card and a 15.99% card cost the same amount of interest: zero. In that case, fees and rewards are the only numbers worth comparing.
How to lower the APR you already have
Issuers do cut rates on request, especially for cardholders with on-time payment histories. Call the number on the back of the card, cite your history and any lower offers you have received, and ask for a reduction. A no costs you nothing.
If you are struggling, ask about a hardship program. Most large issuers run them, and they can temporarily cut the APR to single digits or zero in exchange for a fixed payment plan. Nonprofit credit counseling agencies affiliated with the National Foundation for Credit Counseling can negotiate similar terms through a debt management plan.
Cheaper options first
Pay the statement balance in full each month and the purchase APR costs you nothing.
A credit union card or personal loan often runs under 18%, well below the national card average.
Issuer hardship programs and nonprofit credit counseling can cut rates without new borrowing.
A 0% balance transfer can help if you can clear the debt before the promotion ends, but the 3% to 5% transfer fee is real money and the rate jumps on a fixed date. A cash advance is almost never the answer. For true emergencies, a credit union payday alternative loan, capped by the NCUA at 28% APR with an application fee of no more than $20, costs far less than a cash advance and vastly less than a “payday loan“. Compare any “loans emergency” option against your existing card’s purchase APR before borrowing new money.
State rules and who gets capped rates
Credit card APRs rarely fall under “usury laws” in your own state. Since the Supreme Court’s 1978 decision in Marquette National Bank v. First of Omaha, a national bank can charge the rate allowed by the state where it is chartered to customers anywhere in the country, under 12 U.S.C. § 85. That is why so many issuers sit in Delaware, South Dakota and Utah, states with no rate cap on cards.
Two federal laws do cap rates for specific groups. The Military Lending Act limits the military annual percentage rate on cards for active-duty service members and their dependents to 36%, including most fees. The Servicemembers Civil Relief Act caps interest at 6% on debts you took on before entering active duty, as long as you ask the issuer and provide orders.
Your rights on rate changes
The CARD Act, enforced through Regulation Z, gives you specific protections against surprise rate hikes.
The issuer cannot raise the APR on your existing balance during the first year after opening the account, except when a promotional rate ends, the index on a variable rate rises, or you fall 60 days behind (12 CFR 1026.55).
Any rate increase on new purchases requires 45 days’ written notice (12 CFR 1026.9(c)(2)), and you have the right to reject the increase and pay off your existing balance at the old rate.
A penalty APR can only hit your existing balance if a payment is at least 60 days late, and the issuer must restore the original rate after six consecutive on-time payments (12 CFR 1026.55(b)(4)).
Issuers that raised your rate for any reason must review the account at least every six months and reduce the rate if the reason no longer applies (12 CFR 1026.59).
Double-cycle billing, which charged interest on balances you had already paid, is banned (12 CFR 1026.54).
If an issuer breaks these rules, file a complaint through the CFPB’s online complaint portal. National banks also answer to the Office of the Comptroller of the Currency, and federal credit unions to the NCUA. If an unpaid balance is sold or sent to a “debt collector“, the Fair Debt Collection Practices Act controls what that collector can say and do, and the collector cannot add interest your original agreement did not allow.
FAQ
Is APR charged monthly or yearly on a credit card?
Neither, strictly. The APR is divided by 365 and charged daily on your unpaid balance, then totaled on your monthly statement as the finance charge.
What is the difference between APR and interest rate on a credit card?
On a credit card they are the same number. APR only differs from the interest rate on products like mortgages, where upfront fees are rolled into the APR.
Does APR matter if I pay my balance in full?
No. Paying the full statement balance by the due date keeps the grace period active, and the purchase APR never applies. Cash advances are the exception, since they accrue interest from day one.
Why did my credit card APR go up without my doing anything?
Most card APRs are variable and tied to the prime rate. When the Federal Reserve raises rates, your APR rises automatically, and issuers do not have to give 45 days’ notice for index-driven changes.
What is a penalty APR and how do I get rid of it?
A penalty APR, often around 29.99% or higher, can apply after a payment is 60 or more days late. Under Regulation Z the issuer must restore your original rate after six straight on-time payments.
Can a credit card charge more than my state’s usury limit?
Usually yes. Federal law lets a national bank export the rate rules of its home state, so a card issued from Delaware or South Dakota is not bound by the cap where you live.
An emergency loan is any fast borrowing you use to cover a surprise bill, usually a personal loan, a payday loan, a cash advance app or a credit card cash advance. The cheapest versions cost under 30% APR and the most expensive top 400% APR, so the product you pick matters more than how fast the money arrives. This guide explains how emergency loans work, what each type really costs, which states restrict them and what your legal rights are when you borrow.
Typical amounts$100 to $5,000
APR range6% to over 400%
Fastest fundingsame day to next business day
Cheapest regulated optioncredit union PAL, 28% APR cap
Military borrowers36% MAPR cap
Main sourcesCFPB, NCUA, Federal Reserve
What emergency loans are
“Emergency loan” is a marketing label, not a legal category. No federal law defines one. When a lender advertises emergency loans, it is selling one of the ordinary products below, often with same-day or next-day funding added as the hook.
The Federal Reserve’s Survey of Household Economics and Decisionmaking has found for several years running that roughly 37% of US adults could not cover a $400 surprise expense with cash or its equivalent. That gap is the market these lenders serve. Some serve it fairly. Others price the loan at a level that creates the next emergency.
The main types you will see:
Unsecured personal loans from banks, credit unions and online lenders, usually $1,000 to $50,000, repaid in fixed monthly payments over one to seven years.
Payday loans, typically $100 to $500, due in full on your next payday with a flat fee.
Cash advance apps that front a portion of your paycheck, often $20 to $500, and pull it back on payday.
Credit card cash advances, which draw cash against your card’s limit at a higher rate than purchases.
Auto title loans, secured by your car, usually for 30 days.
Payday alternative loans (PALs), a regulated small loan offered only by federal credit unions.
A “payday loan” and a personal loan can both be advertised as emergency loans, yet one costs around 400% APR and the other might cost 12%. Reading the actual disclosure, not the headline, is the whole game.
How emergency loans work, step by step
Most emergency lenders follow the same path, and knowing it helps you spot where the costs hide.
Application. Online lenders ask for identity, income, a bank account and a Social Security number. Many run a soft credit inquiry first, which does not affect your score, then a hard inquiry only if you accept an offer. “No credit check” offers usually mean the lender checks a different database (bank transaction data or a subprime bureau such as Clarity) and prices the loan high to cover the risk.
Underwriting. Personal loan lenders look at your credit score, debt-to-income ratio and income. Payday lenders mostly want proof of a paycheck and an active checking account. Cash advance apps read your bank history to estimate your next deposit.
Disclosure. Under the Truth in Lending Act and Regulation Z (12 CFR 1026), any lender offering closed-end consumer credit must give you the APR, the finance charge, the amount financed and the total of payments before you sign. If a lender will not show you the APR, that alone is a reason to walk away.
Funding. Direct deposit by ACH takes one business day for most lenders. Same-day funding usually means an instant debit card push, and some lenders or apps charge an extra fee for it.
Repayment. Personal loans are repaid monthly. Payday loans and app advances are repaid in a lump sum from your checking account on payday. That lump-sum structure is why the CFPB found most payday borrowers end up re-borrowing: the full amount plus fee leaves a hole in the next paycheck.
What an emergency loan really costs
The table shows what common products cost on a realistic borrowing amount. APR converts every fee into an annual rate so you can compare a two-week loan against a 12-month loan on equal terms. The math in plain words: divide the fee by the amount borrowed, divide by the number of days you have the money, and multiply by 365.
Product
Amount
Cost
Term
Total repaid
Approximate APR
Credit union PAL I
$500
28% APR plus $20 application fee
6 months
About $562
28% plus fee
Credit card cash advance
$500
5% fee ($25) plus 29.99% APR, no grace period
30 days
About $538
Roughly 90% on a 30-day payoff
Online personal loan, fair credit
$1,000
36% APR
12 months
About $1,206
36%
Cash advance app
$100
$4.99 express fee, no tip
7 days
$104.99
About 260%
Auto title loan
$500
25% monthly finance charge
30 days
$625
300%
Payday loan
$500
$15 per $100
14 days
$575
391%
The payday figure is the CFPB’s own standard example. The title loan figure matches the typical 25% monthly charge the CFPB documented in its title lending research, where it also found about one in five title borrowers lost their vehicle to repossession.
Cash advance apps look cheap in dollars, which is exactly the problem. A $4.99 express fee on a $100 advance for one week works out to roughly 260% APR. The CFPB’s 2024 analysis of earned wage access products found a typical advance cost over 100% APR once express fees and voluntary “tips” were counted. Apps that let you wait two or three business days for free are much cheaper, so the fee is really a charge for speed.
For personal loans, the Federal Reserve’s G.19 consumer credit release has put the average 24-month personal loan rate at banks in the low double digits during 2025, near 12%. That rate goes to borrowers with good credit. Borrowers with scores below about 640 commonly see 25% to 36%, and most mainstream online lenders stop at 36%.
Before you borrow
The biggest risk is not the first fee but the second loan. CFPB research found about four in five payday loans are rolled over or followed by a new loan within 14 days, which turns a $75 fee into hundreds of dollars over a year.
Who an emergency loan can make sense for
A regulated emergency loan can be a reasonable choice when all of these are true:
The expense is unavoidable and has a real deadline, such as a car repair you need to get to work or a utility shutoff notice.
You have a specific plan to repay it from income within the term, not from another loan.
The APR is 36% or lower, which is the cap the Military Lending Act sets for service members and the benchmark most consumer advocates use.
You have already checked the cheaper options below and they are not available in time.
It rarely makes sense to borrow at 300% or more. The CFPB’s data shows that borrowers at those rates typically spend more on fees over a year than they originally borrowed.
Cheaper options first
Before any loan over 36% APR, run through these. Several are free, and most can be arranged in a day or two.
Cheaper options first
A federal credit union PAL is capped at 28% APR and takes a few days to set up.
Hospital charity care, utility hardship plans and dialing 211 can erase the bill instead of financing it.
A no-fee paycheck advance from your employer or an app’s free standard-speed option costs nothing.
1. Credit union payday alternative loans. Under NCUA rules at 12 CFR 701.21(c)(7), a PAL I is $200 to $1,000 over one to six months, with an APR capped at 28% and an application fee of no more than $20. A PAL II goes up to $2,000 over up to 12 months with no minimum membership period. You need to join the credit union, which often requires living or working in its area or a small donation to a partner association.
2. Ask the biller for a plan. Utilities in most states must offer deferred payment arrangements and cannot disconnect during certain weather conditions. Nonprofit hospitals are required under Internal Revenue Code section 501(r) to have a written financial assistance policy, and many write off bills entirely for households under 200% to 400% of the federal poverty level. Ask for the charity care application before paying anything.
3. Local and federal assistance. Dialing 211 connects you to the United Way’s directory of local emergency help for rent, utilities and food. The Low Income Home Energy Assistance Program (LIHEAP) covers heating and cooling bills. Catholic Charities, the Salvation Army and St. Vincent de Paul run emergency bill funds in most counties. None of this has to be repaid.
4. Employer or free app advance. Many employers now offer earned wage access through payroll at no cost to you. If you use a cash advance app, the standard-speed transfer is usually free and arrives in one to three business days.
5. A 0% credit card or your existing card’s purchase rate. Charging a car repair to a card at 24% APR and paying it off in two months costs far less than any payday product. Avoid the cash advance feature, which carries a fee and starts charging interest immediately.
6. Retirement account emergency withdrawal. Under the SECURE 2.0 Act, participants in employer plans such as a 401(k), 403(b) or governmental 457(b) that have adopted the provision can take up to $1,000 per year for a personal emergency without the 10% early withdrawal penalty, with the option to repay it within three years. The withdrawal is still taxed as ordinary income, and the provision is generally not available for IRAs. A 401(k) loan, where your plan allows one, lets you borrow up to 50% of your vested balance or $50,000, whichever is less, and the interest goes back into your own account.
Where emergency loans are restricted by state
Availability depends on where you live, and no lender can legally offer every product everywhere.
Payday lending is banned or capped at or near 36% APR in roughly 20 states and the District of Columbia, including New York, New Jersey, Pennsylvania, Massachusetts, Connecticut, Maryland, North Carolina, Georgia, Arizona, Arkansas, Colorado, Illinois, New Mexico, Nebraska, Montana, South Dakota and Vermont. In those states a lender advertising 400% APR loans is either a tribal lender or operating illegally, and state “usury laws” generally make such loans void or uncollectible.
Auto title loans are legal in only about half of states. Personal installment loans are available everywhere, but the maximum rate a licensed lender can charge varies widely by state and loan size. Cash advance apps operate nationally, though several states, including Connecticut and Maryland, have brought them under their small loan laws.
If you are on active duty or a dependent, the Military Lending Act caps the Military Annual Percentage Rate at 36% on most consumer credit no matter which state you are in, and it bans mandatory arbitration clauses in those contracts.
How to check a lender before you sign
How to check a lender
Search the company on NMLS Consumer Access to confirm it holds a license in your state.
Confirm the license with your state’s banking or financial regulator lookup.
Read the Truth in Lending disclosure and find the APR and total of payments.
Search the CFPB complaint database for the lender’s name.
Refuse any lender that asks for an upfront fee, gift cards or crypto to “release” the loan.
That last point is the single most common emergency loan scam the FTC reports. A legitimate lender never asks you to pay before funding. Scammers also copy real lenders’ names, so match the license number, not just the brand.
Your rights as a borrower
Several federal laws apply to emergency loans, and lenders cannot contract around them.
Truth in Lending Act and Regulation Z. You are entitled to a written APR and finance charge before you are bound. For loans with a prepayment penalty or balloon payment, that must be disclosed too.
Equal Credit Opportunity Act. A lender cannot deny or price a loan based on race, sex, marital status, age, national origin, religion or because your income comes from public assistance. If you are denied, you must receive an adverse action notice giving the reason or telling you how to get it.
Fair Credit Reporting Act. You can pull your reports from all three bureaus free every week at AnnualCreditReport.com, and you can dispute errors, which the bureau must investigate within 30 days. If a lender denies you based on your report, the notice must name the bureau.
Electronic Fund Transfer Act and Regulation E. A lender cannot require you to repay by automatic debit as a condition of credit (15 U.S.C. 1693k). You can revoke an ACH authorization by notifying the lender and your bank, and your bank must honor a stop payment on a recurring debit if you give it three business days’ notice.
Fair Debt Collection Practices Act. If the loan goes to a third-party “debt collector,” that collector cannot call before 8 a.m. or after 9 p.m., contact you at work after you say not to, threaten arrest or lie about what you owe. Debt collectors also cannot collect on a loan that was void under your state’s law.
Military Lending Act and Servicemembers Civil Relief Act. Covered borrowers get the 36% MAPR cap, and the SCRA lets active-duty members reduce pre-service debts to 6% interest on request.
To complain, use the CFPB complaint portal, which forwards your complaint to the company and tracks its response. Report fraud at FTC ReportFraud or, for online scams, the FBI’s Internet Crime Complaint Center (IC3).
FAQ
How fast can I get an emergency loan?
Cash advance apps and some online lenders can fund within minutes to a debit card, usually for an express fee. Standard ACH funding takes one business day. Credit union PALs can take a few days if you must join first.
Can I get an emergency loan with bad credit?
Yes, but the price rises sharply below a 640 score. Licensed personal loan lenders generally cap out at 36% APR. Payday and title lenders accept almost anyone and charge 300% to 400% APR. A credit union PAL is the cheapest widely available option for thin or damaged credit.
Do emergency loans affect my credit score?
Personal loans from banks, credit unions and most online lenders report to the bureaus, so on-time payments help and missed ones hurt. Most payday lenders and cash advance apps do not report at all, which means they do not build credit either. Any hard inquiry can lower a score by a few points for up to a year.
What is the difference between an emergency loan and a payday loan?
A payday loan is one kind of emergency loan, repaid in a single lump sum on your next payday at a flat fee that works out to about 391% APR. Other emergency loans, such as personal loans and PALs, are repaid in monthly installments at far lower rates.
Are there emergency loans that are actually free?
Employer paycheck advances, the standard-speed option on most cash advance apps and the SECURE 2.0 $1,000 retirement emergency withdrawal carry no fee. Charity care, 211 referrals and LIHEAP are grants, not loans, and never need repayment.
Usury is lending money at an interest rate higher than the law allows, and a loan that crosses that line is called usurious. The catch is that there is no single American usury rate: each state sets its own caps, federal banking law lets banks ignore most of them, and a long list of exemptions decides whether a lender’s price is legal or a crime. We walk through what the caps are, who they actually bind, and what a borrower can do with an overpriced loan.
Federal usury capnone for most loans
Military cap36% MAPR
Typical state civil cap6% to 18%
Typical payday APRaround 391%
State payday caps near 36%about 20 states plus DC
Federal credit union cap18% APR
What usury means today
In plain words, usury is charging more interest than the maximum rate a state’s legislature has written into law. The word once meant any interest at all, and the Hebrew Bible, the medieval Catholic Church and Islamic law all banned lending at interest in various forms. By the 1700s English law and most American colonies had settled on a different idea: interest is fine, but there is a ceiling. The English cap was 5% for much of the century, and Jeremy Bentham’s 1787 “Defence of Usury” argued the ceiling itself was the problem.
That older debate still shapes the modern rules. Every state has some statute on the books defining a legal rate of interest, a maximum contract rate, or both. Most also define a higher criminal usury rate that turns the loan from a civil problem into a misdemeanor or felony.
Three terms come up constantly:
Legal rate is the interest a court applies when a contract says nothing about interest, often 6% to 10%.
Maximum contract rate is the highest rate two parties can agree to in writing. This is the civil usury line.
Criminal usury rate is the point at which the lender can be prosecuted, commonly 20% to 25% in states that have one.
A loan is usurious when its rate exceeds the contract rate that applies to that lender and that type of loan. The second half of that sentence is where most people get tripped up, because the exemptions are bigger than the rule.
Why there is no federal usury cap
Congress has never passed a general interest rate ceiling for consumer loans. Bills to set a national 36% cap have been introduced in nearly every session since 2019, and none has passed as of our latest check. What federal law does instead is regulate disclosure, protect specific groups, and, importantly, let banks export their home-state rate across state lines.
Federal law
What it does about interest
Who it covers
Truth in Lending Act, Regulation Z (12 CFR 1026)
Requires the APR and finance charge to be disclosed; sets no cap
Most consumer credit
Military Lending Act (10 U.S.C. § 987, 32 CFR 232)
Caps the Military Annual Percentage Rate at 36%, fees included
Active-duty servicemembers and dependents
Servicemembers Civil Relief Act
Caps interest on debts taken on before service at 6% while on active duty
Servicemembers who request it
National Bank Act, 12 U.S.C. § 85
Lets national banks charge the rate allowed in the bank’s home state to borrowers anywhere
National banks
12 U.S.C. § 1831d (DIDMCA Section 521, 1980)
Extends the same rate exportation to state-chartered FDIC-insured banks
State banks
Federal Credit Union Act, 12 U.S.C. § 1757(5)
Caps federal credit union loans at 15%, which the NCUA board may raise; the ceiling has been 18% since 1987
Federal credit unions
The rate exportation rule is the reason your credit card can carry a 29% APR in a state whose usury statute says 12%. In Marquette National Bank v. First of Omaha Service Corp. (1978), the Supreme Court read the National Bank Act to mean a bank “located” in Nebraska could charge Nebraska’s rate to a Minnesota cardholder. South Dakota and Delaware then repealed their caps for banks in 1980 and 1981, Citibank moved its card operation to Sioux Falls, and the modern credit card industry followed. The Federal Reserve’s G.19 release has shown average APRs on card accounts assessed interest above 20% throughout 2024 and 2025, a figure that would be criminal usury in New York if a non-bank charged it.
Two more federal rulings matter. Smiley v. Citibank (1996) held that late fees, over-limit fees and similar charges count as “interest” a bank can export. And in 2020 the Office of the Comptroller of the Currency and the FDIC each adopted “valid when made” rules (12 CFR 7.4001(e) and 12 CFR 331) saying a loan that was legal when a bank made it stays legal at the same rate after the bank sells it to a non-bank. That rule was a direct response to Madden v. Midland Funding (2d Cir. 2015), where a debt buyer lost the bank’s rate protection after buying a charged-off account. Both federal rules survived court challenges from state attorneys general.
States were allowed to opt out of Section 521 when it passed. Iowa and Puerto Rico did so in 1980 and kept their opt-outs. Colorado passed a new opt-out in 2023 aimed at out-of-state bank loans above its own caps, and that law has been tied up in federal litigation since; the practical effect for Colorado borrowers depends on how the appeals end.
How state usury laws set the cap
State legislatures write usury rules in three layers: a general cap that applies to anyone not otherwise exempt, special statutes for licensed lenders that override the general cap, and criminal penalties above a higher line. The general cap usually binds only private lenders, family loans, seller financing and unlicensed companies. Licensed consumer lenders, banks, credit unions, pawnbrokers and payday lenders almost always operate under their own statute with its own, higher, ceiling.
The table below shows the general civil and criminal lines in a handful of states as they stand in the statutes. We include it to illustrate the spread, not as a lookup for any specific loan; the licensed-lender exemptions in each state usually matter more.
State
General contract cap
Criminal usury line
Key exemptions and notes
New York
16% (General Obligations Law § 5-501)
25% (Penal Law § 190.40)
Loans over $250,000 exempt from civil usury; over $2.5 million exempt from criminal; usurious loans are void
California
10% for personal, family or household loans (Constitution Art. XV § 1)
None as a separate rate; usury is civil
Banks, credit unions and California Financing Law licensees exempt; payday loans capped by a separate statute
Texas
10% default (Finance Code § 302.002), optional ceilings up to 18% or more under Chapter 303
Contract rate above twice the legal cap is criminal
Credit access businesses arrange payday and title loans at fees far above the cap
Florida
18% (Fla. Stat. § 687.02)
25% misdemeanor, 45% felony (§ 687.071)
Loans over $500,000 may carry up to 25%
Georgia
7% if nothing is written; up to 16% by contract on loans under $3,000 (O.C.G.A. § 7-4-2)
Payday lending itself is a crime (§ 16-17-1)
Any agreed rate on loans of $3,000 or more
Illinois
9% general rate (815 ILCS 205/4)
None separate
Predatory Loan Prevention Act (2021) caps consumer loans at 36% APR for all lenders not exempt under federal law
Massachusetts
None stated; 20% is the trigger
20% unless lender registers with the Attorney General (G.L. c. 271 § 49)
Registration makes higher rates legal, which is why the cap bites mostly on unregistered lenders
Delaware, Utah, South Dakota
No cap for licensed lenders or banks
Not applicable
Chosen as home states by card issuers and installment lenders
A few patterns stand out. New York’s rule that a usurious loan is void, with the borrower owing neither interest nor principal, is the harshest in the country and explains why so many fintech contracts avoid New York governing law. California’s constitutional cap sounds strict until you read the exemption list, which covers almost every company that lends for a living. Texas has a strict-looking statute and some of the most expensive small loans in the country, because the credit access business model treats the lender’s fee as a brokerage charge rather than interest.
Payday and small-dollar loans
The sharpest state-by-state divide is on small loans under $1,000. A payday loan in a permissive state typically costs $15 per $100 for two weeks, the example the CFPB itself uses, which works out to a 391% APR. States handle that in one of three ways:
Approach
Examples (as of 2025)
What a $300 loan can cost
Rate cap near 36% APR, payday stores mostly closed
Arizona, Colorado, Illinois, Montana, Nebraska, New Mexico, New York, New Jersey, North Carolina, South Dakota, Georgia, Massachusetts, DC
Under $10 in interest for two weeks
Fee-based cap on payday loans
California ($300 max loan, fee up to 15% of face amount), Florida ($500 max, 10% fee plus $5 verification), Michigan ($600 max, tiered fees)
$45 in California, about $35 in Florida
No meaningful cap on payday fees
Idaho, Nevada, Utah, Wisconsin, Texas via credit access businesses
Whatever the contract says; 400% to 600% APR is common
Voters, not just legislatures, drew many of these lines. South Dakota’s Initiated Measure 21 (2016), Colorado’s Proposition 111 (2018) and Nebraska’s Initiative 428 (2020) each imposed a 36% cap by ballot with more than 70% support. Illinois’s 2021 law and New Mexico’s 2023 law came through the legislature. Surveys by the National Consumer Law Center and the Center for Responsible Lending count roughly 20 states plus the District of Columbia with caps at or near 36% for a typical $500 loan.
A worked cost example: the same $300 under three regimes
Usury law is abstract until you price a loan with it. Here is a $300 loan repaid over 14 days under a permissive payday statute, under a 36% APR cap, and from a federal credit union’s payday alternative loan program, which NCUA rules at 12 CFR 701.21(c)(7) cap at 28% APR plus an application fee of no more than $20.
Loan
Amount
Fee or APR
Term
Total repaid
Payday loan, $15 per $100
$300
$45 fee (391% APR)
14 days
$345.00
Loan under a 36% cap
$300
36% APR, about $4.14 interest
14 days
$304.14
Credit union PAL at 28%
$300
28% APR, about $3.22 interest, plus up to $20 fee
14 days
$303.22 to $323.22
The APR math is simple division. Take the fee, divide by the amount borrowed, divide by the number of days, and multiply by 365. For the payday loan: $45 divided by $300 is 0.15; 0.15 divided by 14 days is 0.0107 per day; times 365 is 3.91, or 391%. Regulation Z requires the lender to print that figure on the loan agreement, which is why a two-week loan with a “15% fee” shows an APR near 400%. The disclosure does not make the rate legal or illegal; only the state’s statute does that.
The credit union example shows a wrinkle. A $20 application fee on a two-week, $300 loan adds the equivalent of about 174 percentage points of APR if you annualize it, which is why NCUA excludes that fee from the 28% calculation and why PALs make more sense for loans of a few months than a few days.
Before you borrow
A loan priced above your state’s cap is not automatically unenforceable, because the lender may be a bank, a licensed lender or a buyer of bank-originated loans with a legal exemption. Assume you will owe what you signed for unless a court or regulator says otherwise, and price the loan by total dollars repaid, not by the monthly fee.
Who the caps do not bind
The list of exemptions explains most of the gap between the statute and the price you are quoted.
Banks and credit unions. Rate exportation lets any FDIC-insured bank charge its home-state rate nationwide, and federal credit unions follow the NCUA ceiling rather than state law. The 18% federal credit union cap has been extended repeatedly; the NCUA board’s most recent extension runs through September 2026.
Licensed lenders. Nearly every state has a consumer finance act, small loan act or installment loan act that sets a separate, higher cap for companies it licenses. California’s Financing Law, for example, caps loans of $2,500 to $9,999 at 36% plus the federal funds rate under a 2019 law, while leaving loans of $10,000 and up with no cap at all.
Commercial and business loans. Usury statutes grew up to protect households, and many states exclude business borrowers outright or set a high floor. New York bars corporations from raising civil usury as a defense (General Obligations Law § 5-521), though they can still assert criminal usury. Florida’s cap rises to 25% above $500,000. Merchant cash advances, which buy a slice of a business’s future receipts, are structured as purchases precisely so that usury law does not reach them; the New York Attorney General and the FTC have both sued cash advance companies on the theory that the “purchase” was really a loan.
Pawn, rent-to-own and retail installment contracts. Each usually has its own statute. Pawnbroker fees of 20% a month are legal in many states under pawn acts even though the same rate would be criminal usury on a loan.
Loans sold by banks to non-banks. Under the 2020 valid-when-made rules, a fintech that buys loans originated by a Utah bank keeps the Utah rate. Whether the bank or the fintech is the “true lender” is the open question in most rent-a-bank lawsuits, and state attorneys general in Colorado, Illinois and elsewhere have won settlements forcing rate reductions where they could show the bank bore none of the risk.
Tribal lenders. Companies owned by federally recognized tribes claim sovereign immunity from state usury laws. Courts have generally held that tribal immunity does not travel with the loan when a non-tribal business runs the operation, and the CFPB and several states have pursued those arrangements.
What happens when a loan is usurious
Remedies vary as widely as the caps, so the same loan can carry very different consequences across a state line.
Forfeiture of interest. The most common civil remedy. The lender collects principal but no interest. Texas and many other states use this baseline.
Multiple damages. Some states award the borrower twice or three times the excess interest. Texas Finance Code § 305.001 allows three times the usurious interest for violations that exceed twice the legal rate.
Voiding the loan. New York treats a civilly usurious loan made by a non-exempt lender as void from the start; the borrower keeps the money and owes nothing. Massachusetts courts can void loans made in violation of the criminal statute.
Criminal prosecution. Florida’s 45% felony line, New York’s 25% criminal line and Georgia’s ban on payday lending each carry potential jail time for the lender, though prosecutions are rare.
Unenforceable collection. Many states say a loan that violates the lending licensing law is void, and that a debt collector cannot lawfully collect it. The CFPB has taken the position that attempting to collect a loan that is void under state law is itself an unfair practice.
Borrowers raise usury in two ways: as a defense when the lender sues, or as an affirmative claim, sometimes as a class action. Courts also look past labels. A “fee,” “points,” “membership charge” or “tip” can be treated as interest if it is really the price of the money. That is the issue regulators have pressed with earned wage access and cash advance apps, where “tips” and “express fees” can push a $100 advance to the equivalent of a 300% APR. The CFPB said in a 2024 interpretive rule that such charges are finance charges under Regulation Z for disclosure purposes, a position the current CFPB has proposed to withdraw, so that corner of the law is unsettled.
Your rights as a borrower
Even where the rate is legal, federal law gives you tools.
Under the Truth in Lending Act and Regulation Z, you are entitled to see the APR and finance charge in writing before you sign a closed-end loan, and in the account-opening disclosures for a credit card. If the APR on the paper does not match what you are being charged, the lender is in violation regardless of usury law, and TILA allows statutory damages.
Under the Military Lending Act, covered borrowers get a 36% all-in cap, no mandatory arbitration, and no requirement to allot pay. A lender that charges more cannot enforce the contract. Lenders check the Defense Manpower Data Center database before lending; you can check your own status there.
Under the CFPB’s payday lending rule, whose payment provisions took effect on March 30, 2025 after the Supreme Court upheld the agency’s funding in May 2024, a payday or vehicle title lender must stop trying to debit your bank account after two consecutive failed attempts unless you give new authorization. That does not cap the rate, but it stops the cascade of overdraft fees that makes a usurious loan more expensive still.
Under the Fair Debt Collection Practices Act, a third-party collector cannot collect interest or fees that the original contract or state law does not allow. Demanding interest above the state cap on a debt the collector bought is one of the most common FDCPA claims.
How to check whether a lender can legally charge its rate
Find the lender’s license on NMLS Consumer Access or your state financial regulator’s license lookup.
Identify which statute the license falls under; the licensing statute, not the general usury law, usually sets the cap.
If the lender is a bank, check the FDIC BankFind database and note its home state, because that state’s rate applies.
Compare the APR on your Regulation Z disclosure with the applicable cap.
If the rate exceeds the cap and no exemption fits, file a complaint with your state attorney general and the CFPB.
Cheaper options and what to do about an overpriced loan
A usury cap does not help much if the only loan you can get is from a lender the cap does not reach. The options below cost less than almost anything priced above 36%.
Cheaper options first
Federal credit union payday alternative loans come in two forms: PAL I runs $200 to $1,000 at no more than 28% APR over one to six months, and PAL II runs up to $2,000 at no more than 28% APR over one to twelve months.
Employer pay advances and nonprofit emergency assistance usually carry no interest at all.
Nonprofit credit counseling agencies and creditor hardship plans can lower existing rates without a new loan.
If you already hold a loan you think is usurious, do not simply stop paying. Pull the loan agreement, note the disclosed APR, and run the license check above. Then complain to your state regulator and through the CFPB’s complaint portal, which forwards the complaint to the company and tracks its response. Many state attorneys general have dedicated rent-a-bank or payday complaint units, and complaints are how they build cases. A legal aid office can tell you whether your state’s remedy is forfeited interest, a void contract or something in between.
If a collector is pursuing a loan that is void under your state’s law, you can dispute the debt in writing within 30 days of the first notice under the FDCPA, which pauses collection until the collector verifies it.
Where the law is heading
Three fights will decide what usury means over the next few years. The first is the federal 36% cap: the Veterans and Consumers Fair Credit Act and similar bills would extend the Military Lending Act’s cap to everyone, and they have bipartisan sponsors but have not reached a floor vote. The second is the valid-when-made and true-lender question, which will be settled lender by lender in state attorney general actions and in cases like the Colorado opt-out litigation. The third is how regulators classify “tips” and “express fees” in app-based advances, which decides whether those products fall under state small-loan caps at all.
For borrowers the practical rule is older than any of those fights. The number that matters is the APR on the disclosure, the statute that matters is the one your lender is licensed under, and the cheapest credit is almost always the credit you arranged before the emergency.
FAQ
What is usury in simple terms?
Usury is charging interest above the maximum rate a state’s law allows. A loan priced over that limit is usurious, and depending on the state the lender can lose the interest, lose the whole loan, or face criminal charges.
Is there a federal usury law in the United States?
No general one. Federal law caps rates only for active-duty servicemembers and their dependents (36% under the Military Lending Act) and for federal credit unions (18% under NCUA rules). Everyone else is governed by state law, and federal banking law lets banks export their home state’s rate nationwide.
Why can my credit card charge 29% if my state’s usury cap is 12%?
Because the issuer is a bank, and under 12 U.S.C. § 85 and the Marquette decision a bank may charge the rate allowed in its home state, typically South Dakota, Delaware or Utah, which have no cap. Your state’s usury statute does not reach that bank.
What is the difference between civil and criminal usury?
Civil usury is exceeding the contract cap, which usually costs the lender its interest or the loan. Criminal usury is exceeding a higher line, 25% in New York and Florida for example, and exposes the lender to prosecution. A corporation in New York cannot plead civil usury but can plead criminal usury.
Are payday loans usurious?
Only where a state has not carved out a separate payday statute. In states with a 36% cap on small loans, a 391% APR payday loan is illegal and often void. In states like California or Florida, a fee-based payday law makes the same loan legal up to a set amount. In Texas, Utah and Nevada, there is no effective cap.
Do usury laws apply to business loans?
Often not, or only partly. Many states exempt commercial loans above a dollar threshold, bar corporations from raising usury as a defense, or allow any agreed rate for business purposes. Merchant cash advances are structured as purchases of receivables to stay outside usury law entirely.
What can I do if I think my loan is usurious?
Compare the disclosed APR with the cap in the statute your lender is licensed under, verify the license on NMLS Consumer Access or your state regulator’s site, and file complaints with your state attorney general and the CFPB. Legal aid can tell you whether your state’s remedy is forfeited interest, a void loan or multiple damages.