An installment loan is money you borrow in one lump sum and pay back in a set number of scheduled payments, usually monthly, until the balance hits zero. Mortgages, auto loans, student loans and most personal loans all work this way. The structure is simple, but the price ranges from under 10% APR at a credit union to triple digits at some online lenders, so the definition matters less than the math.
StructureLump sum, fixed scheduled payments
Common terms3 months to 30 years
Typical personal loan size$1,000 to $50,000
APR rangeUnder 10% to 160% or more
Required disclosureAPR and total of payments
Governing federal lawTruth in Lending Act
Installment loan definition in plain words
“Installment” just means a portion of a debt paid at an agreed time. When you borrow on installment, you agree to a fixed schedule: this much, on this date, for this many months. Each payment covers that month’s interest plus a slice of the principal. By the final payment the account closes.
That is the core difference from a credit card or a line of credit. Those are revolving credit: you can borrow, repay and borrow again, and your payment changes with your balance. An installment loan is closed-end credit. You get the money once, and the lender tells you the exact payoff date before you sign.
The term “installment buying” comes from the same idea. Retailers have sold furniture, sewing machines and cars on payment plans since the 1800s, and General Motors created its own finance arm, GMAC, in 1919 so buyers could pay for a car over time. Modern buy-now-pay-later plans split into four payments are the latest version of the same thing.
How an installment loan works
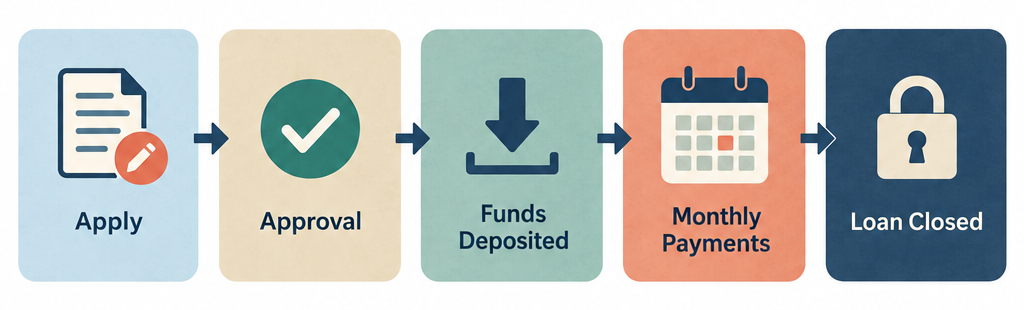
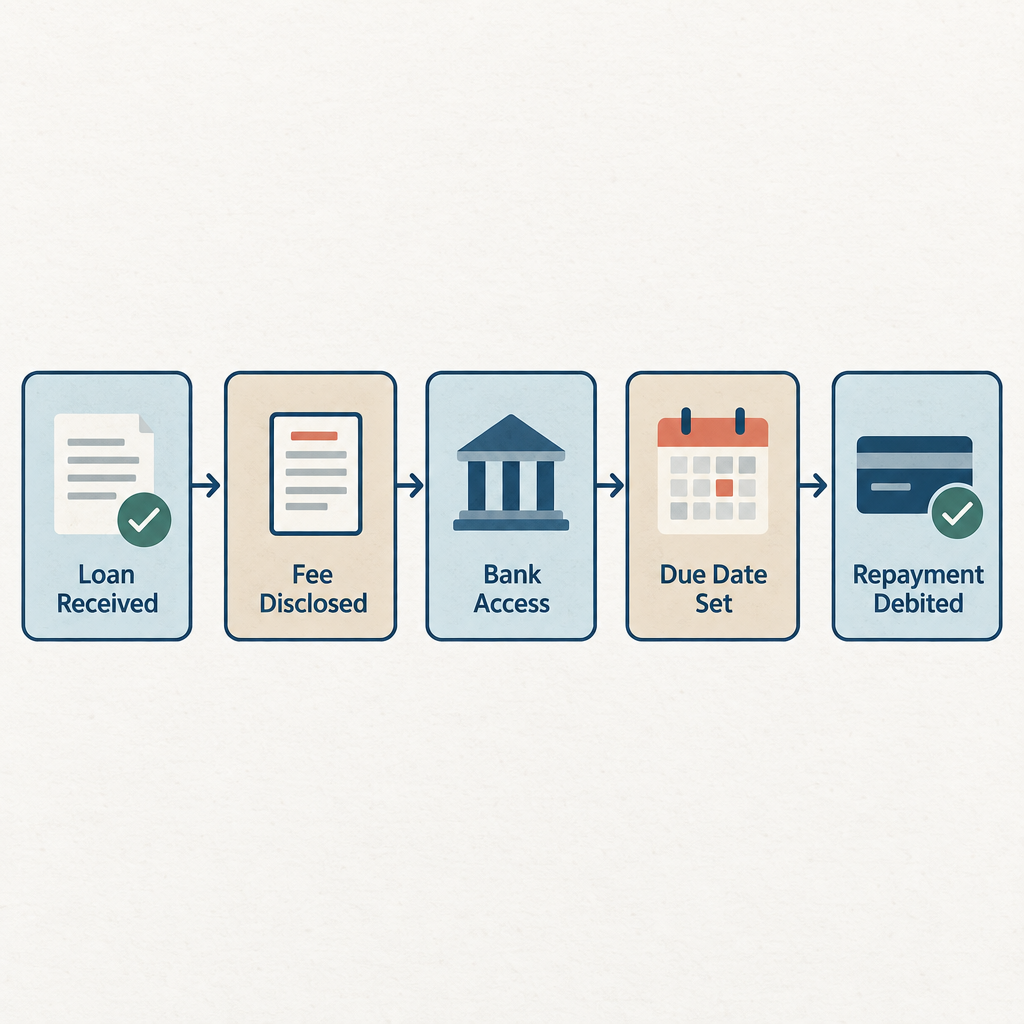
Here is the full cycle for a typical consumer installment loan:
You ask a lender for a specific amount, say $2,000, over a specific term, say 24 months.
The lender checks your credit, income and existing debts, then quotes an interest rate and any fees.
Before you sign, the lender must give you a Truth in Lending disclosure. Under Regulation Z (12 CFR 1026.18), it must show the amount financed, the finance charge, the APR, the total of payments and the payment schedule.
You receive the money, usually by deposit to your bank account within one to five business days.
You make the same payment each month. Early on, most of it is interest. Later, most of it is principal. This is called amortization.
After the last payment the loan is paid in full and reported as closed on your credit file.
The APR is the number to compare. It is the yearly cost of the loan expressed as a percentage, and under the Truth in Lending Act it has to include interest as well as mandatory fees such as an origination charge. That is why two loans with the same interest rate can have different APRs.
What the same $2,000 costs at different rates
Rates on installment loans vary more than on almost any other consumer product. The table below shows the same $2,000 borrowed over 24 months at three rates you might actually be offered, plus a 6-month credit union payday alternative loan for a smaller amount. Figures are rounded to the nearest dollar and assume standard monthly amortization with no extra fees unless noted.
Loan
Amount
APR
Term
Monthly payment
Total repaid
Cost of borrowing
Credit union personal loan
$2,000
12%
24 months
$94
$2,260
$260
Bank or online lender, fair credit
$2,000
36%
24 months
$118
$2,834
$834
High-cost online installment loan
$2,000
160%
12 months
$343
$4,117
$2,117
Federal credit union PAL (28% APR plus $20 fee)
$1,000
28%
6 months
$181
$1,103
$103
The 160% figure is not hypothetical. Several online installment lenders disclose APRs in that range on their own rate pages, often by partnering with out-of-state banks to get around state caps. At that price you pay back more than double what you borrowed in a single year, and a longer term makes it worse, not better.
Here is the plain-words version of the APR math. At 36% APR on a 24-month loan, you are paying roughly 3% of the outstanding balance in interest each month. In month one that is about $60 on a $2,000 balance. As the balance falls, the interest portion falls with it, which is why the total interest ($834) is less than 36% of $2,000 times two years ($1,440).
Before you borrow
The APR and the term decide what you really pay, and a low monthly payment can hide a very expensive loan. Always read the “total of payments” line on the Truth in Lending disclosure before you sign anything.
Examples of installment loans
Consumer installment loans cover a wide range of amounts and terms:
Mortgages: $100,000 and up, typically 15 or 30 years, secured by the home.
Auto loans: a few thousand to $50,000 or more, usually 36 to 84 months, secured by the vehicle.
Federal student loans: Direct Loans default to a 10-year standard repayment plan, with income-driven options that stretch much longer.
Unsecured personal loans: typically $1,000 to $50,000 over 1 to 7 years, from banks, credit unions and online lenders.
Credit union payday alternative loans (PALs): under NCUA rules, PAL I loans run $200 to $1,000 over 1 to 6 months, and PAL II loans run up to $2,000 over up to 12 months, both capped at 28% APR with an application fee of no more than $20.
Small-dollar online installment loans: $300 to $5,000 over 3 to 24 months, often at the highest APRs in the market.
Buy-now-pay-later plans: typically four payments over six weeks with no interest if paid on time, though late fees apply.
A payday loan is not an installment loan in the traditional sense. It is a single balloon payment due on your next payday, usually at $15 per $100 borrowed, which the CFPB calculates at roughly 391% APR on a two-week loan. Some storefront lenders now sell “payday installment loans” that stretch the same pricing over months. Longer is not cheaper when the rate stays that high.
Installment credit vs. revolving credit
Feature
Installment loan
Revolving credit (credit card, line of credit)
How you get money
One lump sum
Borrow as needed up to a limit
Payment
Fixed amount, fixed schedule
Minimum payment that changes with the balance
End date
Set at signing
None while the account stays open
Rate
Usually fixed
Usually variable
Credit score effect
Payment history and credit mix
Payment history and credit utilization
For your credit score, both count heavily toward payment history, which FICO weights at 35% of the score. Installment loans do not affect credit utilization the way a card balance does, and having both types counts toward credit mix, which FICO weights at 10%. If you carry a card balance month to month, it is worth understanding how card interest compounds daily; our “credit card apr explained” article walks through that math.
Pros and cons of installment loans
Strengths
You know the exact payment and payoff date before you commit.
Fixed rates protect you if market rates rise.
A long term can make a large purchase affordable in monthly terms.
On-time payments build positive credit history.
Weaknesses
You cannot re-borrow repaid money without applying again.
Origination fees of 1% to 10% are common on personal loans and come out of your proceeds.
Some lenders charge prepayment penalties, so paying early does not always save money.
A long term at a high APR can cost more in interest than the amount borrowed.
Secured loans put the car or home at risk if you fall behind.
Where installment loans are capped or restricted
State law, not federal law, sets most price limits on consumer installment loans, and the picture is uneven. Illinois caps consumer loans at a 36% all-in APR under its Predatory Loan Prevention Act, which took effect in 2021. New Mexico adopted a 36% cap on most small loans starting in 2023. Colorado voters capped payday loans at 36% in 2018. Several other states, including Delaware, Utah and Idaho, have no general rate cap on small installment loans, which is why triple-digit APRs are legal there.
Many high-cost online lenders route loans through a partner bank chartered in a permissive state and argue that state’s rules apply. Courts and state attorneys general have challenged this “rent-a-bank” model with mixed results. The practical point for you: the rate you are offered depends on your state, and a lender that quotes 36% in one state may quote 160% in another.
Cheaper options first
Ask your local credit union about a personal loan or payday alternative loan; federal credit unions cap most loans at 18% APR under NCUA rules.
Call your utility, landlord or medical provider about a hardship or payment plan before borrowing to pay them.
Nonprofit credit counseling agencies and 211 can point you to local assistance for rent, food and utilities.
If you are borrowing for a sudden bill, our guide on “loans emergency” compares those options in more detail. And if your credit is thin, be skeptical of “no credit check loans“; most lenders run a soft pull or use bank data, and the trade-off for skipping a hard credit check is usually a much higher price.
Your rights when you take an installment loan
Truth in Lending Act / Regulation Z (12 CFR 1026): the lender must disclose the APR, finance charge, amount financed, total of payments and schedule before you sign.
Equal Credit Opportunity Act / Regulation B: a lender cannot deny you based on race, sex, marital status, age, religion, national origin or receipt of public assistance, and must tell you the specific reasons for a denial within 30 days.
Fair Credit Reporting Act: you can get a free credit report, dispute errors, and you are entitled to a notice if adverse information in your report led to worse terms.
Electronic Fund Transfer Act / Regulation E (12 CFR 1005.10(e)): a lender cannot require you to repay by automatic electronic debit as a condition of getting the loan.
Military Lending Act (32 CFR 232): active-duty servicemembers and their dependents cannot be charged more than 36% Military APR on most consumer loans, and the lender cannot require arbitration.
Servicemembers Civil Relief Act: interest on debts you took on before active duty is capped at 6% while you serve.
Fair Debt Collection Practices Act: if the loan goes to a third-party collector, that collector cannot harass you, call at unreasonable hours or misrepresent what you owe.
How to check a lender before you sign
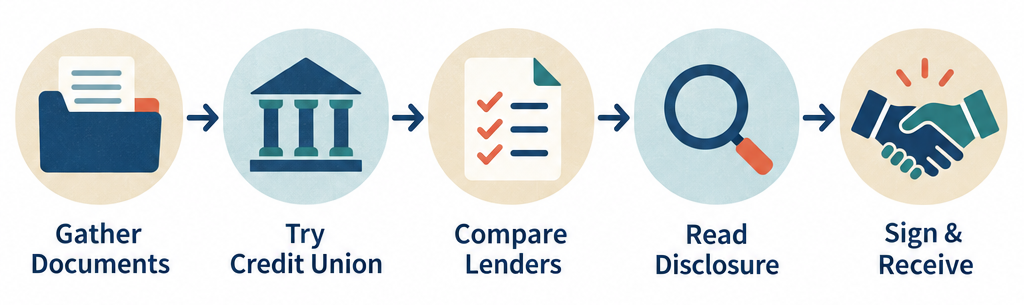
Look the company up on NMLS Consumer Access and confirm it holds a consumer lending license in your state.
Search the CFPB complaint database for the lender’s name and read how it responds.
Find the APR and total of payments on the disclosure, and ask whether there is a prepayment penalty.
Confirm the lender will report your payments to the credit bureaus if building credit is a goal.
Walk away from any lender that asks for an upfront fee before funding; that is a classic advance-fee scam.
If a lender breaks these rules, you can file a complaint with the CFPB, your state attorney general or state banking regulator, and the FTC through ReportFraud.
FAQ
What is an installment loan?
An installment loan is a closed-end loan you receive as a lump sum and repay in fixed, scheduled payments over a set term. Each payment includes interest and principal, and the loan is paid off by a date set when you sign. Mortgages, car loans, student loans and personal loans are all installment loans.
Are installment loans hard to get?
It depends on the lender and your credit. Banks and credit unions typically want a FICO score in the mid-600s or higher and a manageable debt-to-income ratio. Online lenders will approve lower scores, but at higher APRs, sometimes above 100%. Credit union payday alternative loans require only that you have been a member for about a month and have a steady income.
Is installment loan trustworthy?
The product itself is standard, regulated credit. The lender is what you need to vet. A trustworthy lender is licensed in your state, shows the APR and total cost before you commit, never asks for money upfront, and reports to the credit bureaus. Check NMLS Consumer Access and the CFPB complaint database before you sign.
What credit score is needed for an installment loan?
There is no single minimum. Prime rates from banks generally start around a 670 FICO score, and the lowest advertised rates usually require 720 or higher. Scores in the 580 to 660 range can still qualify with many online lenders and credit unions, but expect APRs between 20% and 36%. Below 580, offers tend to be high-cost or secured. A denial must come with specific reasons under the Equal Credit Opportunity Act, so you will know what to fix.
No credit check loans are small loans where the lender skips the hard inquiry at Equifax, Experian or TransUnion and decides based on your income, bank activity or collateral instead. They are real and legal in most states, but the price for skipping that check is steep: triple-digit APRs are normal, and the cheapest versions are not the ones advertised most loudly. This guide explains what lenders look at instead, what each type actually costs, where state law limits them, and which federal protections still apply to you.
Typical payday APRaround 400%
Typical loan size$100 to $1,500
Credit checksoft pull or none
Safer benchmark36% APR or less
Banned or cappedabout 20 states plus DC
As ofOctober 2026
What “no credit check” really means
The phrase does not mean nobody looks at you. It means the lender does not pull a traditional credit report with a hard inquiry, the kind that shows up on your file and can nudge your score down.
Almost every lender that advertises no credit check for loans still runs some form of screening. The three common methods:
Soft inquiry. The lender views your credit file without recording a hard pull. Soft inquiries are visible only to you and do not affect FICO or VantageScore calculations.
Alternative data. Specialty consumer reporting agencies such as Clarity Services (owned by Experian), FactorTrust (owned by TransUnion) and Teletrack collect records on small-dollar borrowing, bounced checks and prior payday activity. The CFPB publishes a list of these companies each year, and the Fair Credit Reporting Act covers them the same way it covers the big three.
Bank account review. Cash advance apps and many online lenders connect to your checking account through a service like Plaid and read your deposits, balance history and overdrafts directly.
So “no check credit loans” is more accurately “no hard pull loans.” A lender with a license still has to confirm you have income and a way to repay. A company that promises money with no questions at all is usually a scam, which we cover below.
Hard pull vs soft pull: why lenders skip the hard one
A hard inquiry stays on your credit report for two years, and FICO says it counts toward your score for 12 months, usually costing fewer than five points. Lenders skip it for two reasons. Hard pulls cost them money, and many of their customers have scores so low that the report would not change the decision anyway. The pricing already assumes a high default rate.
What no credit check lenders look at instead
What they check
How they check it
Why it matters to the lender
Steady income
Pay stubs, direct deposit history, employer verification
Confirms a paycheck is coming before the due date
Active checking account
Bank login or voided check
Needed to pull repayment automatically
Specialty credit files
Clarity, FactorTrust, Teletrack
Shows other open payday or installment loans and defaults
Prior loans with the same lender
Internal records
Repeat customers with clean records get bigger limits
Collateral
Car title, pawned item
Lender can seize and sell it if you default
Identity and residency
ID, address, Social Security number
Required by state licensing and federal anti-fraud rules
Because specialty bureaus fall under the Fair Credit Reporting Act, you have the same rights there as with Experian. You can request your file, dispute errors, and the lender must send you an adverse action notice if a report is part of the reason for a denial.
The five main types and what each one costs
Every product below skips the hard inquiry. They differ enormously in price.
1. Payday loans
A payday loan is a single-payment loan, usually $500 or less, due on your next payday. The CFPB reports that fees typically run $10 to $30 per $100 borrowed, and that a common $15 fee per $100 for two weeks works out to an APR near 400%. The loan does not build credit because most payday lenders never report on-time payments to the big three bureaus. They do often report defaults.
2. Online installment loans
These spread repayment over three to twelve months with fixed payments. Lenders that skip hard pulls generally price them between roughly 100% and 300% APR depending on the state. Some report payments to the bureaus, which can help your score if you never miss one. The longer term makes each payment look manageable, but it also multiplies total interest.
3. Cash advance apps
Apps like Earnin, Dave, Brigit, Chime’s MyPay and EarnIn-style employer programs advance a slice of wages you have already earned, typically $20 to $750. They don’t run credit checks and instead read your bank deposits. Most charge no mandatory interest, but they make money from monthly subscriptions, optional tips and instant-transfer fees of a few dollars. Those small fees produce large APRs on short terms, which is why the CFPB proposed in July 2024 to treat paycheck advances as credit under the Truth in Lending Act. The agency withdrew that proposal in May 2025, so as of October 2026 there is no federal rule requiring these apps to show you an APR. Several states, including California, Connecticut, Kansas, Maryland, Nevada and Wisconsin, have passed their own earned wage access laws.
4. Auto title loans
You hand over your car title, keep driving, and borrow a fraction of the vehicle’s value for 30 days at a monthly fee that often equals 25%, or about 300% APR. In a 2016 study, the CFPB found that one in five single-payment title loan borrowers ended up having the vehicle repossessed. Title lending is banned or heavily restricted in more than half the states.
5. Pawn loans
A pawnshop lends you a portion of an item’s resale value, commonly 25% to 60%, and holds the item. Fees are set by state law, and in many states they translate to APRs well over 100%. The one genuine advantage: if you don’t repay, you lose the item and nothing else. No collections, no bank garnishment, nothing on your credit report.
Worked cost examples
The figures below use representative prices. Your lender’s Truth in Lending disclosure will show the exact APR and finance charge, which it must give you before you sign under Regulation Z (12 CFR 1026).
Product
Amount borrowed
Fee or APR
Term
Total repaid
Effective APR
Payday loan
$300
$15 per $100
14 days
$345
391%
Online installment loan
$1,000
199% APR
9 months
about $1,860
199%
Cash advance app
$100
$4 instant fee, no tip
10 days
$104
146%
Auto title loan
$700
25% monthly fee
30 days
$875
300%
Pawn loan
$150
20% monthly charge
30 days
$180
240%
Credit union PAL (for comparison)
$500
28% APR plus $20 fee
6 months
about $562
28% plus fee
The APR math in plain words: divide the fee by the amount borrowed, then multiply by the number of loan periods in a year. On the payday example, $45 divided by $300 is 15%. A 14-day loan has about 26 periods in a year. Fifteen percent times 26 is roughly 391%. The same arithmetic turns a “small” $4 app fee into 146% because ten days fits into a year 36 times.
If you want to understand why a 24% credit card looks cheap next to these, our piece on “credit card apr explained” walks through the same math for revolving balances.
Before you borrow
The real danger is not the first fee but the rollover: CFPB research found that most payday loan fees are paid by borrowers who take seven or more loans a year, and a single $45 fee repeated every two weeks costs more than $1,100 over a year on a $300 balance you never actually pay down.
Where no credit check loans are banned or capped
State law, not federal law, decides whether these products exist where you live and how much they can charge. There is no nationwide no credit check lending market. An online lender that is licensed in Nevada cannot legally charge Nevada rates to a borrower in New York.
State approach
What it means for you
Examples
Payday lending banned or capped near 36% APR
Storefront payday loans don’t exist; online lenders must follow the cap or stay out
Arizona, Arkansas, Colorado, Georgia, Illinois, Maryland, Massachusetts, Minnesota, Nebraska, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, South Dakota, Vermont, West Virginia, Washington DC
Payday allowed with limits
Caps on loan size, number of rollovers, or a cooling-off period
Washington, Florida, Ohio (since 2019 reform), Virginia (since 2021 reform)
The count of states with a 36% cap has grown steadily. Illinois passed its Predatory Loan Prevention Act in 2021, New Mexico passed its 36% cap in 2022 with an effective date of January 1, 2023, and Minnesota’s cap took effect in 2024. Check your state’s current rule with its financial regulator before assuming a product you saw advertised is legal where you live.
Tribal lenders and lenders using “rent-a-bank” arrangements sometimes claim your state’s cap does not apply to them. Courts and state attorneys general have challenged many of these structures. If a lender tells you a cap doesn’t apply, that’s a reason to be more careful, not less.
Who a no credit check loan can make sense for
We don’t recommend these products, but we also won’t pretend nobody has a rational reason to use one. A short-term advance can be the least bad option when all four of these are true:
The expense is genuinely unavoidable, like a car repair you need to keep your job.
You have confirmed income arriving before the due date that covers the full payment plus your normal bills.
You have already been turned down for or cannot access the cheaper options below.
You are borrowing once, with no plan to renew.
A one-time $200 app advance with a $4 fee is a very different decision from a $700 title loan you expect to roll over. If you’re searching for “loans emergency” because the car won’t start tomorrow, the app advance or a pawn loan limits your downside. The title loan puts the car itself at risk.
Cheaper options to check first
Cheaper options first
A federal credit union payday alternative loan caps APR at 28% and lends $200 to $2,000.
Your employer, utility company and hospital may offer a no-fee advance or payment plan if you ask.
Nonprofit credit counseling agencies and local assistance programs (211) cost nothing to call.
Credit union payday alternative loans (PALs)
Federal credit unions can offer two versions under NCUA rules (12 CFR 701.21). PAL I lends $200 to $1,000 for one to six months to members of at least one month. PAL II lends up to $2,000 for one to twelve months with no waiting period. Both cap the APR at 28% and the application fee at $20. Many credit unions make these without a hard pull, relying on your membership and income instead. You must be eligible to join the credit union, which is often as simple as living in its county.
Employer and app advances with no fee
Some employers offer earned wage access through payroll providers at no cost to you. Apps that charge nothing for standard transfers in one to three business days are also far cheaper than the instant option. Waiting two days can turn a 146% APR into 0%.
Hardship plans and bill negotiation
Utilities in most states must offer payment arrangements before disconnecting service. Hospitals that are nonprofits must have a financial assistance policy under IRS rules. Landlords, phone carriers and even the IRS offer payment plans. None of these involve a credit check.
Secured and credit-builder products
A secured credit card or a credit-builder loan from a credit union won’t fix tomorrow’s emergency, but either one gets you out of the no credit check market within a year. Credit-builder loans in particular report monthly to all three bureaus.
Help with the pattern, not just the loan
If you find yourself taking a new advance every pay period, the problem is usually the cash flow gap, not the lender. Nonprofit counseling through the National Foundation for Credit Counseling is free for a first session, and peer programs like “debtors anonymous” exist for people whose borrowing has become compulsive.
Your rights when you borrow without a credit check
Skipping the credit check does not skip the law. These federal protections apply whether the lender checked your credit or not.
Truth in Lending Act and Regulation Z. Before you sign, the lender must disclose the APR, the finance charge in dollars, the amount financed and the total of payments. If you don’t see an APR, you cannot compare the loan and should walk away.
Equal Credit Opportunity Act (Regulation B, 12 CFR 1002). Lenders cannot deny you based on race, sex, age, marital status, or because your income comes from public assistance. If denied, you get a written reason within 30 days.
Fair Credit Reporting Act. If a specialty bureau report contributed to a denial, you must be told which one and can get that report free. You can dispute inaccurate items.
Electronic Fund Transfer Act. Under 15 U.S.C. 1693k and Regulation E, a lender cannot require you to repay by preauthorized electronic debit as a condition of the loan. You can also revoke an authorization you gave, though you still owe the money.
Military Lending Act. Active-duty servicemembers and their dependents cannot be charged more than a 36% Military APR, and payday, title and refund-anticipation loans at higher rates are simply unlawful for them. The Servicemembers Civil Relief Act separately caps interest at 6% on debts taken on before active duty.
Fair Debt Collection Practices Act. Third-party collectors cannot threaten arrest, call you at work after you ask them to stop, or contact you before 8 a.m. or after 9 p.m. Defaulting on a civil debt is not a crime anywhere in the United States, no matter what a caller says.
Federal rules set a floor. Your state may add rollover limits, a right to cancel by the next business day, a free extended payment plan, or a database that blocks a second loan while one is open.
How to spot a scam lender
Advance-fee loan fraud is one of the most common complaints the FTC receives, and “guaranteed approval” ads are its favorite bait. Under the FTC’s Telemarketing Sales Rule (16 CFR 310.4), it is illegal for a telemarketer to ask you to pay any fee in advance for a loan they promise or claim is likely. A real lender deducts fees from the loan or adds them to your payments. It never asks for a gift card, wire or crypto payment up front.
Other red flags: no physical address, no state license number on the website, pressure to decide within minutes, and a request for your online banking password rather than a read-only connection. The claims behind “urgent loans guaranteed approval” ads deserve the same skepticism, because no licensed lender can lawfully approve a loan before it has seen an application.
How to check a lender before you share your bank details
Search the company name and NMLS ID on NMLS Consumer Access to confirm it holds a license for your state.
Check your state financial regulator’s own license lookup, since some states license small lenders outside NMLS.
Search the CFPB Consumer Complaint Database for the company name and read the most recent complaints.
Confirm the website lists a street address, a phone number that answers, and a Truth in Lending disclosure with an APR.
Report suspected fraud to the FTC at ReportFraud, the CFPB complaint portal, and your state attorney general.
FAQ
Can I borrow money without a credit check?
Yes. Payday lenders, cash advance apps, pawnshops, title lenders and some credit unions all lend without a hard inquiry. Most still verify income and look at your bank activity or a specialty credit file, and the price is usually far higher than a loan that does check credit.
Where can I borrow money without a credit check?
The cheapest places are federal credit unions offering payday alternative loans at 28% APR or less, employer-sponsored wage advances, and apps that charge no fee for standard-speed transfers. Storefront payday and title lenders and online installment lenders are the most expensive, and they’re not legal in every state.
What is the easiest loan to get approved for with no credit?
A pawn loan is the easiest because approval depends only on the item you bring in. Cash advance apps are next, since they need only a checking account with regular direct deposits. Easiest does not mean cheapest, and pawn means losing the item if you can’t repay.
Can I get a genuine loan without a credit check?
Genuine, licensed lenders do offer no credit check loans, but they always ask for something: proof of income, bank access, or collateral. A lender that promises approval before seeing any information, or asks you to pay a fee before funding, is running a scam rather than a loan program.
Do no credit check loans build credit?
Rarely. Most payday, title and pawn lenders report nothing to Equifax, Experian or TransUnion when you pay on time. Some online installment lenders and most credit unions do report, so ask before you borrow if building a score is part of the goal.
What happens if I can’t repay?
With a pawn loan you lose the item and nothing more. With a title loan the lender can repossess the car. With payday and installment loans the lender may keep attempting debits, send the debt to collections, and in some states sue you. Ask about your state’s extended payment plan rules before the due date, since several states require lenders to offer one free of charge.
A cash advance app lets you pull a few hundred dollars forward from your next paycheck, usually for a subscription, an express fee or a “tip” rather than stated interest. We ranked the apps that publish their terms, worked out what each one actually costs on a typical two-week advance, and set the whole category next to the cheaper options a credit union or your employer may already offer.
Typical advance$20 to $500
Mandatory fees$0 to $40 per advance
Express delivery$0.99 to $15
Effective APRoften 65% to 230%
Credit checknone for most apps
Repaymentyour next payday
Key takeaways
No app on this list charges stated interest, but almost all of them earn money from express fees, monthly subscriptions or default tip prompts. A $3.99 fee on a $100 advance repaid in 14 days works out to an APR above 100%.
The cheapest advances come from the bank you already use. Chime MyPay and Varo Advance only serve their own account holders, and that is exactly why they can afford to charge so little.
Advances are small. The headline “up to $500” or “up to $750” figure is a ceiling that new users rarely reach. The FTC has sued or settled with Brigit, Cleo, FloatMe and Dave over the gap between advertised and actual amounts.
Nothing here builds credit. Apps do not report to Equifax, Experian or TransUnion, so paying on time gains you nothing, and most apps also do not run a hard credit check.
Repayment is automatic. The app debits your linked account on payday, and the biggest hidden cost is the overdraft that debit can trigger at your bank.
How we ranked these cash advance apps
We compared apps on six criteria: total cost of a typical advance, whether a free delivery option exists, how clearly the fee is disclosed before you accept, the realistic advance limit for a new user, delivery speed, and the company’s record with regulators. We only included apps that publish fee schedules and that operate under a licensed bank partner or a state registration. Each app got a real weakness in its write-up, because every one of them has at least one.
Figures below come from each app’s published fee disclosure and terms at the time of writing. Apps change pricing often and quietly, so read the exact fee on the confirmation screen before you tap accept.
Best cash advance apps compared at a glance
Rank
App
Max advance
Mandatory cost
Free delivery?
Instant delivery fee
Needs its own bank account?
1
EarnIn (Cash Out)
$150/day, $750/pay period
$0
Yes, 1 to 3 business days
$2.99 to $5.99
No
2
Chime (MyPay)
$500
$0
Yes, by next day
$2 to $5 (3% of amount)
Yes, Chime checking with direct deposit
3
Varo (Advance)
$500
$0 to $40 flat, by amount
Instant is standard
Included in flat fee
Yes, Varo Bank account with direct deposit
4
Cash App (Borrow)
$200
5% flat
No separate tiers
Included
Yes, active Cash App account
5
MoneyLion (Instacash)
$500, higher with RoarMoney
$0
Yes, 1 to 5 business days
$0.49 to $8.99
No
6
Dave (ExtraCash)
$500
$1/month plus 5% (min $5, max $15)
No under current pricing
Included in 5% fee
No
7
Current (Paycheck Advance)
Scaled to deposit history
$0
Yes, standard delivery
Varies by amount
Yes, Current account with direct deposit
8
Brigit (Instant Cash)
$250
$9.99 or $14.99/month
Yes, 1 to 3 business days
$0.99 to $3.99
No
9
Empower (Cash Advance)
$400
$8/month
Yes, 1 to 2 business days
$1 to $8
No
Klover, Albert and Cleo also offer advances. They did not make the ranked list because their published limits for new users are low, their subscription plus express pricing lands near the top of the cost range, and in Cleo’s case the FTC reached a $17 million settlement with the company in 2025 over advertised advance amounts and cancellation practices.
Before you borrow
The real risk with a cash advance app is not the fee on the first advance. It is the loop: the app debits your full balance on payday, your check is short, and you take another advance the same day. CFPB research found the average user takes more than two dozen advances a year.
What a cash advance app really costs
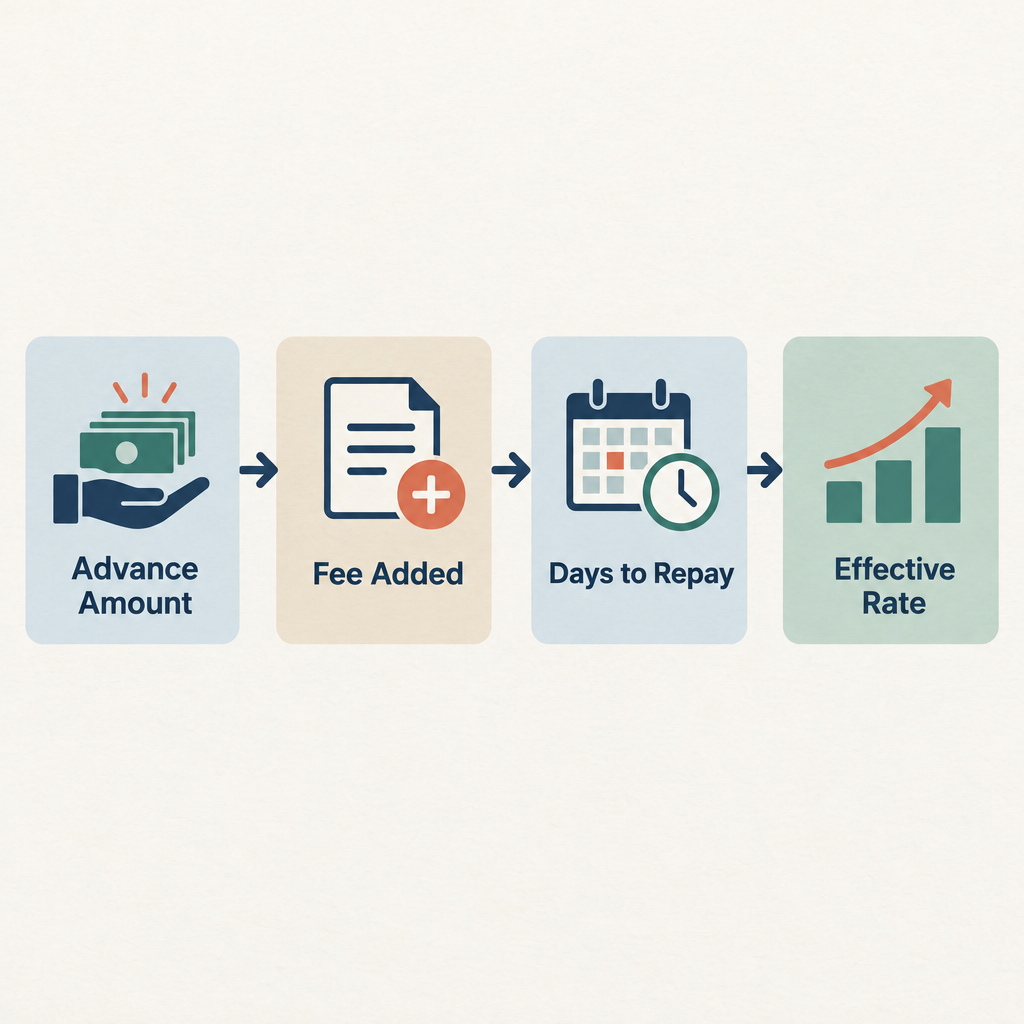
Apps do not quote an APR, so you have to compute it yourself. The math is simple: divide the fee by the amount, then multiply by 365 divided by the number of days until repayment. A $3.99 fee on $100 for 14 days is 3.99 divided by 100, times 26.07, which comes to about 104%.
That is the number to compare against a credit union loan or a credit card cash advance, because it puts a 14-day product and a 12-month product on the same scale. The CFPB’s July 2024 data spotlight on paycheck advance products found the typical advance was a little over $100 and that the average effective APR, for users who paid a fee or tip, was above 100%.
App and scenario
Amount
Fees you pay
Days to repay
Total repaid
Effective APR
EarnIn, standard delivery, no tip
$100
$0
14
$100.00
0%
EarnIn, Lightning Speed at $3.99, no tip
$100
$3.99
14
$103.99
104%
EarnIn, Lightning Speed plus $5 tip
$100
$8.99
14
$108.99
234%
Chime MyPay, instant
$500
$5.00
14
$505.00
26%
Varo Advance, top tier
$500
$40.00
30
$540.00
97%
Cash App Borrow
$200
$10.00
28
$210.00
65%
MoneyLion Instacash, Turbo at $8.99
$500
$8.99
14
$508.99
47%
Dave ExtraCash, 5% fee plus $1 membership
$200
$11.00
14
$211.00
143%
Dave ExtraCash at the $15 fee cap plus $1
$500
$16.00
14
$516.00
83%
Brigit Plus, standard delivery
$250
$9.99
14
$259.99
104%
Empower, subscription plus $8 instant fee
$300
$16.00
14
$316.00
139%
Credit union PAL, 28% APR plus $20 application fee
Two things stand out. First, the gap between apps is large: Chime’s $5 instant fee on $500 is a third of Dave’s capped fee on the same amount, and one fifteenth of what a payday loan charges. Second, every app that charges a percentage or a subscription gets more expensive as the advance gets smaller, which is backwards from how most credit works. A $9.99 monthly plan to borrow $50 is an APR near 520%.
The tip line matters more than it looks. EarnIn and MoneyLion present a tip slider on the confirmation screen, and the CFPB’s 2024 analysis treated tips as part of the cost because so few users set them to zero. You can. Nothing in either app’s terms penalizes a $0 tip.
The 9 cash advance apps, ranked
1. EarnIn Cash Out: top pick for borrowing against hours you already worked
EarnIn is our top pick because it is the only app with no subscription, no mandatory fee and no requirement to move your bank account. You connect a checking account that receives direct deposit, add your employer and either a work address or a timesheet, and EarnIn tracks earnings as you go. Cash Out lets you pull up to $150 a day and $750 per pay period, repaid by a debit on payday.
Standard delivery takes one to three business days and costs nothing. Lightning Speed delivers in minutes for $2.99 to $5.99 depending on the amount. The tip prompt defaults to a dollar figure, so set it to zero every time if you want the free product. The app also has a Balance Shield feature that auto-advances when your balance drops below a threshold you set, which is convenient and also the fastest route into the repeat loop described above.
Weaknesses: new users start well below the $750 ceiling and limits rise slowly. Earnings verification can fail for tipped, gig or irregular-hours workers. EarnIn paused or limited service in Connecticut after that state brought earned wage access under its small loan law in 2023, so the app is not available everywhere.
2. Chime MyPay: cheapest option if your paycheck already lands at Chime
MyPay is a feature of Chime’s checking account, not a standalone app. Members with a qualifying direct deposit can access up to $500 of pay before payday. Delivery by the next day costs nothing. Instant delivery costs 3% of the amount, with a $2 minimum and a $5 cap, which still makes it one of the cheapest instant advances in the market. Chime repays itself from the direct deposit when it arrives.
Chime is a financial technology company, not a bank. Deposits are held at The Bancorp Bank, N.A. or Stride Bank, N.A., both FDIC members, and that is who you are actually banking with.
Weaknesses: you have to move your direct deposit to Chime to use it, and switching banks to get a cheap advance is a big step for a small benefit. Your limit is set by Chime’s read of your deposit history, and new members typically see far less than $500. If your employer’s pay date slips, the repayment and the deposit can land out of order.
3. Varo Advance: flat fees with no subscription and no tips
Varo Bank, N.A. is a chartered bank, which makes it unusual on this list. Varo Advance lets qualifying account holders with direct deposit borrow $20 to $500 and repay within 30 days. The fee is a flat amount tied to the advance size, shown in the app before you accept. There is no monthly plan, no express surcharge and no tip screen.
That flat fee schedule is the honest part. The fee on a large advance is not cheap, but it is printed in the app before you accept and it never changes based on how fast you want the money.
Weaknesses: you need a Varo account with recent qualifying direct deposits. Small advances are a bargain and large ones are not, so the product rewards borrowing $20 and punishes borrowing $500. The 30-day term is longer than most apps’, which helps cash flow but makes it easy to forget the debit.
4. Cash App Borrow: the “money app cash advance” most people are searching for
When readers search for a money app cash advance they usually mean Cash App. Borrow is Cash App’s small loan feature: up to $200 for eligible users, a flat 5% fee, and four weeks to repay. A $200 loan costs $10, a 65% APR, with no tip prompt and no subscription. Repayment can be weekly or in a single payment at the end.
Borrow is a loan, not an earned wage product, so it is disclosed as one. Late balances accrue a 1.25% weekly finance charge after a short grace period, which is the one way the price can climb.
Weaknesses: Borrow is invitation-only. Cash App enables it based on your account activity and location, and there is no way to apply. Limits start low. The late charge compounds weekly, so a $200 balance left alone for three months costs noticeably more than the headline 5%.
5. MoneyLion Instacash: biggest advances without switching banks
Instacash advances run up to $500 for users who link an outside checking account, and MoneyLion advertises higher limits for people who move their direct deposit to its RoarMoney account. No subscription is required for Instacash itself. Standard delivery is free and takes one to five business days to an external bank. Turbo delivery costs $0.49 to $8.99 depending on the amount and where it is going, and there is an optional tip.
The published Turbo fee for a $500 advance is lower than Dave’s capped fee, which is why MoneyLion ranks above Dave despite similar limits.
Weaknesses: the five-day standard window to an outside bank is the slowest free option on the list, so most users end up paying for Turbo. The app aggressively cross-sells its paid membership, credit builder loan and investing products. The CFPB sued MoneyLion in 2022, alleging its membership fees pushed loans to servicemembers over the Military Lending Act’s 36% cap; the company contested the case.
6. Dave ExtraCash: a bigger limit at a higher price
Dave advertises ExtraCash advances up to $500 and charges a $1 monthly membership. Under the pricing Dave has published most recently, each advance carries two mandatory charges: the monthly membership fee plus a 5% service fee on the amount, with a $5 minimum and a $15 cap. Dave dropped tips in early 2025. A $100 advance costs $5 plus the membership dollar. A $500 advance costs the capped $15.
That structure is simpler than the old mix of express fees and tips, and the $15 cap makes Dave reasonable on large advances. It also means there is no longer a free slow option; check the current terms, because this is the fee structure that changed most recently.
Weaknesses: on small advances the $5 minimum is steep, a 130% APR on $100 over two weeks. In November 2024 the FTC, later joined by the Department of Justice, sued Dave over its “up to $500” advertising and the way it disclosed express fees and tips. Dave disputed the claims. Whatever the outcome, the complaint lays out the gap between advertised and typical advance amounts in detail.
7. Current Paycheck Advance: best for existing Current members with steady deposits
Current is another fintech checking account, with deposits held at partner banks. Paycheck Advance lets members who direct deposit their pay access a portion of it early, with the limit set by the size and consistency of their deposit history. Standard delivery is free; instant delivery carries a fee that scales with the amount. Repayment comes out of the next deposit.
Weaknesses: like Chime and Varo, this only works if your pay already goes to Current. Limits for new members are modest, and Current publishes the instant fee inside the app rather than on a public schedule, so you cannot price it before you open an account.
8. Brigit Instant Cash: budgeting alerts bundled with a small advance
Brigit’s advance is only available on a paid plan: Plus at $9.99 a month or Premium at $14.99 a month. Advances run from $50 up to $250 (Brigit advertises higher amounts for some longer-tenured members). Standard delivery is free in one to three business days, and instant delivery costs $0.99 to $3.99. The plan also includes overdraft prediction alerts, credit monitoring and a credit builder product.
Weaknesses: the subscription is the whole problem. Paying $9.99 to borrow $100 once in a month is a 260% APR before any express fee. In November 2023 Brigit paid $18 million to settle FTC allegations that it advertised “up to $250” to users who could not get that amount and made the subscription hard to cancel, which the FTC pursued under the FTC Act and the Restore Online Shoppers’ Confidence Act.
Empower advances up to $400 for $8 a month, with free delivery in one to two business days or instant delivery for $1 to $8. Approval leans on bank account cash flow rather than a credit score, and the app does a decent job showing the fee before you accept.
Weaknesses: the subscription stacks with the express fee, so a $300 instant advance can cost $16 for two weeks, a 139% APR. Empower also pushes its Thrive line of credit, which is a separate product with its own cost, in the same screens where you manage advances.
Apps that did not make the cut
Klover offers advances up to about $200 and makes money partly by asking you to share shopping and transaction data for points, with express fees that vary widely by amount and bank. Albert bundles advances into a paid subscription and has changed its limits and plan pricing repeatedly. Cleo charges a monthly plan and settled with the FTC in March 2025 for $17 million over deceptive advance amounts. FloatMe paid $3 million to the FTC in early 2024 over similar claims. Beem, Grant, VANSi and similar names that appear in app store search results publish thin or shifting fee information, which is enough on its own to leave them off a ranked list.
Cheaper options first
Ask your employer about an earned wage program; many pay the provider’s fee so your advance is free.
Check a credit union’s payday alternative loan: $200 to $1,000 at a 28% APR ceiling under NCUA rules.
Big banks now offer small-dollar loans with flat fees: Bank of America Balance Assist charges $5, U.S. Bank Simple Loan charges $6 per $100.
Cheaper ways to get the same money
Everything in the ranked list is a last-mile product. Before you connect a bank account to any of them, price these.
$0 if your employer pays the fee; otherwise a few dollars
Next payday
Employees of participating companies
Credit union payday alternative loan (PAL)
$200 to $1,000
Max 28% APR, application fee up to $20
1 to 6 months
Members of a participating federal credit union
Bank of America Balance Assist
$100 to $500
$5 flat
3 monthly installments
Existing checking customers
U.S. Bank Simple Loan
$100 to $1,000
$6 per $100
3 monthly installments
Existing checking customers with direct deposit
Wells Fargo Flex Loan
$250 or $500
$12 or $20 flat
4 monthly payments
Existing customers invited in the app
Huntington Standby Cash
$100 to $1,000
0% with autopay, otherwise 1% a month
3 monthly payments
Existing checking customers
Nonprofit credit counseling hardship plan
Varies
Free or low cost
Varies
Anyone; look for NFCC member agencies
Utility and rent hardship programs, 211 referrals
Bill-specific
$0
Varies
Income-based
The NCUA’s payday alternative loan rule, 12 CFR 701.21(c)(7)(iii), sets the PAL terms above: $200 to $1,000, one to six months, a 28% APR ceiling, an application fee of no more than $20, and one month of membership before borrowing. PAL II loans under the same regulation go up to $2,000 for up to 12 months with no membership waiting period. A $500 PAL at 28% for three months costs about $24 in interest plus the application fee, which is less than a single month of Brigit Premium plus two express fees.
An employer-based program is different from a consumer app in one key way: the employer or payroll provider verifies the hours, so there is no bank-account scraping and often no fee to you at all. If your workplace offers one, it beats every consumer app in this article on cost. For readers comparing a paycheck loan from a lender against this kind of employer program, the difference in price is usually several hundred percentage points of APR.
How a cash advance app decides what you get
None of these apps run a hard credit inquiry, which is why they can claim “no credit check.” What they do instead is read your bank account. You grant access through Plaid or a similar aggregator, and the app looks at how often direct deposits land, how large they are, how low your balance dips between paydays, and whether you have bounced payments. EarnIn goes further and ties the advance to verified hours worked.
That is why limits start small. The app has no credit report to lean on, so it tests you with $25 or $50 and raises the ceiling as it watches you repay. Advertised maximums describe long-tenured users with large, steady deposits. The FTC’s complaints against Brigit, Cleo and Dave all turned on this point: most users never saw the headline amount.
Gig workers, tipped employees and anyone paid by paper check or irregular transfers tend to get the lowest limits or get declined, because the model cannot find a predictable paycheck to borrow against.
Where cash advance apps are regulated
There is no single federal rule for this category, and the picture has shifted twice in two years.
At the federal level, the CFPB issued an advisory opinion in 2020 saying a narrow kind of employer-integrated, no-fee earned wage product was not “credit” under the Truth in Lending Act. In July 2024 the Bureau proposed an interpretive rule going the other way, stating that paycheck advance products are credit under Regulation Z (12 CFR 1026) and that expedite fees and tips count as finance charges that must be disclosed with an APR. In May 2025 the CFPB withdrew that proposed rule along with dozens of other guidance documents. As a result, federal treatment is unsettled, and no app currently shows you an APR because none is required to.
States have filled the gap, and they disagree with each other.
State
What the law does
Effect on apps
Nevada
2023 law (SB 290) created the first earned wage access license; providers must offer a free option, cannot require tips and cannot pursue collections or report to credit bureaus
Apps operate under license; not treated as loans
Missouri
2023 registration law modeled on Nevada’s
Similar to Nevada
Wisconsin, Kansas, South Carolina
2024 licensing laws with free-option and no-mandatory-tip rules
Similar to Nevada
Connecticut
2023 law counts app fees and tips as interest under the small loan act
Several apps, including EarnIn, limited or paused service
California
DFPI rules effective February 2025 require providers to register and report advances as loans, with fees and tips tracked as charges
Apps must register with DFPI; no fee cap yet
Maryland
2025 law adds licensing and fee limits for earned wage access
New rules; check the Commissioner of Financial Regulation
Several more states, including Indiana and Arkansas, passed licensing laws in 2025, and the list keeps growing. The practical takeaway: an app available to a friend in Nevada may not serve you in Connecticut, and an app’s fee in California is reported to a regulator while the same fee in Texas is not. Check your state regulator’s license lookup before assuming a product is available or overseen where you live.
Your rights when you use a cash advance app
Even without a settled federal rule, several laws already apply to the mechanics.
Electronic Fund Transfer Act and Regulation E (12 CFR 1005). The app repays itself by debiting your account. You have the right to revoke that authorization, and your bank must honor a stop payment on a preauthorized debit if you give notice at least three business days before the scheduled transfer. If the app debits more than you authorized, Regulation E’s error resolution rules require your bank to investigate. Blocking a debit does not cancel the debt, but it can stop an overdraft cascade.
Military Lending Act (10 U.S.C. 987, 32 CFR 232). Active-duty servicemembers and dependents are “covered borrowers,” and credit extended to them carries a 36% cap on the Military APR, which includes fees and subscription charges connected to the credit. The CFPB’s case against MoneyLion is built on this rule.
Truth in Lending Act and Regulation Z. Because most apps structure advances as non-recourse (they say they will not sue or send a debt collector if you do not repay), they argue no finance charge exists. If a product does charge a fee that is mandatory for the credit, TILA disclosures may be required, and Cash App Borrow, which is structured as a loan, does disclose on those terms.
Federal Trade Commission Act, Section 5. Deceptive advertising of advance limits and dark-pattern cancellation flows are what drove the Brigit, Cleo, FloatMe and Dave actions. The Restore Online Shoppers’ Confidence Act covers the subscription side.
Fair Credit Reporting Act. Apps generally do not furnish payment data to the credit bureaus, so an advance does not help or hurt your score. Apps that bundle a “credit builder” product are furnishing data on that product, not the advance.
Fair Debt Collection Practices Act. Most apps state they will not refer unpaid advances to collections. If one does, the collector is bound by the FDCPA’s limits on calls, threats and disclosures to third parties.
State small loan and usury laws. In states like Connecticut, and increasingly California, tips and express fees are counted as charges on a loan. That means state rate caps and licensing can apply.
Where to complain: the CFPB complaint portal for problems with debits, fees or disclosures; the FTC’s ReportFraud site for deceptive advertising and cancellation traps; your state financial regulator for licensing questions.
How to check a cash advance app before you connect your bank
Find the fee page on the app’s website and write down the subscription, express fee and tip default.
Compute the APR: fee divided by amount, times 365, divided by days to payday.
Search the company name on the CFPB complaint database and read the most recent 20 complaints.
Check your state regulator’s license or registration lookup, and NMLS Consumer Access if the product is a loan.
Confirm there is a free delivery option and that the tip can be set to $0.
Read the repayment section: which account is debited, on what date, and how to revoke authorization.
How to choose the right cash advance app for you
Start with where your paycheck already goes. If it lands at Chime, Varo or Current, their in-house advances are cheaper than anything that requires linking an outside bank. Switching banks just to get a cheaper advance is rarely worth it; the savings on a $200 advance are a few dollars, and the hassle of moving direct deposit and autopays is real.
If you want to keep your current bank, EarnIn is the lowest-cost outside app provided you accept the one-to-three-day wait and set the tip to zero. MoneyLion is the next cheapest for instant delivery on larger amounts. Dave makes sense only when you need $400 or more quickly, because the $15 cap makes large advances cheaper than its small ones.
Avoid any subscription-based app unless you will use the other features every month. Paying $9.99 or $14.99 for budgeting alerts you could get free from your bank is the most common way these apps quietly cost more than a payday advance from a storefront on a per-dollar basis.
Think about repayment before speed. A next-day free delivery with a payday that falls on a Friday is fine. An instant delivery that triggers a debit the day before rent is a problem. Line the advance date, the debit date and your other automatic payments up on a calendar before you accept.
Things to consider before using a cash advance app
Overdrafts at your own bank. The app debits the full advance on payday whether or not your balance covers it. If the deposit is late or smaller than expected, your bank’s overdraft fee, often $35, lands on top of the app fee. Several apps claim to check your balance first and delay the debit if it would overdraw you, but that is a courtesy in the terms, not a right.
The repeat cycle. CFPB data shows the typical user does not take one advance. They take two dozen or more a year, and each one shortens the next paycheck by the amount advanced plus fees. The arithmetic only ends when you skip a cycle, which means living on a short check once. Budgeting for that skipped cycle is the real exit plan.
Data access. Connecting the app means granting continuous read access to your bank transactions. Some apps, Klover most openly, monetize that data. Read the privacy policy for the words “sell,” “share” and “affiliates,” and revoke the connection in your bank’s or Plaid’s settings when you stop using the app.
Subscription cancellation. Cancel inside the app, not just by deleting it. The FTC’s cases against Brigit and Cleo centered on users who thought they had canceled and kept getting charged.
Non-recourse is not free money. Most apps say they will not sue or send a debt collector. They will, however, close your account, keep retrying the debit for weeks, and block future advances. Unpaid balances do not affect your credit score, but they do affect your relationship with the one app that was helping.
What it is not. A cash advance app is not a payday loan, which carries stated interest, a signed loan agreement and, in states that allow it, APRs around 400%. It is also not a loan you can build credit with. Treat it as a bridge for a single short gap, priced in the triple digits for anything beyond the free tier, and look at the cheaper options table before you reach for it twice.
FAQ
What are the best cash advance apps right now?
By total cost, Chime MyPay and Varo Advance are cheapest for people who already bank there, and EarnIn is cheapest for anyone who wants to keep their existing bank and can wait one to three business days. MoneyLion and Dave offer the largest limits for outside-bank users at a higher price. Subscription apps like Brigit and Empower cost the most per dollar borrowed.
Which cash advance app gives you the most money?
EarnIn’s published ceiling is $750 per pay period, and MoneyLion advertises up to $1,000 for users who move direct deposit to RoarMoney. In practice new users on every app start between $25 and $100, and the ceiling only applies after months of consistent deposits and on-time repayment.
Do cash advance apps check your credit?
Not with a hard inquiry. They read your linked bank account for deposit patterns and balance behavior instead. Because they do not check credit, they also do not report to the credit bureaus, so repaying on time will not raise your score.
Are cash advance apps cheaper than a payday loan?
Usually, but not always. A payday loan at $15 per $100 over two weeks is about a 391% APR. A free, slow-delivery advance from EarnIn or Chime is 0%. A subscription app used once a month for a small advance can top 500%, which is worse than the storefront product it is marketed against.
What happens if I cannot repay a cash advance app?
Most apps state they will not charge late fees, sue or send the debt to a collector. They will keep attempting the debit, which can overdraw your bank account, and they will suspend your access. Cash App Borrow is the exception on this list: it is a loan and adds a 1.25% weekly finance charge on late balances.
Can I stop a cash advance app from debiting my account?
Yes. Under Regulation E you can revoke a preauthorized debit by notifying your bank at least three business days before the scheduled transfer, and you can revoke the app’s authorization in its settings. Stopping the debit does not erase what you owe, but it can prevent an overdraft fee while you sort out the timing.
Is a cash advance app available in every state?
No. Connecticut brought these products under its small loan law in 2023 and several apps limited service there. Nevada, Missouri, Wisconsin, Kansas, South Carolina, California and Maryland each require licensing or registration under different rules, and more states added laws in 2025. Check the app’s availability page and your state regulator before assuming you qualify.
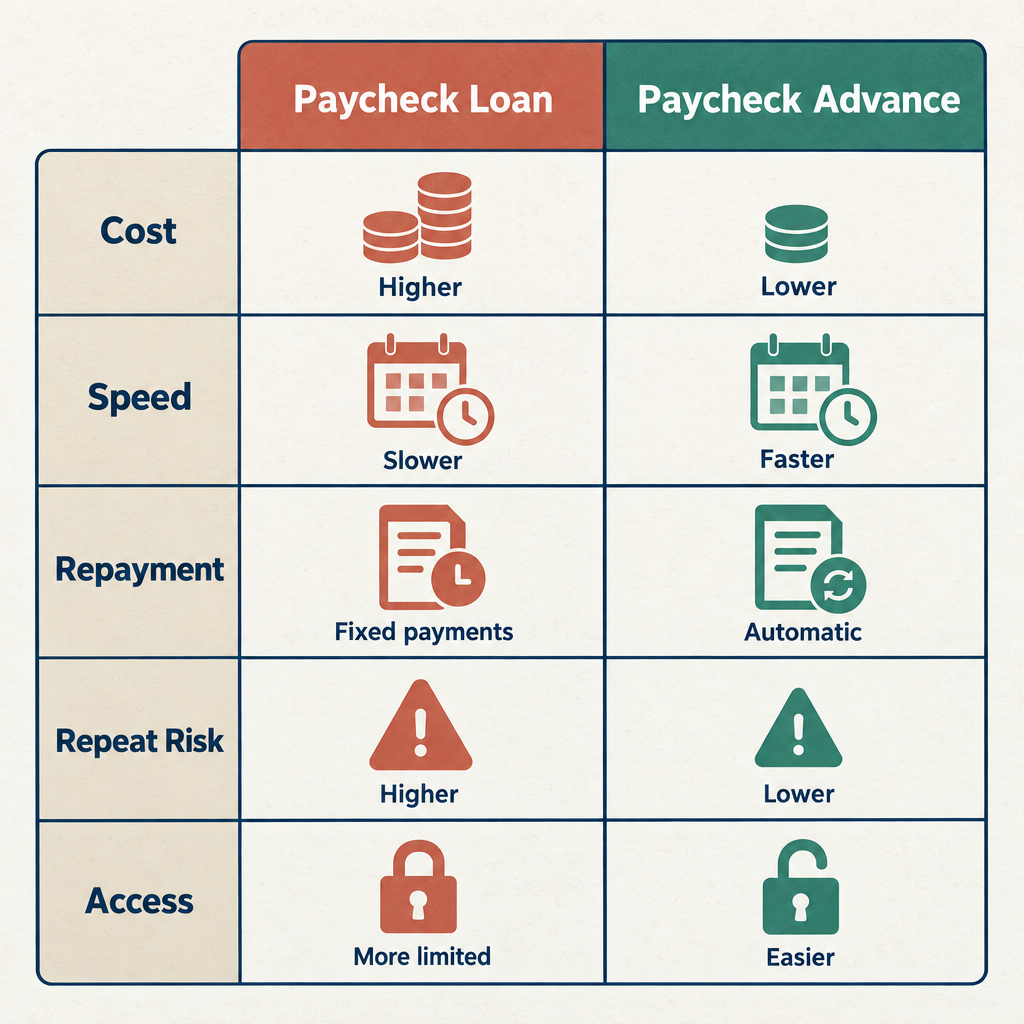
A paycheck loan is a short-term, high-cost loan repaid from your next pay, usually at $10 to $30 per $100 borrowed, which works out to roughly 400% APR. A paycheck advance lets you access wages you have already earned, sometimes free through an employer and sometimes for a few dollars through an app. The products look alike on a phone screen, but the gap in what you repay can be several hundred dollars.
Paycheck loan cost$10 to $30 per $100
Typical APRaround 400%
Loan size$100 to $1,000
Paycheck advance cost$0 to about $6
Advance sizeusually $50 to $750
As of2026
Before you borrow
The biggest risk with a paycheck loan is paying the fee again two weeks later because the lump sum left you short. CFPB research found that four out of five payday loans are rolled over or followed by a new loan within 14 days, so a $60 fee becomes $240 or more before the principal moves.
Two products hide behind one search term
People type “paycheck loan” and mean two different things.
The first is a payday loan with a friendlier label. You borrow a few hundred dollars from a licensed lender, in a store or online, and agree to repay it plus a flat fee on your next payday. The lender takes a postdated check or an authorization to debit your bank account. Marketing calls this a cash advance on paycheck, a pay cash advance, or a “payday advance” depending on the state.
The second is earned wage access, usually sold as a paycheck advance, advance pay or “paycheck advance now.” Your employer or an app lets you pull part of the wages you have already worked for before payday arrives. The money is then deducted from your paycheck or your bank account when the real payroll lands.
The difference matters because one is credit at triple-digit rates and the other is, at best, your own money a few days early. At worst, the app version drifts toward payday pricing once you add express fees and tips.
How a paycheck loan works
A storefront or online paycheck loan runs on a short cycle. You show proof of income, a checking account and ID. Most lenders do not pull a traditional FICO score. They run a soft check, use alternative data such as bank transaction history, or check specialty databases like Clarity or FactorTrust. That is what sits behind “no credit check” advertising. Approval is still a decision based on your income and your bank activity, and the price reflects the lender’s risk.
The term is usually 14 to 31 days. On the due date the lender deposits your check or debits your account for the full amount plus the fee. If you cannot cover it, many states allow a rollover or a back-to-back loan, and each one carries a fresh fee.
Applying for a paycheck loan online adds two issues. Some online lenders are not licensed in your state, and tribal or offshore lenders often charge far more than state law allows a local store to charge. Others are lead generators that sell your application to multiple companies, which is why a single search can trigger weeks of calls and texts. Marketing phrases like “urgent loans guaranteed approval” are a red flag rather than a feature, since no licensed lender can lawfully promise approval before it reviews an application.
If you want the full mechanics, our “payday loan” explainer walks through the fee structure state by state. The lending product is the same whatever the ad calls it.
How a paycheck advance works
Earned wage access comes in two forms, and they are priced very differently.
Employer-integrated advances
Your employer contracts with a provider that connects to its payroll and timekeeping. You can see earned-but-unpaid wages and transfer some of them, often up to 50% of what you have accrued. On payday the provider is repaid directly out of your check. Many employers pay the provider’s fee as a benefit, so a standard transfer costs you nothing. Instant transfers to a debit card may cost a dollar or two.
Direct-to-consumer apps
Apps that work without your employer connect to your bank account instead. They estimate your earnings from deposit history and advance a set amount, commonly $50 to $500, then debit your account on your next payday. They do not charge interest. They make money three ways: a monthly subscription, an “instant” or “lightning” transfer fee for same-day money, and an optional tip. A standard transfer that takes one to three business days is usually free.
The CFPB’s 2024 data spotlight on employer-partnered earned wage access found the typical worker made around 27 advances a year, and that once fees were counted the cost worked out to an APR above 100%. That is far cheaper than a paycheck loan, but it is not free money, and the pattern of repeat use looks a lot like payday borrowing.
What each option really costs
The honest way to compare a flat fee with an APR is to turn the fee into an APR. Divide the fee by the amount you received, multiply by 365, then divide by the number of days you had the money. A $60 fee on $400 for 14 days is 15%, times 365 divided by 14, which is 391% APR.
Product
Amount
Fee or APR
Term
Total repaid
APR equivalent
Paycheck loan, paid on time
$400
$15 per $100 ($60)
14 days
$460
391%
Paycheck loan, rolled over 3 times
$400
$60 x 4 ($240)
56 days
$640
391%
App advance, instant transfer
$100
$4.99 express fee
10 days
$104.99
182%
App advance, standard transfer
$100
$0
10 days
$100.00
0%
Employer advance, employer pays fee
$200
$0
7 days
$200.00
0%
Credit union PAL I
$500
28% APR, $20 app fee
6 months
about $562
28% plus fee
Credit card cash advance
$400
5% fee ($20) plus about 30% APR
30 days
about $430
roughly 90%
Two things jump out. The paycheck loan is the only row where the fee restarts every two weeks without reducing what you owe. And the app advance can swing from 0% to triple digits depending on whether you tap the instant button. A $5.99 express fee on a $100 advance repaid in seven days is a 312% APR, which is payday-loan territory.
Side-by-side on the criteria that matter
We compare on total cost, fees, transparency, licensing, complaint record and borrower protections, not on speed or convenience.
Criterion
Paycheck loan
Employer advance
App advance
Credit union PAL
Typical total cost
Highest
Lowest
Low to moderate
Low
Cost repeats if you are short
Yes, every term
No new fee
Only express fees
No, fixed schedule
APR disclosed up front
Required under Regulation Z
Usually not
Usually not
Required
Licensing
State lender license
Varies by state
Varies by state
Federal or state charter
Builds credit
No
No
No
Often yes
Can overdraft your account
Yes, via ACH
Rarely, payroll deduction
Yes, via ACH
No
Covered by Regulation E
Yes
Partly
Yes
Yes
Paycheck loan from a licensed lender
Strengths: the price is disclosed as an APR under the Truth in Lending Act, the lender holds a state license you can verify, and the amount can reach $1,000 in states that allow it.
Weaknesses: the cost is extreme for a two-week loan, repayment is a single lump sum, and the business model relies on repeat borrowing. The CFPB’s 2017 payday rule, whose payment provisions took effect March 30, 2025, exists because lenders were hammering empty accounts with repeated debits.
Employer-integrated paycheck advance
Strengths: often free, repaid from payroll so it cannot overdraft your bank account, and the advance is capped at wages you have actually earned.
Weaknesses: only available if your employer offers it, your boss’s payroll vendor knows how often you use it, and repayment shrinks your next check at the moment you may need it most.
Direct-to-consumer paycheck advance app
Strengths: no employer involvement, standard transfers are usually free, and the amounts are small enough that the debt rarely snowballs.
Weaknesses: the real price is buried in subscriptions, express fees and suggested tips, the app’s debit can bounce and trigger overdraft fees at your bank, and many apps advertise an amount you will not qualify for until you have months of deposit history. Because most apps do not call the product a loan, they also do not give you a standardized APR, so comparing two apps takes real arithmetic.
Credit union payday alternative loan
Strengths: the NCUA caps PAL I loans at 28% APR with an application fee of no more than $20, amounts run $200 to $1,000, and terms run one to six months. PAL II allows up to $2,000 over up to 12 months with no waiting period. Payments report to credit bureaus at many credit unions.
Weaknesses: you need to join a credit union, PAL I requires one month of membership first, and funding is rarely same-day.
How to choose between them
Start with the question of whether you have already earned the money. If payday is five days away and you have worked the hours, a paycheck advance that costs nothing with a standard transfer is the cheapest route by a wide margin. Ask your HR or payroll department first, because an employer program is almost always cheaper than an app.
If the gap is bigger than one paycheck can cover, an advance just moves the hole forward a week. That is where people slide into a paycheck loan. Before you do, price a credit union PAL, a hardship plan with the bill you are trying to pay, or a credit card cash advance. All three cost a fraction of a payday product even when the credit card rate looks ugly.
Pick a paycheck loan only if the alternatives are closed to you, you can repay the full amount on the first due date without borrowing again, and the lender is licensed in your state. If any of those three is uncertain, the loan will likely cost more than the problem it solves.
Cheaper options first
Ask your employer about earned wage access or a payroll advance with no fee.
Call your utility, landlord or medical provider and ask for a payment plan before borrowing.
Price a credit union payday alternative loan, capped at 28% APR by the NCUA.
Dial 211 for local emergency assistance with rent, utilities and food.
Where paycheck loans are banned or capped
Paycheck loans are legal at triple-digit rates in a bit more than half the states. Roughly 20 states plus the District of Columbia either ban the product or cap small-loan rates at or around 36%, which makes classic two-week lending unprofitable. That group includes New York, New Jersey, Pennsylvania, Massachusetts, Connecticut, Maryland, Georgia, North Carolina, West Virginia, Vermont, Arizona, Arkansas, Colorado, Montana, South Dakota, Nebraska, New Hampshire, Illinois and New Mexico.
Where the loans are legal, state law sets the terms. California caps the check at $300 and the fee at 15% of the face amount, so you receive $255 and repay $300 within 31 days, which the Department of Financial Protection and Innovation itself describes as a 460% APR on a two-week term. Texas allows “credit access businesses” to broker loans with fees that often push APRs above 500%. An online lender advertising nationwide availability is either licensed state by state or operating outside your state’s rules, and you should assume the second until you confirm the first.
Paycheck advances are regulated differently and the map is still being drawn. Nevada, Missouri, Wisconsin, Kansas and South Carolina have passed laws that register earned wage access providers and treat them as something other than lenders. Connecticut went the other way and treats the fees as loan charges subject to its small-loan rate cap. California requires providers to register with the DFPI. At the federal level, the CFPB proposed an interpretive rule in July 2024 saying most paycheck advance products are credit under the Truth in Lending Act, then withdrew that proposal in 2025. As of this writing there is no settled federal rule, so your protections depend heavily on your state.
Your rights with either product
The Truth in Lending Act and Regulation Z (12 CFR 1026) require a licensed paycheck lender to show you the finance charge and APR in writing before you sign. If a lender quotes only a “fee” and refuses to state an APR, that is a disclosure violation.
The Electronic Fund Transfer Act and Regulation E govern the bank debits that both lenders and apps rely on. You can revoke an ACH authorization, and you can place a stop payment with your bank at least three business days before a scheduled debit. A lender cannot condition a loan on your agreeing to repay by preauthorized electronic transfer.
Under the CFPB’s payday lending rule, after two consecutive failed withdrawal attempts a covered lender must get a new, specific authorization from you before trying again. That provision became enforceable March 30, 2025.
The Military Lending Act caps the Military Annual Percentage Rate at 36% for active-duty servicemembers and their dependents, which effectively bars them from standard paycheck loans. The Servicemembers Civil Relief Act separately caps pre-service debts at 6%.
If a paycheck loan goes unpaid and is sold, the Fair Debt Collection Practices Act controls what a “debt collector” can say and do. Collectors cannot threaten arrest over a bounced loan check, call before 8 a.m. or after 9 p.m., or discuss your debt with your employer. The Fair Credit Reporting Act gives you the right to dispute inaccurate collection entries.
Complaints go to the CFPB complaint portal, your state’s banking or financial regulator, and the FTC through ReportFraud. If you believe a lender was an outright fraud, file with the FBI’s IC3 as well.
How to check a lender before you borrow
Look the company up on NMLS Consumer Access and confirm a license for your state.
Check your state regulator’s own license search, since some states license payday lenders outside NMLS.
Search the CFPB complaint database for the company name and read the most recent complaints.
Confirm the APR and finance charge appear in writing before you sign anything.
Read the ACH authorization and note the exact date and amount of each scheduled debit.
FAQ
Is a paycheck loan the same as a payday loan?
Yes. “Paycheck loan,” “cash advance on paycheck” and “pay cash advance” are marketing names for the same short-term, single-payment loan regulated under state payday or deferred-deposit laws. The fee, term and legal protections are identical.
Is a paycheck advance a loan?
It depends on your state. Connecticut treats paycheck advance fees as loan charges. Nevada, Missouri, Wisconsin, Kansas and South Carolina regulate providers under separate earned wage access laws. Federally, the CFPB withdrew its 2024 proposal to treat them as credit, so there is no national answer yet.
Can I get a paycheck loan online with no credit check?
Online lenders usually skip the big three credit bureaus but still check your income, bank history and specialty databases. “No credit check” means a soft check or alternative data, not no review. Expect higher prices than a store in your state, and verify the license before sharing your bank login.
Do paycheck advances affect my credit score?
Almost never. Neither paycheck loans nor paycheck advance apps report on-time payments to Equifax, Experian or TransUnion. A defaulted paycheck loan can appear as a collection account, which does hurt your score. A credit union payday alternative loan is the only option in this comparison that routinely helps build credit.
What happens if the debit bounces?
Your bank may charge an overdraft or returned-item fee, often around $30, and the lender may add its own returned-payment fee where state law permits. A paycheck advance app typically will not charge a penalty but may cut off future advances. Under Regulation E and the CFPB payday rule, a lender needs fresh authorization after two consecutive failed attempts.
Which is cheaper for a $300 shortfall?
A free standard transfer through an employer program or app costs $0. A credit card cash advance costs roughly $15 in fees plus about $7 in interest for a month. A credit union PAL costs under $10 in interest for one month plus up to $20 to apply. A paycheck loan at $15 per $100 costs $45 for two weeks, and $90 if you roll it once.
A payday advance is a small, short-term loan, usually $100 to $500, that you repay in full from your next paycheck along with a flat fee. That fee typically runs $10 to $30 per $100 borrowed, which the CFPB notes works out to nearly 400% APR on a two-week loan. Before you sign, it helps to know exactly what the agreement commits you to and where the law stands behind you.
Typical fee$10 to $30 per $100
Typical APR300% to 600%
Loan size$100 to $500
Term2 to 4 weeks
Repaymentlump sum, from your bank account
As ofOctober 2026
What a payday advance actually is
The names change from storefront to storefront. Payday advance, cash advance, payday loan advance, advance payday loans, deferred deposit transaction, check advance. In almost every state they describe the same product: a lender gives you cash now, you give the lender a postdated check or permission to debit your bank account, and the lender cashes it on your payday.
Two things set this apart from other small loans. The whole balance comes due at once, and the price is a flat fee rather than interest that builds over months. That flat fee feels modest in dollars and looks enormous once you convert it to an annual rate, which the lender is legally required to do for you.
If you want a deeper comparison with installment loans, credit cards and cash advance apps, our “payday loan” explainer walks through each one. This page focuses on the contract itself.
How this differs from a pay advance or earned wage access
“Pay advance loans” and “advance credit” sometimes refer to something else: an employer or an app letting you draw wages you have already earned. Those products often charge a subscription or an optional tip instead of a loan fee, and the CFPB has said that mandatory fees and tips on these advances should be disclosed like finance charges. They are generally cheaper than a storefront payday advance, but they are not free, and they still leave you short on the next payday. Do not assume an app advance and a payday advance follow the same rules.
What you agree to when you sign
A payday advance agreement is short, but every line matters. Here is what you are committing to in a typical contract.
A finance charge and APR. Under the Truth in Lending Act and Regulation Z (12 CFR 1026), the lender must show you the dollar finance charge and the annual percentage rate before you are bound. If a storefront or website will not show the APR until after you commit, that is a problem.
Access to your bank account. You hand over a postdated check or sign an ACH authorization. That authorization is the lender’s main collection tool. Under the Electronic Fund Transfer Act and Regulation E (12 CFR 1005.10(e)), a lender cannot make repayment by preauthorized electronic transfer a condition of getting the loan, though in practice most borrowers sign one anyway.
A single due date. The full principal plus the fee comes out on your next payday. Nothing is spread out unless your state requires an extended payment plan.
Rollover or renewal terms. In states that allow it, you can pay only the fee on the due date and push the balance to the next pay period. Each rollover costs another full fee. The CFPB’s 2014 analysis of lender data found that four out of five payday loans were rolled over or followed by a new loan within 14 days.
Returned payment fees. If the debit bounces, the lender may charge its own NSF fee on top of your bank’s fee, and it may keep trying.
Arbitration and class action waivers. Most agreements require you to settle disputes through private arbitration and give up the right to join a class action. You can sometimes opt out within 30 to 60 days by sending a written notice; check the clause.
Collection and reporting language. The contract spells out what happens if you default, including referral to a “debt collector” and possible reporting to specialty credit bureaus.
What a payday advance really costs
The APR math is simple once you see it. Divide the fee by the amount borrowed, divide by the number of days in the term, then multiply by 365. On a $300 loan with a $45 fee for 14 days: $45 ÷ $300 = 0.15; 0.15 ÷ 14 × 365 = 3.91, or 391% APR.
Scenario
Amount borrowed
Fee
Term
Total repaid
APR
Typical two-week advance
$300
$45 ($15 per $100)
14 days
$345
391%
Higher-fee state
$500
$100 ($20 per $100)
14 days
$600
521%
California maximum
$255
$45 (15% of $300 face)
14 days
$300
460%
$300 rolled over three times
$300
$45 × 4 = $180
56 days
$480
391%
The last row is where most of the damage happens. Pew Charitable Trusts research found the average borrower takes out about eight loans of roughly $375 a year and pays around $520 in fees, spending about five months of the year in payday debt. The product is marketed as a two-week fix. The data says it rarely works that way.
Before you borrow
The biggest risk is not the first fee. It is paying that fee again every two weeks because the lump-sum repayment leaves you short, until the fees exceed what you originally borrowed.
Where payday advances are legal, capped or banned
This is not a nationwide product with one price. State law decides whether a payday advance exists at all and what it can cost.
Banned or capped at 36% APR or lower: Arizona, Arkansas, Colorado, Connecticut, Georgia, Illinois, Maryland, Massachusetts, Montana, Nebraska, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, South Dakota, Vermont, West Virginia and the District of Columbia. In several of these states, general “usury laws” make the typical payday fee a crime for the lender.
Allowed with limits: California caps loans at $300 face value, fees at 15% and terms at 31 days under the California Deferred Deposit Transaction Law, overseen by the Department of Financial Protection and Innovation. Florida caps loans at $500, fees at 10% plus a $5 verification fee, bans rollovers and requires a 24-hour cooling-off period between loans, tracked in a statewide database.
Lightly regulated: Texas lets “credit access businesses” arrange loans with no meaningful cap on fees, so APRs above 500% are routine there.
If an online lender offers you a payday advance in a state that bans them, it is either unlicensed or operating under a tribal or out-of-state claim that your state regulator may not recognize. Either way, you lose most of your protections.
Who a payday advance can make sense for
We would be lying if we said never. A payday advance can be rational when all of the following are true: the amount is small, you have a specific one-time gap, your next paycheck covers the full repayment plus your normal bills, and every cheaper option on the list below is genuinely unavailable. The avoided cost also has to be real. Paying $45 to avoid a $35 overdraft fee is not a win. Paying $45 to avoid a $150 utility reconnection fee or a car repossession might be.
If you are reading this because of a sudden expense, our “loans emergency” guide covers the full range of options by speed and cost.
Cheaper options first
A credit union payday alternative loan: $200 to $2,000, APR capped at 28% by NCUA rules.
Your employer’s advance program or a no-fee app advance.
A hardship plan from the biller itself, or help from 211, LIHEAP or a nonprofit credit counselor.
Your rights with a payday advance
Federal law gives you a floor of protection, and some states add more.
Disclosure. The Truth in Lending Act requires the APR and finance charge in writing before you sign. Missing or wrong disclosures give you grounds for a complaint.
Limits on repeated debits. The CFPB’s Payday Lending Rule (12 CFR 1041), with payment provisions in effect since March 30, 2025, bars a lender from making a third consecutive attempt to debit your account after two failed attempts unless you give new authorization. The lender must also notify you before an unusual withdrawal.
Revoking authorization. Under Regulation E, you can revoke an ACH authorization by notifying the lender and your bank. That stops the debits. It does not erase the debt.
Military borrowers. The Military Lending Act (32 CFR 232) caps the total cost of consumer credit at a 36% Military APR for active-duty service members and their dependents, which effectively shuts them out of conventional payday advances.
Collection. The Fair Debt Collection Practices Act covers third-party collectors, not the original lender. A collector cannot threaten you with arrest, call before 8 a.m. or after 9 p.m., or discuss your debt with your employer. A bounced check on a payday advance is a civil matter in nearly every state, despite what some collectors imply.
Extended payment plans. Florida, Washington and several other states require lenders to offer a no-cost extended plan if you cannot repay. Members of the Community Financial Services Association also promise one. Ask before the due date, not after.
How to check a payday lender
Search the company name in NMLS Consumer Access to see its state licenses.
Confirm the license on your own state regulator’s lookup, such as California’s DFPI.
Read the lender’s complaints in the CFPB consumer complaint database.
Make sure the APR appears on the agreement before you sign anything.
Report problems to the CFPB complaint portal, your state regulator or FTC ReportFraud.
FAQ
Is a payday advance the same as a payday loan?
Yes. Lenders use payday advance, cash advance, deferred deposit and check advance interchangeably for the same two-week lump-sum loan. The word “advance” does not change the legal product or the fee.
Will a payday advance help my credit score?
Almost never. Most payday lenders do not report on-time payments to Equifax, Experian or TransUnion, so there is no upside. Defaults can be sold to collectors who do report, so the downside is real.
What happens if I cannot repay on the due date?
Ask about an extended payment plan first if your state or the lender offers one. If the debit bounces, expect NSF fees from both the lender and your bank. After two failed attempts, the lender needs fresh authorization to keep trying. Do not take a second advance to cover the first.
Can I cancel a payday advance after signing?
Many states give you until the end of the next business day to return the money and cancel at no cost. California and Texas both require this rescission right. Check your agreement for the exact deadline and whether cancellation must be in writing.
Are online payday advances safe?
Only if the lender is licensed in your state. Unlicensed online lenders are the source of most complaints about repeated unauthorized debits and threats of arrest. Verify the license before you share your bank details, not after.
Search “urgent loans for bad credit guaranteed approval” and you get pages promising cash in minutes with no questions asked. No licensed lender in the United States can actually guarantee approval, so the phrase tells you more about the advertiser than the loan. This guide explains what those ads really mean, what a same-day loan costs when your credit is poor, and how to get money quickly without paying 400% for it.
Typical payday APR391% for a 14-day loan
Bad-credit installment APRroughly 100% to 200%
Credit union PAL APR cap28% plus $20 fee
"Guaranteed approval"not offered by any licensed lender
Payday lending banned or capped at 36%about 20 states plus DC
As ofOctober 2026
Before you borrow
The fastest loans for bad credit are almost always the most expensive, and CFPB research found that about four in five payday loans are rolled over or followed by another loan within two weeks. An urgent loan can turn one bad month into a year of fees.
What “guaranteed approval” really means
Every lender has to decide if you can repay. That is not just caution, it is how they stay in business. A company that says yes to everyone either has a hidden catch or is not a lender at all.
Here is how the common phrases translate once you read the actual disclosures.
What the ad says
What usually happens
Guaranteed approval
A soft pre-screen, then a real review. Many applicants still get declined.
No credit check
No FICO pull, but a check through Clarity Services (Experian) or FactorTrust (TransUnion), which track payday and short-term loans.
Bad credit OK
True, but priced for it: APRs from about 100% to 400% or more.
Instant decision
Automated underwriting in minutes. Funding is a separate step.
Same-day cash
Only if you apply before a cutoff, pass verification, and choose an instant debit card deposit.
No cosigner, no collateral
Standard for payday and most online installment loans. The lender charges more instead of asking for a guarantor.
The Federal Trade Commission has said for years that no legitimate lender promises approval before seeing an application. Worse, the FTC’s Telemarketing Sales Rule (16 CFR 310.4) makes it illegal to charge an upfront fee for a promised loan. If someone says your loan is approved and you just need to pay a “processing” or “insurance” fee first, that is the signature of a loan scam, not a loan.
How urgent bad-credit loans actually work
With a FICO score under 580, which Experian labels “poor,” you are mostly looking at three kinds of credit that will take you.
Payday loans. A single-payment loan, usually $100 to $500, due on your next payday. The lender takes a post-dated check or authorization to debit your bank account. Fees are quoted per $100 borrowed, not as an interest rate, which hides how expensive they are. Our separate piece on what a “payday loan” is covers the mechanics in more detail.
Online installment loans for bad credit. Larger amounts, often $500 to $5,000, repaid in fixed payments over 3 to 24 months. These lenders skip FICO and use bank data and income. The trade-off shows up in the APR, which lender disclosures commonly put well into the triple digits, and higher in states with no rate cap.
Cash advance apps. Apps like EarnIn, Dave, Brigit and Chime’s MyPay front you part of your paycheck, typically $20 to $500 depending on your income and history, with EarnIn going as high as $1,000 per pay period subject to a daily cap. There is no interest in the legal sense, but optional “instant” fees and monthly subscriptions add up. A $100 advance with a $5 express fee repaid in 14 days works out to an APR of about 130% once you do the math the same way a lender would.
None of these products run a traditional hard credit pull in most cases. That is why they can approve you quickly. It is also why they cost so much: the lender expects a chunk of borrowers to default and prices everyone accordingly.
What a $500 urgent loan costs
The table below uses fee structures that appear in actual lender disclosures and the NCUA’s rules for credit unions. Your numbers will vary by state and lender, so always read the Truth in Lending disclosure before you sign.
Option
Amount
Cost
Term
Total repaid
APR
Storefront or online payday loan
$500
$15 per $100 ($75)
14 days
$575
391%
Same payday loan rolled over twice
$500
$225 in fees
6 weeks
$725
391% each time
Bad-credit installment loan
$500
160% APR
6 months
about $757
160%
Credit card cash advance
$500
5% fee ($25) plus 29.99% APR
30 days
about $538
roughly 90% all-in for one month
Cash advance app
$100
$4.99 express fee
14 days
$104.99
about 130%
Credit union Payday Alternative Loan
$500
28% APR plus $20 fee
6 months
about $562
28% plus fee
How the payday APR math works. A $15 fee on $100 is 15% for 14 days. A year has about 26 two-week periods, so 15% times 26 comes to 391%. That is the number Regulation Z requires the lender to print on your contract, even though the counter clerk will only mention “$15 per hundred.”
The rollover row matters most. If you cannot repay $575 in two weeks, many lenders let you pay the $75 fee and extend. Do that twice and you have paid $150 in rollover fees on top of the original $75, $225 in all, to borrow $500 and still owe the full $500. The CFPB found that most payday revenue comes from borrowers stuck in exactly this loop.
How to get an urgent loan with bad credit (step by step)
This is a real process, and the order matters. Checking cheaper sources first takes about an hour and can save hundreds of dollars.
What you need before you start
Government ID and Social Security number
Proof of income: recent pay stubs, benefit letters, or two months of bank statements
An active checking account with online access (most lenders verify it electronically)
Your actual credit score, pulled free from Experian, Equifax, or TransUnion at AnnualCreditReport.com, which the Fair Credit Reporting Act guarantees weekly at no charge
The exact amount you need and the date you can realistically repay it
How to borrow fast without overpaying
Call the biller first. Utilities, landlords, hospitals and even the IRS offer payment plans or hardship holds that cost nothing.
Check your employer. Many payroll providers now offer earned wage access with no fee if you accept standard ACH timing.
Call a local credit union and ask for a Payday Alternative Loan. If you are already a member, PAL II has no waiting period.
If you hold a credit card, compare its cash advance APR to the loan quotes. It is usually far cheaper than a payday loan.
Only then look at online bad-credit lenders. Pre-qualify with two or three, which uses a soft inquiry and does not hurt your score.
Verify each lender’s license on NMLS Consumer Access and your state regulator’s site before giving a Social Security number.
Read the TILA disclosure box. Compare the APR and total finance charge, not the monthly payment.
Choose instant debit card funding only if you truly need money today. Standard ACH is often free; instant transfers usually cost a few dollars.
Expected result
If you follow the order above, a typical outcome looks like this: a credit union PAL funded in one to two business days at 28% APR, or an app advance of a few hundred dollars within minutes for a $3 to $6 fee. If both fail and you take an online installment loan, expect approval in minutes, funds the same or next business day, and an APR well above 100%.
How fast is “same day”?
Funding speed depends on the payment rail, not on how urgent the ad sounds.
Funding method
Typical arrival
Usual cost
Catch
Push to debit card (RTP or Visa Direct)
Minutes
$0 to $6
Your bank must support instant deposits
Same-day ACH
Same business day
Usually free
Must be approved before the lender’s cutoff, often early afternoon Eastern
Standard ACH
1 to 3 business days
Free
Weekends and federal holidays do not count
In-store cash
Immediate
Free
Storefront payday only, and only in states that allow it
Apply on a Friday evening and “same day” quietly becomes Tuesday. If the money has to arrive today, the application needs to be finished, verified and approved by lunchtime.
Common mistakes that make an emergency loan worse
Borrowing more than the bill. Lenders often approve a higher amount than you asked for. Every extra $100 on a 391% APR loan costs $15 every two weeks.
Comparing payments instead of total cost. A $126 monthly payment sounds manageable. Six of them on a $500 loan means $757 out the door.
Applying everywhere at once. Soft pre-qualification is fine. Submitting full applications to five lenders can trigger five hard inquiries. FICO says each one typically costs fewer than five points, but they stack, and each one also shows future lenders you were shopping under stress.
Trusting reviews over licenses. Star ratings are easy to buy. A state license is not. Look up the company on NMLS Consumer Access and your state’s financial regulator before you trust a single review.
Paying anything upfront. Legitimate lenders deduct fees from the loan or add them to the balance. Anyone asking for a gift card, wire or crypto payment to “release” funds is running a scam.
Letting the lender keep debiting. Under 12 CFR 1041, the CFPB’s payday lending rule, a covered lender that fails to collect twice in a row must get fresh written authorization before trying again. Those payment provisions took effect March 30, 2025. If your account keeps getting hit and overdrafting, that may be a violation.
Where same-day bad-credit loans are available
Nothing about urgent loans is national. Your state decides which products exist and what they can charge.
State rule (as of October 2026)
Examples
What it means for you
Payday lending banned or capped at 36% APR or lower
Arizona, Arkansas, Colorado, Connecticut, Georgia, Illinois, Maryland, Massachusetts, Montana, Nebraska, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, South Dakota, Vermont, West Virginia, District of Columbia
Any “payday loan” offered to you online is likely unlicensed. Credit union and installment options still exist.
Payday allowed with fee and size limits
California ($300 max, fee up to 15% of face amount), Florida ($500 max, 10% fee plus $5 verification fee)
Legal but expensive; state database may block a second loan until the first is paid
Payday allowed with few limits
Texas (credit access business model, APRs often above 500%), Nevada, Utah, Idaho
The highest costs in the country; shop carefully and verify licensing
In a 36%-cap state, the online lender promising “urgent loans no credit check guaranteed approval” is often a tribal lender or an offshore operation that argues state law does not apply. Courts and state regulators have repeatedly disagreed. If the lender holds no license in your state, you have far fewer protections when something goes wrong, and your state attorney general’s office will want to hear about it.
Active-duty service members and their dependents are covered everywhere by the Military Lending Act (10 U.S.C. 987), which caps the Military Annual Percentage Rate at 36% on payday, installment and most other consumer credit. If a lender quotes you more, the loan is void from the start.
Cheaper options first
A credit union Payday Alternative Loan: PAL I from $200 to $1,000, or PAL II up to $2,000, both at a maximum 28% APR under NCUA rules.
Employer earned wage access or a no-fee app advance on standard ACH timing.
Nonprofit credit counseling through the National Foundation for Credit Counseling, and 211 for local emergency assistance with rent, utilities and food.
A closer look at Payday Alternative Loans
Federal credit unions can offer two PAL products under 12 CFR 701.21(c)(7). PAL I runs $200 to $1,000 over one to six months and requires one month of membership. PAL II goes up to $2,000 over one to twelve months with no waiting period. Both cap the APR at 28% and the application fee at $20, and neither allows rollovers. Credit unions generally pull credit, but many approve members with scores in the 500s because they look at your deposit history instead.
Joining usually costs $5 to $25 for a share account, and membership rules are broader than most people think: where you live, work, worship or attend school often qualifies you.
Your rights when you borrow
Fast lenders count on you not reading the fine print. These laws apply even when you are in a hurry.
Truth in Lending Act and Regulation Z (12 CFR 1026). Before you sign, the lender must disclose the APR, the finance charge in dollars, the amount financed and the total of payments. For online loans this appears as a boxed table before the signature screen. If a lender will not show it until after you commit, walk away.
Equal Credit Opportunity Act and Regulation B (12 CFR 1002). If you are denied, the lender must tell you within 30 days and give the specific reasons, or tell you how to request them. “Guaranteed approval” sites that go quiet after rejecting you are breaking this rule.
Fair Credit Reporting Act. You can get your report from each bureau free every week at AnnualCreditReport.com. If a denial was based on a credit report, the adverse action notice must name the bureau and the score used.
Electronic Fund Transfer Act (15 U.S.C. 1693k). A lender cannot make preauthorized recurring bank debits a condition of the loan. You can revoke an ACH authorization by notifying both the lender and your bank; the bank must honor a stop payment if you give it three business days’ notice.
Fair Debt Collection Practices Act. If you default and the account is sold, a “debt collector” cannot call before 8 a.m. or after 9 p.m., contact you at work after you say to stop, or threaten arrest. Payday default is a civil matter, not a crime, no matter what a collector says.
CFPB payday rule (12 CFR 1041). After two consecutive failed withdrawal attempts, a covered lender must stop and get new authorization in writing.
How to spot a fake lender
Approval before any application or income verification
Any fee requested before funding, especially by gift card, wire, Zelle or crypto
No license number, or a name that does not appear on NMLS Consumer Access
Only a Gmail or similar free email address, no physical address, no state disclosures page
Pressure to decide in minutes or “lose the offer”
A request for your online banking username and password rather than a read-only verification service
Report suspected scams to the FTC at ReportFraud.ftc.gov and to the FBI’s Internet Crime Complaint Center. Report licensed lenders that break the rules through the CFPB’s complaint portal; companies must respond, and the complaint becomes part of the public database that we and other researchers use.
Who an urgent bad-credit loan can make sense for
An expensive short-term loan is defensible in a narrow set of cases: the cost of not paying is higher than the loan’s cost, you have a specific date when money arrives, and the amount is small enough to clear in one payment. Avoiding a $35 overdraft plus a returned-payment fee, keeping a car on the road for a job, or stopping a utility shutoff can fit that description.
It does not make sense for ongoing shortfalls. If this month’s gap will exist next month too, a two-week loan at 391% guarantees the gap gets bigger. That situation calls for a nonprofit credit counselor, a hardship plan with your creditors, or a longer, cheaper loan from a credit union.
FAQ
Who will approve me for a loan when no one else will?
No lender approves everyone, and the ones who claim to are usually scams or lead generators selling your data. Your best realistic odds with poor credit are a credit union Payday Alternative Loan, a cash advance app that judges you on recurring deposits rather than score, or an online installment lender that uses bank data. Each will still check income and your account history.
How can I borrow money in an emergency with bad credit?
Start with sources that do not price by credit score: a payment plan from the biller, your employer’s earned wage access program, or a credit union PAL capped at 28% APR. Then consider a credit card cash advance if you have a card. Online bad-credit lenders should be the last stop because their APRs usually start above 100%.
How can I get an urgent loan with bad credit?
Gather ID, proof of income and bank login for verification, then pre-qualify with licensed lenders using soft inquiries. Apply before the lender’s same-day cutoff, usually early afternoon Eastern, and choose debit card funding if you need money within minutes. Confirm the APR on the Regulation Z disclosure before signing.
Can I borrow money instantly if I have poor credit?
You can get a decision in minutes, and money can hit a debit card within minutes if the lender supports instant transfers and you pay the express fee. True “instant” funding depends on your bank’s rails, the time of day and completed verification. Standard ACH takes one to three business days and is usually free.
Does a no-credit-check loan show up on my credit report?
Most payday and app advances are not reported to Equifax, Experian or TransUnion, so they do not help you build credit. Many are reported to specialty bureaus like Clarity Services and FactorTrust, and if you default and the debt goes to a collector, that collection can appear on your regular reports.
Is a guaranteed approval loan legal?
Lending itself is legal when licensed. Advertising “guaranteed approval” is deceptive marketing, and charging a fee before delivering a promised loan violates the FTC’s Telemarketing Sales Rule. Any lender who uses the phrase deserves extra scrutiny of its license and disclosures.
A payday loan is a small, short-term cash loan, usually $500 or less, that you repay in one lump sum on your next payday, typically within two to four weeks. Lenders charge a flat fee instead of monthly interest, and that fee works out to an annual percentage rate (APR) of roughly 400% on a typical two-week loan. Here is how the product works, what it costs next to other small loans, where it is legal, and which rules protect you if you borrow.
Typical loan size$100 to $500
Typical fee$10 to $30 per $100
Typical term2 to 4 weeks
Typical APR300% to 700%
Credit checkUsually none from big bureaus
As of2026
What a payday loan is
The Consumer Financial Protection Bureau (CFPB) describes a payday loan as a short-term, high-cost loan, generally for $500 or less, that is due on your next payday. The name comes from that timing. You borrow against the paycheck you have not received yet.
You will see the same product sold under a lot of labels: payday advance, cash advance, deferred deposit, check advance, or simply “pay day loan.” Storefront shops and online lenders both offer them. The mechanics are the same no matter what the sign says.
Two things set payday lending apart from a personal loan at a bank. First, you repay the whole balance at once, not in monthly installments. Second, the lender takes a post-dated check or an electronic authorization to pull the money from your bank account on the due date, so the lender gets paid before you decide what else to pay that week.
How a payday loan works
The process is simple, which is a large part of the appeal when rent is due Friday and payday is the following Monday.
You show proof of income (a pay stub or bank statements), a government ID and an open checking account. Most payday lenders do not pull your file from Equifax, Experian or TransUnion. Many do check specialty databases that track payday borrowing, and many states require the lender to check a state database so you cannot hold more loans than the law allows.
Once approved, you write a check for the loan amount plus the fee, dated for your next payday, or you sign an ACH authorization for the same amount. The lender hands you cash or deposits the money, often the same business day in a store and by the next business day online.
On the due date, the lender cashes the check or debits your account. If you cannot cover it, many states let you pay only the fee to “roll over” the loan for another pay period. That is where the trouble starts, and we come back to it below.
What a payday loan costs
Payday lenders quote fees per $100 borrowed, not an interest rate. The CFPB’s long-standing estimate is $10 to $30 for every $100, with $15 per $100 the most common price in states that allow it. Converting that to an APR shows why consumer regulators treat the product differently from a bank loan.
Here is the math in plain words. A $15 fee on $100 for 14 days is 15% for two weeks. There are about 26 two-week periods in a year, so 15% times 26 is 390%, which rounds to the 391% APR the CFPB cites once you use exact days.
Loan amount
Fee
Term
Total repaid
APR
$300
$45 ($15 per $100)
14 days
$345
391%
$500
$75 ($15 per $100)
14 days
$575
391%
$500
$150 ($30 per $100)
14 days
$650
782%
$500 rolled over 4 times
$375 in total fees
10 weeks
$875
391% each period
That last row is the one to study. Four rollovers on a $500 loan cost $375 in fees, and you still owe the original $500 at the end. The lender has collected 75% of the principal in ten weeks without reducing your balance by a dollar.
Before you borrow
The biggest risk is not the first fee. It is paying that fee again every two weeks because your next paycheck cannot absorb a lump-sum repayment, which is how a $300 loan quietly turns into $900 in fees over a year.
Under the Truth in Lending Act and Regulation Z (12 CFR 1026), every payday lender must disclose the finance charge in dollars and the APR in writing before you sign. If a lender will not show you an APR, that alone is reason to walk away.
How payday loans differ from other small loans
“Small loan” covers a wide price range. The table compares the main ways Americans borrow a few hundred dollars, using typical terms. Exact costs depend on your state and the lender’s own disclosure.
Product
Typical size
Typical cost
Repayment
Credit reported?
Payday loan
$100 to $500
$10 to $30 per $100, 300% to 700% APR
One lump sum in 2 to 4 weeks
Rarely, unless you default
High-cost installment loan
$500 to $5,000
100% to 300% APR in many states
Monthly payments over months or years
Often
Auto title loan
$100 to $5,000
About 25% per month, around 300% APR
Lump sum in 30 days; car is collateral
Rarely
Pawn loan
$20 to a few hundred
Monthly fee set by state, often 20% to 25%
Redeem item or forfeit it
Never
Credit card cash advance
Up to your cash limit
3% to 5% fee plus around 30% APR from day one
Minimum monthly payments
Yes
Cash advance app
$20 to $750
$0 to $15 in tips and express fees
Debited next payday
Usually not
Credit union payday alternative loan (PAL)
$200 to $2,000
28% APR cap, up to $20 application fee
1 to 12 monthly payments
Yes
Installment loans
An installment loan spreads repayment over fixed monthly payments. That structure is easier to manage than a lump sum, but many payday lenders also sell installment loans at triple-digit APRs. A longer term at a high rate can cost more in total dollars than a single payday loan paid off on time. Compare the total repaid, not the monthly payment.
Auto title loans
Title loans use your car as collateral. Costs run close to payday rates, and the lender can repossess the vehicle if you miss the balloon payment. Losing the car you drive to work turns a $500 problem into a lost job.
Pawn loans
Pawn shops lend against an item you leave with them. If you cannot repay, you lose the item and nothing else. There is no debt collection, no bank debit and no credit damage, which makes pawn one of the lower-risk high-cost options even though the fees are steep.
Credit card cash advances
A cash advance on a card you already hold charges a 3% to 5% fee and interest from the day you withdraw, with no grace period. On a $500 advance held for a month at a 30% APR, the interest comes to about $12, so you repay roughly $512. Expensive by credit card standards, far cheaper than a payday loan.
Cash advance apps
Apps such as EarnIn, Dave and Brigit advance small amounts against your next paycheck and ask for optional tips or charge express delivery fees. A $5 fee on a $100 advance due in two weeks is a 130% APR, and the CFPB has found that most users do pay something. Still, the dollar cost is usually a fraction of a payday loan, and the apps generally cannot send you to collections.
Payday alternative loans from credit unions
Federal credit unions can offer PALs under NCUA rules (12 CFR 701.21). A PAL I runs $200 to $1,000 for one to six months; a PAL II runs up to $2,000 for up to 12 months. Both cap the APR at 28% and the application fee at $20. A $500 PAL repaid over six months at the 28% cap costs about $69 in interest, roughly $570 total before the application fee, against $575 for a two-week payday loan that you may need to roll over.
Where payday loans are legal
Availability depends entirely on your state. Around 20 states and the District of Columbia either ban payday lending outright or cap small-loan rates near 36% APR, which makes the two-week model unprofitable. That group includes New York, New Jersey, Pennsylvania, North Carolina, Georgia, Massachusetts, Connecticut, Maryland, Arizona, Arkansas, West Virginia, Vermont and Montana, plus states that voted or legislated caps more recently: South Dakota (2016), Colorado (2018), Nebraska (2020), Illinois (2021), New Mexico (2023) and Minnesota (2023).
Other states allow the product with limits. California’s Deferred Deposit Transaction Law caps loans at $300 face value, fees at 15% of that amount (so $45 on a $300 check, leaving you $255 in cash), and terms at 31 days, with lenders licensed by the Department of Financial Protection and Innovation. Ohio’s 2018 Fairness in Lending Act restructured payday lending into installment loans with a minimum 91-day term. Texas lets “credit access businesses” arrange loans with fees state law does not cap, which is why Texas borrowers routinely see APRs above 500%.
An online lender advertising nationwide “cash loans payday advance” does not override your state’s law. If your state bans payday loans, a loan made to you there is generally void or unenforceable, and the lender is operating illegally. Tribal lenders and offshore sites claim exemptions; state attorneys general and the CFPB have repeatedly sued them.
Who a payday loan can make sense for
We will be direct: the list is short. A payday loan can be a defensible choice only when all of these are true. You face a specific cost of overdraft fees, a utility shutoff or a late fee that is larger than the payday fee. You are certain the next paycheck covers the full repayment plus your normal bills. You have already ruled out the cheaper options below. And you will borrow once, not roll over.
CFPB research from its own supervisory data found that more than 80% of payday loans are rolled over or followed by a new loan within 14 days. Most borrowers do not fit the one-time profile, however they feel at the counter.
Why rollovers trap borrowers
The lump-sum structure is the problem. Someone borrowing $500 because they came up $500 short this month is unlikely to have $575 spare two weeks later. Paying the $75 fee to defer feels manageable. Doing it ten times over the year costs $750 and leaves the $500 unpaid.
Because the lender holds a check or ACH authorization, a missed payment also triggers bank consequences. Each failed debit can cost you an overdraft or returned-item fee from your bank on top of the lender’s returned-check fee. The CFPB’s payday lending rule, in effect since March 30, 2025, now bars lenders from attempting a third withdrawal after two consecutive failures without fresh authorization from you.
Payday loans also do nothing for your credit score. Most lenders do not report on-time payments to the three big bureaus, so repaying faithfully builds nothing. Defaults, on the other hand, are often sold to collectors who do report.
Cheaper options first
Ask your employer about a paycheck advance, or use a cash advance app with the free standard delivery option.
Check a local credit union for a payday alternative loan at 28% APR or a small personal loan.
Call the biller: utilities, landlords and medical offices often set up payment plans at no cost.
Call 211 or a nonprofit credit counselor approved by the National Foundation for Credit Counseling before borrowing at triple digits.
Several large banks now offer small-dollar loans of $100 to $1,000 to existing checking customers, repaid over three or four months for a flat fee far below payday pricing. Your own bank’s app is worth checking before a payday store.
Your rights as a payday borrower
Federal and state law gives you more protection than most storefronts mention.
The Truth in Lending Act and Regulation Z require written disclosure of the APR, the finance charge, the amount financed and the total of payments before you sign. The APR must be stated as a yearly rate even for a 14-day loan.
The Military Lending Act (32 CFR 232) caps the Military Annual Percentage Rate at 36% for active-duty servicemembers and their dependents and bans mandatory arbitration in their loan contracts. A payday loan above 36% made to a covered borrower is void.
The Electronic Fund Transfer Act and Regulation E (12 CFR 1005.10(e)) say a lender cannot require repayment by preauthorized electronic transfer as a condition of the loan. You can also revoke an ACH authorization by notifying the lender and your bank, which stops future debits, though it does not cancel the debt.
The Fair Debt Collection Practices Act covers third-party collectors who buy or service defaulted payday debt. They cannot threaten arrest, call before 8 a.m. or after 9 p.m., or contact your employer about the debt. Bouncing a post-dated check to a payday lender is a civil matter, not a crime, in the vast majority of cases, and threatening criminal charges is a common illegal collection tactic.
The Fair Credit Reporting Act lets you dispute a payday collection account on your credit report if it is inaccurate or unverifiable.
State law adds limits on loan size, fees, rollovers and the number of loans you can hold, plus licensing requirements. In many states a loan from an unlicensed lender is unenforceable.
How to check a payday lender
Search the lender’s name on NMLS Consumer Access to see its license and the states it is licensed in.
Confirm the license with your state regulator’s lookup, such as California’s DFPI or Texas’s OCCC.
Read the Regulation Z disclosure and find the APR before you sign anything.
Search the CFPB complaint database for the lender’s complaint record.
Report illegal fees, threats or unlicensed lending to the CFPB complaint portal, FTC ReportFraud or your state attorney general.
FAQ
How much can you borrow with a payday loan?
Most payday loans are $500 or less, and state caps vary. California limits the check amount to $300. Some states allow up to $1,000, and a handful set no dollar cap at all.
Does a payday loan check your credit?
Most payday lenders skip the three major bureaus, which is why they advertise “no credit check.” They often use specialty databases such as Clarity or FactorTrust and state-mandated loan databases instead, so “no credit check” does not mean no screening.
Do payday loans build credit?
Almost never. On-time payments usually go unreported. Unpaid loans sold to collectors frequently do show up and hurt your score.
What happens if I cannot repay a payday loan?
The lender will try to cash your check or debit your account, which can trigger bank fees. Federal rules stop a third attempt after two consecutive failures. The debt may go to collections, and the lender can sue in civil court, but you cannot be jailed for owing a payday loan.
Can I cancel a payday loan after signing?
Many states give you until the end of the next business day to return the money fee-free. Check your contract and your state regulator’s rules for the exact window.
Are online payday loans different from storefront loans?
The product is the same, but online lenders are more likely to operate without a state license, charge higher fees and rely on ACH debits. Verifying the license on NMLS Consumer Access matters even more online.
What is the difference between a payday loan and a cash advance?
Many lenders use the terms interchangeably. A credit card cash advance, by contrast, is a separate product with a 3% to 5% fee plus card interest, usually far cheaper than a payday loan. Cash advance apps are a third category with small fees and no lender collection rights.