We do not lend money or arrange loans. Rates and rules change and differ by state, so check the lender’s own disclosure before you sign.
Search “urgent loans for bad credit guaranteed approval” and you get pages promising cash in minutes with no questions asked. No licensed lender in the United States can actually guarantee approval, so the phrase tells you more about the advertiser than the loan. This guide explains what those ads really mean, what a same-day loan costs when your credit is poor, and how to get money quickly without paying 400% for it.
Before you borrow
The fastest loans for bad credit are almost always the most expensive, and CFPB research found that about four in five payday loans are rolled over or followed by another loan within two weeks. An urgent loan can turn one bad month into a year of fees.
What “guaranteed approval” really means
Every lender has to decide if you can repay. That is not just caution, it is how they stay in business. A company that says yes to everyone either has a hidden catch or is not a lender at all.
Here is how the common phrases translate once you read the actual disclosures.
| What the ad says | What usually happens |
|---|---|
| Guaranteed approval | A soft pre-screen, then a real review. Many applicants still get declined. |
| No credit check | No FICO pull, but a check through Clarity Services (Experian) or FactorTrust (TransUnion), which track payday and short-term loans. |
| Bad credit OK | True, but priced for it: APRs from about 100% to 400% or more. |
| Instant decision | Automated underwriting in minutes. Funding is a separate step. |
| Same-day cash | Only if you apply before a cutoff, pass verification, and choose an instant debit card deposit. |
| No cosigner, no collateral | Standard for payday and most online installment loans. The lender charges more instead of asking for a guarantor. |
The Federal Trade Commission has said for years that no legitimate lender promises approval before seeing an application. Worse, the FTC’s Telemarketing Sales Rule (16 CFR 310.4) makes it illegal to charge an upfront fee for a promised loan. If someone says your loan is approved and you just need to pay a “processing” or “insurance” fee first, that is the signature of a loan scam, not a loan.
How urgent bad-credit loans actually work
With a FICO score under 580, which Experian labels “poor,” you are mostly looking at three kinds of credit that will take you.
Payday loans. A single-payment loan, usually $100 to $500, due on your next payday. The lender takes a post-dated check or authorization to debit your bank account. Fees are quoted per $100 borrowed, not as an interest rate, which hides how expensive they are. Our separate piece on what a “payday loan” is covers the mechanics in more detail.
Online installment loans for bad credit. Larger amounts, often $500 to $5,000, repaid in fixed payments over 3 to 24 months. These lenders skip FICO and use bank data and income. The trade-off shows up in the APR, which lender disclosures commonly put well into the triple digits, and higher in states with no rate cap.
Cash advance apps. Apps like EarnIn, Dave, Brigit and Chime’s MyPay front you part of your paycheck, typically $20 to $500 depending on your income and history, with EarnIn going as high as $1,000 per pay period subject to a daily cap. There is no interest in the legal sense, but optional “instant” fees and monthly subscriptions add up. A $100 advance with a $5 express fee repaid in 14 days works out to an APR of about 130% once you do the math the same way a lender would.
None of these products run a traditional hard credit pull in most cases. That is why they can approve you quickly. It is also why they cost so much: the lender expects a chunk of borrowers to default and prices everyone accordingly.
What a $500 urgent loan costs
The table below uses fee structures that appear in actual lender disclosures and the NCUA’s rules for credit unions. Your numbers will vary by state and lender, so always read the Truth in Lending disclosure before you sign.
| Option | Amount | Cost | Term | Total repaid | APR |
|---|---|---|---|---|---|
| Storefront or online payday loan | $500 | $15 per $100 ($75) | 14 days | $575 | 391% |
| Same payday loan rolled over twice | $500 | $225 in fees | 6 weeks | $725 | 391% each time |
| Bad-credit installment loan | $500 | 160% APR | 6 months | about $757 | 160% |
| Credit card cash advance | $500 | 5% fee ($25) plus 29.99% APR | 30 days | about $538 | roughly 90% all-in for one month |
| Cash advance app | $100 | $4.99 express fee | 14 days | $104.99 | about 130% |
| Credit union Payday Alternative Loan | $500 | 28% APR plus $20 fee | 6 months | about $562 | 28% plus fee |
How the payday APR math works. A $15 fee on $100 is 15% for 14 days. A year has about 26 two-week periods, so 15% times 26 comes to 391%. That is the number Regulation Z requires the lender to print on your contract, even though the counter clerk will only mention “$15 per hundred.”
The rollover row matters most. If you cannot repay $575 in two weeks, many lenders let you pay the $75 fee and extend. Do that twice and you have paid $150 in rollover fees on top of the original $75, $225 in all, to borrow $500 and still owe the full $500. The CFPB found that most payday revenue comes from borrowers stuck in exactly this loop.
How to get an urgent loan with bad credit (step by step)
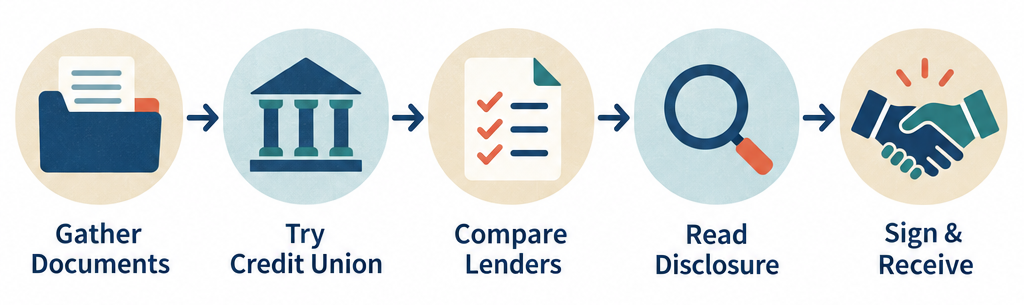
This is a real process, and the order matters. Checking cheaper sources first takes about an hour and can save hundreds of dollars.
What you need before you start
- Government ID and Social Security number
- Proof of income: recent pay stubs, benefit letters, or two months of bank statements
- An active checking account with online access (most lenders verify it electronically)
- Your actual credit score, pulled free from Experian, Equifax, or TransUnion at AnnualCreditReport.com, which the Fair Credit Reporting Act guarantees weekly at no charge
- The exact amount you need and the date you can realistically repay it
How to borrow fast without overpaying
- Call the biller first. Utilities, landlords, hospitals and even the IRS offer payment plans or hardship holds that cost nothing.
- Check your employer. Many payroll providers now offer earned wage access with no fee if you accept standard ACH timing.
- Call a local credit union and ask for a Payday Alternative Loan. If you are already a member, PAL II has no waiting period.
- If you hold a credit card, compare its cash advance APR to the loan quotes. It is usually far cheaper than a payday loan.
- Only then look at online bad-credit lenders. Pre-qualify with two or three, which uses a soft inquiry and does not hurt your score.
- Verify each lender’s license on NMLS Consumer Access and your state regulator’s site before giving a Social Security number.
- Read the TILA disclosure box. Compare the APR and total finance charge, not the monthly payment.
- Choose instant debit card funding only if you truly need money today. Standard ACH is often free; instant transfers usually cost a few dollars.
Expected result
If you follow the order above, a typical outcome looks like this: a credit union PAL funded in one to two business days at 28% APR, or an app advance of a few hundred dollars within minutes for a $3 to $6 fee. If both fail and you take an online installment loan, expect approval in minutes, funds the same or next business day, and an APR well above 100%.
How fast is “same day”?
Funding speed depends on the payment rail, not on how urgent the ad sounds.
| Funding method | Typical arrival | Usual cost | Catch |
|---|---|---|---|
| Push to debit card (RTP or Visa Direct) | Minutes | $0 to $6 | Your bank must support instant deposits |
| Same-day ACH | Same business day | Usually free | Must be approved before the lender’s cutoff, often early afternoon Eastern |
| Standard ACH | 1 to 3 business days | Free | Weekends and federal holidays do not count |
| In-store cash | Immediate | Free | Storefront payday only, and only in states that allow it |
Apply on a Friday evening and “same day” quietly becomes Tuesday. If the money has to arrive today, the application needs to be finished, verified and approved by lunchtime.
Common mistakes that make an emergency loan worse
Borrowing more than the bill. Lenders often approve a higher amount than you asked for. Every extra $100 on a 391% APR loan costs $15 every two weeks.
Comparing payments instead of total cost. A $126 monthly payment sounds manageable. Six of them on a $500 loan means $757 out the door.
Applying everywhere at once. Soft pre-qualification is fine. Submitting full applications to five lenders can trigger five hard inquiries. FICO says each one typically costs fewer than five points, but they stack, and each one also shows future lenders you were shopping under stress.
Trusting reviews over licenses. Star ratings are easy to buy. A state license is not. Look up the company on NMLS Consumer Access and your state’s financial regulator before you trust a single review.
Paying anything upfront. Legitimate lenders deduct fees from the loan or add them to the balance. Anyone asking for a gift card, wire or crypto payment to “release” funds is running a scam.
Letting the lender keep debiting. Under 12 CFR 1041, the CFPB’s payday lending rule, a covered lender that fails to collect twice in a row must get fresh written authorization before trying again. Those payment provisions took effect March 30, 2025. If your account keeps getting hit and overdrafting, that may be a violation.
Where same-day bad-credit loans are available
Nothing about urgent loans is national. Your state decides which products exist and what they can charge.
| State rule (as of October 2026) | Examples | What it means for you |
|---|---|---|
| Payday lending banned or capped at 36% APR or lower | Arizona, Arkansas, Colorado, Connecticut, Georgia, Illinois, Maryland, Massachusetts, Montana, Nebraska, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, South Dakota, Vermont, West Virginia, District of Columbia | Any “payday loan” offered to you online is likely unlicensed. Credit union and installment options still exist. |
| Payday allowed with fee and size limits | California ($300 max, fee up to 15% of face amount), Florida ($500 max, 10% fee plus $5 verification fee) | Legal but expensive; state database may block a second loan until the first is paid |
| Payday allowed with few limits | Texas (credit access business model, APRs often above 500%), Nevada, Utah, Idaho | The highest costs in the country; shop carefully and verify licensing |
In a 36%-cap state, the online lender promising “urgent loans no credit check guaranteed approval” is often a tribal lender or an offshore operation that argues state law does not apply. Courts and state regulators have repeatedly disagreed. If the lender holds no license in your state, you have far fewer protections when something goes wrong, and your state attorney general’s office will want to hear about it.
Active-duty service members and their dependents are covered everywhere by the Military Lending Act (10 U.S.C. 987), which caps the Military Annual Percentage Rate at 36% on payday, installment and most other consumer credit. If a lender quotes you more, the loan is void from the start.
Cheaper options first
A credit union Payday Alternative Loan: PAL I from $200 to $1,000, or PAL II up to $2,000, both at a maximum 28% APR under NCUA rules.
Employer earned wage access or a no-fee app advance on standard ACH timing.
Nonprofit credit counseling through the National Foundation for Credit Counseling, and 211 for local emergency assistance with rent, utilities and food.
A closer look at Payday Alternative Loans
Federal credit unions can offer two PAL products under 12 CFR 701.21(c)(7). PAL I runs $200 to $1,000 over one to six months and requires one month of membership. PAL II goes up to $2,000 over one to twelve months with no waiting period. Both cap the APR at 28% and the application fee at $20, and neither allows rollovers. Credit unions generally pull credit, but many approve members with scores in the 500s because they look at your deposit history instead.
Joining usually costs $5 to $25 for a share account, and membership rules are broader than most people think: where you live, work, worship or attend school often qualifies you.
Your rights when you borrow
Fast lenders count on you not reading the fine print. These laws apply even when you are in a hurry.
Truth in Lending Act and Regulation Z (12 CFR 1026). Before you sign, the lender must disclose the APR, the finance charge in dollars, the amount financed and the total of payments. For online loans this appears as a boxed table before the signature screen. If a lender will not show it until after you commit, walk away.
Equal Credit Opportunity Act and Regulation B (12 CFR 1002). If you are denied, the lender must tell you within 30 days and give the specific reasons, or tell you how to request them. “Guaranteed approval” sites that go quiet after rejecting you are breaking this rule.
Fair Credit Reporting Act. You can get your report from each bureau free every week at AnnualCreditReport.com. If a denial was based on a credit report, the adverse action notice must name the bureau and the score used.
Electronic Fund Transfer Act (15 U.S.C. 1693k). A lender cannot make preauthorized recurring bank debits a condition of the loan. You can revoke an ACH authorization by notifying both the lender and your bank; the bank must honor a stop payment if you give it three business days’ notice.
Fair Debt Collection Practices Act. If you default and the account is sold, a “debt collector” cannot call before 8 a.m. or after 9 p.m., contact you at work after you say to stop, or threaten arrest. Payday default is a civil matter, not a crime, no matter what a collector says.
CFPB payday rule (12 CFR 1041). After two consecutive failed withdrawal attempts, a covered lender must stop and get new authorization in writing.
How to spot a fake lender
- Approval before any application or income verification
- Any fee requested before funding, especially by gift card, wire, Zelle or crypto
- No license number, or a name that does not appear on NMLS Consumer Access
- Only a Gmail or similar free email address, no physical address, no state disclosures page
- Pressure to decide in minutes or “lose the offer”
- A request for your online banking username and password rather than a read-only verification service
Report suspected scams to the FTC at ReportFraud.ftc.gov and to the FBI’s Internet Crime Complaint Center. Report licensed lenders that break the rules through the CFPB’s complaint portal; companies must respond, and the complaint becomes part of the public database that we and other researchers use.
Who an urgent bad-credit loan can make sense for
An expensive short-term loan is defensible in a narrow set of cases: the cost of not paying is higher than the loan’s cost, you have a specific date when money arrives, and the amount is small enough to clear in one payment. Avoiding a $35 overdraft plus a returned-payment fee, keeping a car on the road for a job, or stopping a utility shutoff can fit that description.
It does not make sense for ongoing shortfalls. If this month’s gap will exist next month too, a two-week loan at 391% guarantees the gap gets bigger. That situation calls for a nonprofit credit counselor, a hardship plan with your creditors, or a longer, cheaper loan from a credit union.
FAQ
Who will approve me for a loan when no one else will?
No lender approves everyone, and the ones who claim to are usually scams or lead generators selling your data. Your best realistic odds with poor credit are a credit union Payday Alternative Loan, a cash advance app that judges you on recurring deposits rather than score, or an online installment lender that uses bank data. Each will still check income and your account history.
How can I borrow money in an emergency with bad credit?
Start with sources that do not price by credit score: a payment plan from the biller, your employer’s earned wage access program, or a credit union PAL capped at 28% APR. Then consider a credit card cash advance if you have a card. Online bad-credit lenders should be the last stop because their APRs usually start above 100%.
How can I get an urgent loan with bad credit?
Gather ID, proof of income and bank login for verification, then pre-qualify with licensed lenders using soft inquiries. Apply before the lender’s same-day cutoff, usually early afternoon Eastern, and choose debit card funding if you need money within minutes. Confirm the APR on the Regulation Z disclosure before signing.
Can I borrow money instantly if I have poor credit?
You can get a decision in minutes, and money can hit a debit card within minutes if the lender supports instant transfers and you pay the express fee. True “instant” funding depends on your bank’s rails, the time of day and completed verification. Standard ACH takes one to three business days and is usually free.
Does a no-credit-check loan show up on my credit report?
Most payday and app advances are not reported to Equifax, Experian or TransUnion, so they do not help you build credit. Many are reported to specialty bureaus like Clarity Services and FactorTrust, and if you default and the debt goes to a collector, that collection can appear on your regular reports.
Is a guaranteed approval loan legal?
Lending itself is legal when licensed. Advertising “guaranteed approval” is deceptive marketing, and charging a fee before delivering a promised loan violates the FTC’s Telemarketing Sales Rule. Any lender who uses the phrase deserves extra scrutiny of its license and disclosures.
Laws and regulations referenced
- Truth in Lending Act, 15 U.S.C. 1601
- Regulation Z, 12 CFR Part 1026
- Fair Debt Collection Practices Act, 15 U.S.C. 1692
- Fair Credit Reporting Act, 15 U.S.C. 1681
- Equal Credit Opportunity Act, 15 U.S.C. 1691
- Regulation B (equal credit), 12 CFR Part 1002
- Electronic Fund Transfer Act, 15 U.S.C. 1693
- Military Lending Act, 10 U.S.C. 987
- CFPB payday lending rule, 12 CFR Part 1041
Links go to the official text on government sites.
Check, verify or complain
Sources
- consumer.ftc.gov › articles › what know about payday and car title loans consumer.ftc.gov · primary source
- ncua.gov › regulation supervision › letters credit unions other guidance › principle… ncua.gov · primary source
- thinksaveretire.com › cash advance apps thinksaveretire.com
- credizen.net › en US › blog › education › payday loan interest rates credizen.net
- armyemergencyrelief.org › news › how the military lending act protects service members armyemergencyrelief.org
- lendingtree.com › personal › payday alternative loan lendingtree.com

Dana writes US Financer's guides to payday loans, personal and installment loans, bad credit borrowing and cash advance apps. Every piece starts from what a loan really costs, works the numbers in a table, and checks what the lender's own disclosure and your state's rules…