

Maryland caps interest at 33% a year on the first $1,000 of small consumer loans. A typical 300% to 400% APR payday loan therefore cannot be made legally in the state, and you will not find licensed payday storefronts in Baltimore, Silver Spring or Waldorf. Licensed lenders can still make small loans under that cap. Since October 2025, licensed cash advance (earned wage access) apps have been allowed to charge small flat fees under a separate law, and since October 1, 2026 those apps may not ask you for tips.
BLOCKEDRelated consumer alert, Nov 9
FinCEN, Fed pull crypto Travel Rule proposal to seek new public inputRun the numbers
Key takeaways
- Commercial Law §12-306 caps interest at 33% a year on the first $1,000 and 24% above that, for loans of $25,000 or less.
- A loan of $25,000 or less from an unlicensed, non-exempt lender is void and unenforceable under Commercial Law §12-314.
- Cash advance apps need a Maryland license, must offer a free option, and can charge $5 or $7.50 only for faster delivery.
- Since October 1, 2026 (SB 94), Maryland earned wage access providers may not ask for tips.
- The deadline to sue on most debts in Maryland is 3 years, separate from the roughly 7-year credit report window.
In this guide
- Are payday loans legal in Maryland?
- Maryland’s interest rate caps, explained with real numbers
- Payday and short-term loan rules: fees, size, term and rollovers
- Legit fast-cash options in Maryland if you have bad credit
- Car title loans in Maryland
- Installment and personal loans in Maryland: caps and licensing
- Cash advance and earned wage access apps: Maryland’s separate rules
- Online, tribal and offshore lenders
- How to check a lender’s license and file a complaint
- Federal protections that also apply in Maryland
- Already owe an online payday lender? What to do, step by step
- Can you get in trouble for not repaying? Time limits, credit and collections
- How Maryland compares with DC and nearby states
- Lower-cost help Marylanders actually have
- FAQ
Fact-checked
We checked these key facts against the sources named, on November 11, 2026:
- For the app example, $5 ÷ $50 = 10% per two weeks, and 10% × 26.07 ≈ 261% (source: consumerfinance.gov)
- Maryland caps interest at 33% a year on the first $1,000 of small consumer loans (source: dllr.state.md.us)
- For the payday example, $75 ÷ $500 = 15% per two weeks, and 15% × (365 ÷ 14) ≈ 391% (source: consumerfinance.gov)
- The legal maximum is 2.75% on $1,000 ($27.50) plus 2% on the remaining $500 ($10.00), so $37.50 in total (source: mgaleg.maryland.gov)
- 847) takes effect | EWA apps licensed, fees capped at $5 / $7.50 | | Apr 28, 2026 | Governor Wes Moore signs SB 94 (Ch (source: labor.maryland.gov)
Are payday loans legal in Maryland?
On paper, payday loans are legal in Maryland. In practice nobody can offer one. The law does not ban short-term loans by name, but it caps the interest any licensed lender can charge, and a two-week loan priced like a payday loan would break that cap many times over. Last updated November 11, 2026.
Under the Maryland Consumer Loan Law and the rate rules in Commercial Law §12-306, a lender making a loan of $25,000 or less needs a license from the Commissioner of Financial Regulation, who heads the Office of Financial Regulation (OFR) inside the Maryland Department of Labor. The lender must also stay within the tiered caps described below. A storefront that charges $15 for every $100 borrowed over two weeks is charging roughly 391% APR, so no licensed Maryland lender offers that product. That is why Baltimore has no payday stores while shops operate across the border in Delaware.
Three kinds of products are still lawful. Licensed lenders can make small installment loans within the caps. Licensed earned wage access apps can charge capped fees under a separate rule that took effect October 1, 2025. Banks and federally chartered credit unions can lend under federal rules, including the credit union payday alternative loan programs. Federal rules affecting payday lenders also remain unsettled, as covered further down.
What counts as a “payday loan” under Maryland law
Maryland has no special payday or “deferred deposit” license. In most states a payday loan is a small, single-payment loan due on your next payday and repaid from a post-dated check or bank debit. Maryland does not regulate it as a separate product. It treats it as an ordinary consumer loan, so the Consumer Loan Law license requirement and the §12-306 caps apply in full. The OFR takes the same approach to newer products: in its view, buy now, pay later plans and earned wage access advances are loans too.
Small-dollar credit in Maryland at a glance (November 2026)
| Product | Legal in MD? | Cost limit | License needed | Governing law / effective date |
|---|---|---|---|---|
| Storefront or online payday loan | Only within the caps, so not offered | 33% / 24% annual rate tiers | Yes, Consumer Loan Law | Commercial Law §12-306, §12-314 |
| Car title loan | Only within the caps | 33% / 24% annual rate tiers | Yes | Consumer Loan Law; OFR title loan advisory (2017) |
| Small installment loan (≤ $25,000) | Yes | 33% / 24% annual rate tiers | Yes | Commercial Law §12-306 |
| Earned wage access / cash advance app | Yes | $5 (≤ $75) or $7.50 (> $75) for expedited delivery only; free option required | Yes, Consumer Loan Law | HB 1294, Ch. 847 (Oct 1, 2025); SB 94, Ch. 170 (Oct 1, 2026) |
| Buy now, pay later | Yes, if licensed | Treated as a loan | Yes, per OFR | OFR order to Four Technologies (May 2024) |
| Credit union payday alternative loan | Yes, at federal credit unions | 28% APR, $20 max application fee | Federal charter (NCUA) | 12 CFR 701.21 |
Timeline of Maryland small-loan law changes
| Date | Change | What it means for borrowers |
|---|---|---|
| 2009 | OFR Advisory 7-09 | Collecting on loans made by unlicensed, non-exempt lenders is illegal |
| Aug 2017 | OFR vehicle title loan advisory | Title loans are consumer loans, not pawns, and need a license |
| Jan 1, 2019 | HB 1297 (Ch. 790) raises small-loan threshold from $6,000 to $25,000 | Licensing and caps cover far more loans |
| 2019 | FovoPayday consent order | Online payday lender sanctioned for unlicensed, usurious loans |
| May 2024 | OFR order to Four Technologies | BNPL treated as a loan needing a license |
| Mar 30, 2025 | CFPB payment provisions reach compliance date | Two-failed-withdrawal limit on paper; enforcement deprioritized |
| Oct 1, 2025 | HB 1294 (Ch. 847) takes effect | EWA apps licensed, fees capped at $5 / $7.50 |
| Apr 28, 2026 | Governor Wes Moore signs SB 94 (Ch. 170) | Tip ban enacted |
| Oct 1, 2026 | SB 94 takes effect | No tips; any tip refunded within 7 days |
Maryland’s interest rate caps, explained with real numbers
Commercial Law §12-306 caps interest on consumer loans of $25,000 or less in tiers, based on the original principal balance. On a loan of $2,000 or less, the cap is 2.75% a month (33% a year) on the first $1,000 and 2% a month (24% a year) on the next $1,000. On a loan over $2,000, the cap is 2% a month (24% a year) on the whole balance.
| Loan portion / size | Max monthly rate | Max annual rate | Example: max interest for 1 month |
|---|---|---|---|
| First $1,000 of a loan of $2,000 or less | 2.75% | 33% | $500 loan: $13.75 |
| Second $1,000 of a loan of $2,000 or less | 2% | 24% | $2,000 loan: $27.50 + $20.00 = $47.50 |
| Entire balance of a loan over $2,000 | 2% | 24% | $3,000 loan: $60.00 |
The examples are illustrations, not quotes. They show the most simple interest the statute allows on the full balance for one month.
Loans of $2,000 or less
Most emergency borrowing falls in this tier, and the higher 33% rate applies only to the first $1,000. Take a $1,500 loan for one month. The legal maximum is 2.75% on $1,000 ($27.50) plus 2% on the remaining $500 ($10.00), so $37.50 in total. The blended rate works out to about 30% a year.
A longer loan shows the cap more clearly. A $500 loan at the full 33% annual rate, repaid in 12 equal monthly payments, costs about $49.48 a month. You would repay about $594 in total, so roughly $94 of interest. That is the most a licensed lender could charge on that loan.
Loans over $2,000
Once the original principal is above $2,000, the whole balance falls under the 24% cap. A $3,000 loan can carry at most $60 of interest in its first month. Repaid over 24 months at the 24% maximum, total interest comes to roughly $800 (illustration). Lenders often charge less than the cap to borrowers with stronger credit.
Worked comparison: the same $500, three ways
The table compares what $500 for two weeks costs under Maryland’s cap, what a typical payday loan costs in states that allow them, and what a Maryland earned wage access fee costs.
| Scenario | Amount | Fee or rate | Term | Cost | Total repaid | APR |
|---|---|---|---|---|---|---|
| Maryland licensed loan at the cap | $500 | 33% annual | 14 days | about $6.33 | about $506.33 | 33% |
| Typical payday loan in a permissive state | $500 | $15 per $100 | 14 days | $75.00 | $575.00 | about 391% |
| Maryland EWA app, expedited, $50 advance | $50 | $5 flat | 14 days | $5.00 | $55.00 ($50 deducted from pay plus $5 fee) | about 261% |
Illustrations. The APR math works like this. Divide the fee by the amount borrowed to get the cost for the period, then multiply by the number of such periods in a year. For the payday example, $75 ÷ $500 = 15% per two weeks, and 15% × (365 ÷ 14) ≈ 391%. For the app example, $5 ÷ $50 = 10% per two weeks, and 10% × 26.07 ≈ 261%. EWA fees are exempt from the 33% cap, which is why that APR can run so high.
What happens if a lender charges more than the cap
A lender that breaks Maryland’s rules loses money on the loan, and an unlicensed lender can lose the whole loan. This section is the full explanation of the “void loan” rule. Later sections refer back to it.
- Unlicensed or noncompliant loans (Commercial Law §12-314). No one may lend $25,000 or less if the loan carries interest, charges, discounts or other consideration above what state law authorizes. Under §12-314(b), a loan of $25,000 or less is void and unenforceable in several situations, including when the lender is unlicensed and not exempt. The lender may not keep any principal, interest, fees or other compensation on a void loan. Maryland’s highest court described the same no-retention rule in a 2022 opinion.
- Excess charges by a lender (Commercial Law §12-313). If the overcharge was not willful and the lender fails to correct it before your next payment, the lender owes you three times the excess but may keep collecting principal and lawful interest. If the overcharge was willful, the lender loses the right to keep any interest or other compensation on the loan.
- Collection on unlicensed loans. The OFR’s Advisory 7-09, issued in 2009 and still posted, says it is illegal to pursue collection actions against Maryland residents for loans made by unlicensed entities unless the entity is exempt under Maryland law. Debt buyers and collectors who take over these loans are bound by the same rule.
These remedies are why the OFR orders restitution. Its annual report for the fiscal year ended June 30, 2025 shows $189,364 ordered back to Maryland consumers harmed by earlier unlicensed activity.
Did you know?
According to the OFR’s annual report for the fiscal year ended June 30, 2025, the office licensed or registered 17,545 businesses and individuals. Every one of them should be searchable before you hand over bank details.
Payday and short-term loan rules: fees, size, term and rollovers
Maryland has no payday-specific fee schedule, loan maximum, rollover limit, cooling-off period or statewide loan database. It never created a licensed payday product that would need those rules. Any short-term loan follows the same Consumer Loan Law rules as every other small loan.
| Rule | Typical payday state | Maryland |
|---|---|---|
| Fee schedule | Set fee per $100 borrowed | None; all charges count toward the §12-306 cap |
| Maximum loan | Often $500 to $1,000 | No payday ceiling; licensing and caps cover loans up to $25,000 |
| Minimum term | Often 7 to 14 days | None set, but the cap makes short, high-fee loans unprofitable |
| Rollovers | Limited by count | No payday loans to roll over |
| Statewide database | Often used to track loans | None needed |
A few points matter more than the rest:
- Fees count. Section 12-314 measures interest, charges, discounts and “other consideration” against what the law authorizes. A lender cannot get around the cap by calling part of its price a fee.
- Renewals are a warning sign. If an online lender “renews” your loan for another fee, the loan almost certainly breaks Maryland law.
“Same day loans” in Maryland
A licensed lender may fund a loan the same day, and nothing in Maryland law forbids quick funding. The warning sign is a combination: instant approval, “no credit check,” a two-week due date and a fee of tens of dollars per $100. Lenders that offer that package to Marylanders are nearly always unlicensed. “No credit check” usually means the lender uses bank account data or alternative credit bureaus and charges more to cover the extra risk.
Legit fast-cash options in Maryland if you have bad credit
Bad credit does not create a separate set of rules in Maryland. The same 33% and 24% caps apply whatever your score, so a lender that charges you more because your credit is poor is breaking the law, not offering you a special product. The legal routes to fast money are a credit union small-dollar loan, a licensed installment lender you have checked in NMLS Consumer Access, a free earned wage access transfer, an employer advance, and emergency help through 211.
The list below runs from cheapest and safest to most expensive. Speed depends on the provider and your bank, so the timings are typical ranges, not promises.
| Rank | Option | Typical speed | Most it can cost under Maryland or federal rules | Bad-credit fit |
|---|---|---|---|---|
| 1 | Maryland 211 and local assistance | Varies by program | Often free (grants or bill payments) | Credit history usually not a factor |
| 2 | Employer pay advance | Next payroll or sooner | Often free | No credit check by most employers |
| 3 | Free EWA transfer from a licensed app | Usually 1 to 3 business days | $0 for the standard transfer (required by law) | Based on your pay history, not your score |
| 4 | Credit union payday alternative loan (PAL) | Often within days once you are a member | 28% APR, $20 application fee cap | Credit unions weigh membership and income |
| 5 | Licensed installment lender, checked in NMLS | Same day to a few days | 33% on the first $1,000, 24% above | Accepts thinner files, usually prices near the cap |
Expedited EWA delivery ($5 or $7.50) sits between options 3 and 4 on price. On a small advance it can cost a higher APR than a PAL, as the worked comparison above shows.
What a $1,000 loan costs under the cap
The worked example shows the ceiling, not a quote. It compares a $1,000 loan repaid over 12 months from a federal credit union PAL II and from a licensed lender charging the Maryland maximum.
| Loan | Amount | APR | Term | Monthly payment | Total repaid |
|---|---|---|---|---|---|
| Federal credit union PAL II | $1,000 | 28% (plus up to $20 fee) | 12 months | about $96.50 | about $1,158, plus fee |
| Licensed Maryland lender at the cap | $1,000 | 33% | 12 months | about $98.97 | about $1,188 |
| Typical payday pricing in a permissive state, rolled every 2 weeks | $1,000 | about 391% | 12 months | Not comparable | Fees alone could top $3,900 |
Illustrations. The last row assumes a $150 fee every two weeks for 26 periods. That is the debt cycle Maryland’s cap is designed to stop.
Your rights when you have bad credit
The Equal Credit Opportunity Act bars lenders from discriminating on race, color, religion, national origin, sex, marital status, age, or because your income comes from public assistance. A lender can turn you down for weak credit. It cannot charge you above Maryland’s cap because of it, and if it denies you it must give you the reasons or tell you how to ask for them.
How to spot an illegitimate “payday loans Baltimore” ad
Ads for “payday loans Baltimore,” “payday loans Waldorf” or “I need a payday loan immediately” usually lead to lead-generation sites or unlicensed online lenders. Three checks catch most of them:
- No Maryland license you can verify. No NMLS ID, or an NMLS record with no Maryland Consumer Loan License, means the lender is not allowed to make the loan.
- Payday pricing. A fee quoted per $100, a two-week due date or a single balloon payment cannot fit under a 33% cap at any profitable fee.
- Money or access up front. A request for an “insurance,” “processing” or “verification” fee before funding, payment in gift cards, or a demand for your online banking login is a scam pattern the FTC warns about. Legitimate lenders take fees out of the loan or charge them on the disclosure, not before you get the money.
Car title loans in Maryland
Car title loans are not banned by name, but they are consumer loans. The lender needs a license, and the same 33% and 24% caps apply. A title loan priced at the 300% APR common in other states is illegal in Maryland.
In an August 2017 advisory, the OFR said vehicle title lenders are covered by the Maryland Consumer Loan Law and the state’s installment loan laws, and are subject to the Commissioner’s investigation and enforcement powers. The advisory also said a vehicle title loan is not a pawn transaction. That matters because some lenders have called their products “title pawns” to avoid lending rules.
The Maryland Attorney General’s case against Cash-N-Go shows how this plays out. The state charged the company in 2019 with making unlicensed, usurious “title pawn” loans. A final order followed in 2020, and in 2021 a circuit court upheld the findings that the transactions were illegal consumer loans. If a lender is threatening to repossess your car over a high-rate title loan, start with the license check and OFR complaint process below. The void-loan rule explained in the cap section may apply.
Installment and personal loans in Maryland: caps and licensing
You can get an installment loan in Maryland from a licensed consumer lender. Loans of $25,000 or less follow the §12-306 caps. Loans above $25,000 fall under other credit provisions of Commercial Law Title 12, and banks and federal credit unions lend under their own charters.
The 2018 law HB 1297 (Chapter 790), effective January 1, 2019, raised the Consumer Loan Law threshold from $6,000 to $25,000. It also barred anyone from lending $25,000 or less without a Consumer Loan Law license unless exempt. Many personal loans that once fell outside the small-loan rules are now covered by them.
| Lender type | Strengths | Weaknesses |
|---|---|---|
| Licensed nonbank lender | Funds quickly, accepts thinner credit files | Usually prices at or near the cap |
| Credit union | Lower rates, PAL products up to $2,000 | Membership required; PAL I may need a month of membership |
| Bank-partner online lender | Fast online process, larger amounts | May legally charge more than Maryland’s cap in some cases (see below) |
With any of them, check the APR on the Truth in Lending disclosure, not only the monthly payment.
The OFR convened a licensing workgroup in 2026 to review the licensing provisions in Financial Institutions Title 11, Subtitle 2, and the credit provisions of Commercial Law Title 12, Subtitle 3. As of November 2026, no change to the rate caps has come out of that review.
Cash advance and earned wage access apps: Maryland’s separate rules
Cash advance apps are legal in Maryland only if they hold a Consumer Loan Law license. They must offer a free way to get your money, may charge only $5 or $7.50 for faster delivery, and since October 1, 2026 may not ask for tips. These fees are exempt from the 33% cap.
Earned wage access (EWA) apps such as Earnin, and app-based advance products such as Dave, let you draw money before payday and repay it automatically from your next deposit. The Center for Responsible Lending (CRL) said in April 2026 that app-based payday lenders such as Dave and Earnin regularly charge above 300% APR. That criticism shaped two recent Maryland laws.
What changed on October 1, 2025
HB 1294 of the 2025 session treats earned wage access as a loan and requires third-party providers to be licensed under the Consumer Loan Law. It caps expedited-delivery fees at $5 for advances of $75 or less and $7.50 for larger advances, and requires a no-cost option and a $0 default tip. The bill became law without the governor’s signature under Article II, §17(c) of the Maryland Constitution, as Chapter 847 on May 25, 2025.
Consumer advocates objected that the bill let these providers charge fees outside the 33% cap. As the worked comparison above shows, those fees can reach triple-digit APRs on small advances.
Did you know?
According to the Maryland General Assembly’s bill record, the 2025 law allowing paid earned wage access fees outside the 33% cap became law without Governor Wes Moore’s signature, as Chapter 847. A year later he signed SB 94, which banned tips on those same apps.
What changed on October 1, 2026: the tip ban
Governor Wes Moore signed SB 94 on April 28, 2026, as Chapter 170, and it took effect October 1, 2026. App-based lenders and EWA providers may no longer ask for tips, and their contracts must say tips are prohibited. Any tip a provider receives must be refunded within 7 days, down from the 30 days allowed under the 2025 law. SB 94 also restored the small-dollar law’s anti-discrimination and unfair or deceptive practice rules for these providers. It did not bring their fees under the 33% cap. CRL, Economic Action Maryland, the CASH Campaign of Maryland and the NAACP were among the groups that pushed for the 2026 reforms.
What the apps can still charge
| Transfer type | Advance size | Maximum charge | Tip allowed? |
|---|---|---|---|
| Standard (no-cost option every provider must offer) | Any | $0 | No |
| Expedited | $75 or less | $5 | No |
| Expedited | Over $75 | $7.50 | No |
An app cannot ask for a tip or set one by default, and it must refund any tip within 7 days.
Use the free transfer
If you use a cash advance app in Maryland, choose the no-cost transfer the law requires. The $5 or $7.50 fee applies only to expedited delivery, and since October 1, 2026 any request for a tip is a violation you can report to the OFR.
Online, tribal and offshore lenders
Maryland law applies to any lender that lends to Maryland residents, wherever the company is based. An online lender making consumer loans of $25,000 or less to Marylanders needs a Maryland license unless it is exempt, for example a bank. Loans from unlicensed, non-exempt lenders fall under the void-loan and no-collection rules explained in the cap section above.
The OFR has enforced this against internet lenders. In 2019 it entered a consent order against the online lender FovoPayday for unlicensed and usurious consumer lending. In May 2024 it ordered Four Technologies, a buy now, pay later company, to stop unlicensed lending after finding that its BNPL product was a loan under Maryland law.
Tribal lenders
Some online lenders say they are owned by a Native American tribe and that only tribal law applies. Maryland’s licensing rules contain no such exemption, and the OFR’s position on unlicensed lending makes no exception for one. The U.S. Court of Appeals for the Fourth Circuit, which covers Maryland, held in Hengle v. Treppa, 19 F.4th 324 (2021), that tribal-law clauses in loan agreements could not be used to waive borrowers’ rights under state and federal law. Treat a tribal-law clause in a high-rate loan as a red flag. It does not prove the loan is valid.
Bank-partner (“rent-a-bank”) loans
Federal banking law lets a state-chartered bank charge the rate allowed in its home state, even to borrowers elsewhere. Some fintech lenders use this to offer higher-rate loans through a partner bank. When the bank really is the lender, Maryland’s caps may not apply. When a nonbank does the marketing, takes most of the risk and buys the loans, regulators in several states have argued that the nonbank is the “true lender” and must follow state law. If your loan documents name an out-of-state bank as the lender and the price looks out of line, report it to the OFR, which can look at who the real lender is.
How to check a lender’s license and file a complaint
Every lender, EWA app, debt collector and debt management company that needs a Maryland license is listed in NMLS Consumer Access, the public database of the Nationwide Multistate Licensing System. Complaints go to the Maryland OFR, and you can also file with the Consumer Financial Protection Bureau.
How to check a lender's Maryland license
- Go to nmlsconsumeraccess.org and search the company’s exact legal name, or the NMLS ID from its website footer or loan agreement.
- Open the company record and look under state licenses for “Maryland” and the license type Consumer Loan License.
- Confirm the status is “Approved” or “Active,” and that the name and address match the company you are dealing with.
- If nothing shows up, or the license is for a different activity, treat the lender as unlicensed for consumer loans until the OFR says otherwise.
- Call the OFR at 410-230-6077 if the record is unclear, for example when a company uses a trade name.
To file a complaint with the Maryland OFR, email [email protected] or call 410-230-6077. Include your name and address, the lender’s name and website, the loan agreement, any payment schedule, bank statements showing debits, and copies of letters, emails or texts.
| Where to report | Best for | How |
|---|---|---|
| Maryland Office of Financial Regulation | Unlicensed lending, cap violations, EWA tip requests | [email protected] or 410-230-6077 |
| Consumer Financial Protection Bureau | Any lender, collector or app; the company must respond | consumerfinance.gov or 855-411-2372 |
| FTC ReportFraud | Advance-fee scams, fake lenders | ReportFraud.ftc.gov |
| FBI Internet Crime Complaint Center | Online threats, extortion, identity theft | IC3.gov |
Check before you share bank details
Search the lender in NMLS Consumer Access before giving it your bank login, routing number or debit card. An unlicensed lender that already has your account details can start debiting before you find out it was never allowed to lend in Maryland.
Federal protections that also apply in Maryland
Federal law adds a layer on top of Maryland’s caps. The Truth in Lending Act requires cost disclosures, the Electronic Fund Transfer Act lets you stop automatic debits, the Military Lending Act caps rates for service members, and the Fair Debt Collection Practices Act limits third-party collectors.
Truth in Lending disclosures
Under the Truth in Lending Act and Regulation Z (12 CFR 1026), a lender must show you the APR, the finance charge, the amount financed and the total of payments before you sign. Compare loans by APR, which includes most fees. Two loans with the same monthly payment can have very different total costs.
The CFPB payday rule in 2026
The payment provisions of the CFPB Payday Lending Rule (12 CFR part 1041) bar covered lenders from attempting further withdrawals after two consecutive failed attempts unless you give new authorization, and they require advance notices. Those provisions reached their compliance date on March 30, 2025. The CFPB then said it would not prioritize enforcing them, and its regulatory agenda published July 6, 2026 plans a rulemaking to reconsider them. As of mid-October 2026, part 1041 was unchanged. For Maryland borrowers the rule is still law, but you should not count on federal enforcement. Your own right to revoke debits under the Electronic Fund Transfer Act is the stronger tool.
Stopping automatic withdrawals
Under the Electronic Fund Transfer Act and Regulation E (12 CFR 1005.10), you can stop a preauthorized recurring debit by notifying your bank at least three business days before the scheduled transfer. The bank may ask for written confirmation within 14 days. You can also revoke the authorization with the lender directly. Doing both, in writing, gives you the strongest record.
Military borrowers
The Military Lending Act (10 U.S.C. §987 and 32 CFR part 232) caps the military annual percentage rate at 36% for active-duty service members and their dependents. That rate includes most fees, including add-on products that ordinary APR leaves out. The law also bans mandatory arbitration and allotment-based repayment. Families at Fort Meade, Joint Base Andrews or Aberdeen Proving Ground can also ask Army Emergency Relief, the Navy-Marine Corps Relief Society or the Air Force Aid Society about no-interest loans and grants. The Servicemembers Civil Relief Act separately caps interest at 6% on debts taken on before active duty.
Already owe an online payday lender? What to do, step by step
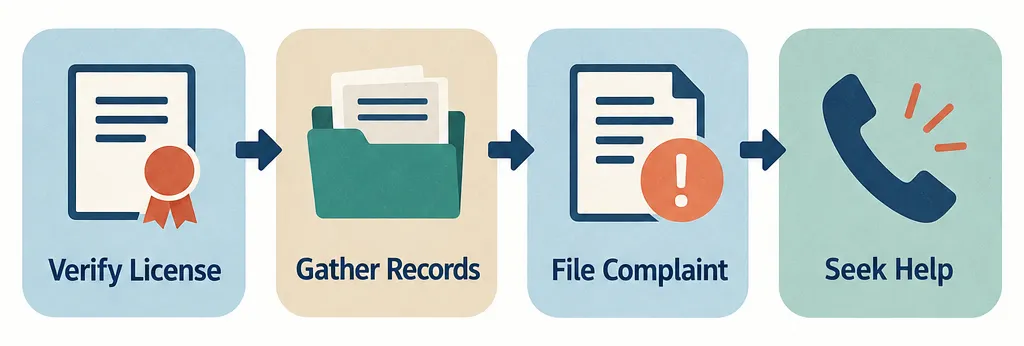
If you borrowed from an online lender that turns out not to be licensed in Maryland, the loan is likely void under §12-314, as explained in the cap section, and the OFR says collecting on it is illegal. The practical steps are to stop the debits, document everything, file a complaint and get legal advice before you change how you pay.
Readers often ask: “I took an online payday loan and just found out they’re not licensed in Maryland. Should I stop paying?” Under the statute, an unlicensed, non-exempt lender has no enforceable right to collect. Getting money back and winding the loan down is easiest through the OFR, which can order restitution, and through a legal aid lawyer who can read your contract.
- Confirm the license status in NMLS Consumer Access, using the steps above.
- Gather records: the loan agreement, the original disclosure, every bank statement showing a debit, and all emails, texts and call logs.
- Revoke ACH authorization in writing with both the lender and your bank, and keep dated copies.
- Ask your bank to stop payment on future debits under Regulation E. If the lender keeps debiting after you revoked authorization, dispute those debits as unauthorized.
- File an OFR complaint at [email protected] or 410-230-6077, attaching your records.
- Never ignore court papers. If you are served with a lawsuit, file the notice of intention to defend or answer by the deadline on the summons. A lender that wins by default can garnish your wages even when the loan was void.
- Contact legal aid, such as Maryland Legal Aid or the Maryland Volunteer Lawyers Service, which help with consumer debt cases.
“The lender keeps pulling money from my account even after I asked them to stop” is a common complaint. If you revoked authorization with the lender and notified your bank, later debits count as unauthorized electronic fund transfers. Report them to your bank promptly, because Regulation E’s protections depend on how fast you report. Then add the debits to your OFR and CFPB complaints.
Put it in writing
When you revoke an ACH authorization, send a dated letter or email to both the lender and your bank naming the account, the lender and the date authorization ends. Keep copies and screenshots. Your OFR complaint will be much stronger with that paper trail.
Can you get in trouble for not repaying? Time limits, credit and collections
You cannot be arrested in Maryland for failing to repay a payday loan or any other consumer debt. Unpaid debt is a civil matter. What can happen is a lawsuit, a judgment, wage garnishment, a bank levy and damage to your credit, each within legal limits.
There is one exception to “no jail.” After a judgment, a Maryland court can order you to appear for questioning about your assets. If you ignore that order, the court can issue a body attachment, which is an order to bring you before the judge. The cause is ignoring the court, not the debt. Any collector who threatens arrest over the debt itself is breaking the Fair Debt Collection Practices Act, which bans false threats of arrest. Maryland’s own Consumer Debt Collection Act, Commercial Law §14-202, also bars collectors from threatening to enforce a right they know does not exist. That covers trying to collect a void loan.
Can a payday lender come after you after 7 years?
There are two separate clocks. Maryland’s general deadline to sue on written contracts and open accounts is 3 years under Courts and Judicial Proceedings §5-101. The roughly 7-year period is how long negative items can stay on your credit report under the Fair Credit Reporting Act. After 3 years a collector can still ask you to pay, but under the CFPB’s Regulation F (12 CFR 1006.26) it may not sue or threaten to sue on a time-barred debt.
| Clock | Length | What it limits | Source |
|---|---|---|---|
| Lawsuit deadline | 3 years (most contract debts) | When a creditor or collector can sue you | Cts. & Jud. Proc. §5-101 |
| Credit report | About 7 years from first delinquency | How long the negative item can be reported | Fair Credit Reporting Act |
| Collection requests | No fixed end | Collectors may ask, but not sue or threaten suit after the deadline | Fair Debt Collection Practices Act; Regulation F |
The 3-year clock usually starts at default, but the start date and whether a later payment or written promise affects the deadline depend on the facts. Get advice from legal aid before you pay anything on a debt that is several years old. “I’m getting calls about a payday loan from years ago. Can they still sue me?” Usually not after 3 years. If they do sue, you must raise the time limit as a defense in court, because the court will not apply it automatically.
Will it hurt your credit?
Many payday and app lenders do not report to Equifax, Experian or TransUnion, so on-time payments rarely help your score. A debt sold to a collector, though, can show up as a collection account and stay for about seven years. If a collector reports an unlicensed loan, you can dispute the entry with the credit bureaus as inaccurate, citing §12-314.
Wage garnishment and bank account limits
Garnishment needs a court judgment first. Under Commercial Law §15-601.1, the amount protected from a wage attachment is the greater of 75% of your disposable wages or 30 times the state minimum hourly wage for each week the wages were earned. At Maryland’s $15.00 minimum wage, unchanged for 2026, that floor is $450 a week.
Worked example (illustration). With $600 of weekly disposable pay, 75% is $450 and the 30-times floor is also $450, so up to $150 can be taken. With $500 of weekly disposable pay, 75% is $375, but the floor protects $450, so at most $50 can be taken. Below $450 a week, nothing can be garnished.
Courts and Judicial Proceedings §11-504 provides separate exemptions for certain property and bank funds. Federal law protects Social Security and most other federal benefits deposited directly into your account. If a creditor freezes your account, file the exemption request with the court right away.
How Maryland compares with DC and nearby states
Maryland is one of the jurisdictions that have shut out high-cost payday lending through a rate cap. Its 33% ceiling on the first $1,000 sits close to the District of Columbia’s 24% cap and far below the effective rates allowed in states that license payday lenders.
| Jurisdiction | Payday lending status | Rate rule |
|---|---|---|
| Maryland | No licensed payday product | 33% / 24% tiers, Commercial Law §12-306 |
| District of Columbia | Payday exemption removed in 2007 | 24% general cap, D.C. Code §28-3301 |
| Virginia | Short-term loans allowed under the 2020 Fairness in Lending Act | 36% interest plus a limited monthly fee |
| Pennsylvania | No licensed payday lending | Consumer lending rate limits apply |
| Delaware | Payday loans licensed | Limits on the number of loans per year, not on price |
This matters for people who live in Waldorf or Prince George’s County and work in DC, or who live in Cecil County near the Delaware line. Maryland’s protections follow where you live and where the loan is made. Crossing into Delaware to sign a payday loan in person puts that loan under Delaware’s rules. Borrowers comparing other states will find similar breakdowns in our guides to Texas payday loan laws and Florida payday loan laws, both states where storefront payday lending is licensed.
Which states ban payday loans?
About 20 states plus DC effectively prohibit triple-digit payday loans through rate caps of roughly 36% APR or lower. The Center for Responsible Lending’s July 2025 count put the number at 21 states plus DC once Rhode Island enacted its 36% cap. Rhode Island’s cap does not take effect until January 1, 2027, so for most of 2026 the working figure was 20. Other tallies come out lower because they count only outright bans by name and leave out states like Maryland, where a general rate cap makes payday lending impossible without naming it.
Lower-cost help Marylanders actually have
Before any high-cost credit, look at the options that cost little or nothing. A free EWA transfer, a credit union small-dollar loan, a creditor hardship plan or a local assistance program can cover many emergencies for a fraction of the cost.
Cheaper options first
Ask a credit union about a payday alternative loan: 28% APR maximum and a $20 application fee cap at federal credit unions.
Ask your utility, landlord or card issuer for a hardship plan before you borrow to pay them.
Dial 211 in Maryland to reach local emergency help with rent, food and utility bills.
| Option | Who runs it | Typical cost | Best for |
|---|---|---|---|
| PAL I | Federal credit unions (NCUA rules) | 28% APR max, $20 fee max | $200 to $1,000 over 1 to 6 months |
| PAL II | Federal credit unions (NCUA rules) | 28% APR max, $20 fee max | Up to $2,000 over 1 to 12 months |
| Maryland Energy Assistance Program / Electric Universal Service Program | Maryland Department of Human Services, Office of Home Energy Programs | Free assistance | Heating and electric bills |
| Debt management plan | Nonprofit credit counselors licensed in Maryland | Small monthly fee, lower card interest | Several unsecured debts |
| Free tax preparation and coaching | CASH Campaign of Maryland | Free | Getting a refund or credit sooner |
- Credit union payday alternative loans. Under NCUA rules (12 CFR 701.21), both PAL types cap the APR at 28% and the application fee at $20. Some credit unions require a month of membership for PAL I. PAL II has no minimum membership period. A $500 PAL I loan at 28% over six months costs about $42 in interest (illustration).
- Employer and no-fee advances. Some employers advance wages directly at no cost. A licensed EWA app’s standard transfer is free by law in Maryland.
- Hardship and payment plans. Utilities regulated by the Maryland Public Service Commission, many landlords and most card issuers offer payment arrangements. Ask before the bill is past due.
- Benefits and local programs. Maryland 211 and the federal benefit finder at USA.gov point to food, rent and medical help.
- Debt relief programs in Maryland. Nonprofit credit counseling agencies, many of them members of the National Foundation for Credit Counseling, can set up a debt management plan with lower interest. In Maryland, debt management providers must be licensed by the Commissioner of Financial Regulation, so check them in NMLS Consumer Access too. Under the FTC’s Telemarketing Sales Rule, debt settlement companies that sell by phone may not charge fees before they settle a debt.
There is an honest counter-argument. When an emergency is real and immediate, such as a car repair you need to keep a job, a licensed installment loan at Maryland’s capped rate can be a reasonable choice. Even at the 33% maximum, that loan costs a small fraction of what payday products cost in other states. The danger in Maryland comes from unlicensed lenders, not from borrowing itself.
Before you borrow
The biggest risk in Maryland is an online lender that offers “same day” cash at payday-style prices without a Maryland license. If you hand over your bank access first, it can debit you repeatedly before you learn that the loan was illegal. Check NMLS Consumer Access before you sign anything.
FAQ
Are payday loans allowed in Maryland?
Not in the usual form. Maryland has no special payday license, and Commercial Law §12-306 caps interest at 2.75% a month (33% a year) on the first $1,000 of a small loan. That makes the typical 300%-plus APR payday loan illegal. Licensed lenders can make small installment loans within the cap, and licensed EWA apps can charge capped delivery fees.
What is the maximum interest rate on a loan in Maryland?
For consumer loans of $2,000 or less, the cap is 2.75% a month (33% a year) on the first $1,000 and 2% a month (24% a year) on the second $1,000. For loans over $2,000 and up to $25,000, it is 2% a month (24% a year) on the full balance. Earned wage access fees of $5 or $7.50 fall under a separate rule.
Can I get a loan in Maryland with bad credit?
Yes, from licensed lenders and credit unions, and always within the same 33% and 24% caps. Bad credit does not let a lender charge more. Start with free options such as an employer advance or a free EWA transfer, then a credit union PAL, and only then a licensed installment lender you have checked in NMLS Consumer Access.
How do I know if a Maryland lender is legit?
Search the company in NMLS Consumer Access and look for a Maryland Consumer Loan License with an approved or active status. Be wary of a lender that quotes a fee per $100, sets a two-week due date, asks for an upfront fee or wants your online banking login. A lender that does any of those is very unlikely to be operating legally in Maryland.
Do I have to repay a loan from an unlicensed lender in Maryland?
Under Commercial Law §12-314, a loan of $25,000 or less from an unlicensed, non-exempt lender is void and unenforceable, and the OFR’s Advisory 7-09 says collecting on it is illegal. Revoke debit authorization, file an OFR complaint and talk to legal aid. Never ignore a lawsuit.
Are cash advance apps like Dave and Earnin legal in Maryland?
They can operate legally if they hold a Maryland Consumer Loan Law license, which HB 1294 has required since October 1, 2025. They must offer a free transfer option and can charge only $5 (advances of $75 or less) or $7.50 (larger advances) for expedited delivery. Since October 1, 2026, they cannot ask for tips.
Can cash advance apps ask for tips in Maryland?
No. SB 94, signed by Governor Wes Moore on April 28, 2026 and in effect since October 1, 2026, bans EWA providers and app-based lenders from soliciting tips. Any tip received must be refunded within 7 days. Report a tip request to the OFR at 410-230-6077 or [email protected].
How do I report a payday lender in Maryland?
File a complaint with the Maryland Office of Financial Regulation by email at [email protected] or by phone at 410-230-6077, and attach your loan agreement and bank statements. You can also file with the CFPB at consumerfinance.gov or 855-411-2372. Report suspected fraud to the FTC at ReportFraud.ftc.gov.
Laws and regulations referenced
- Truth in Lending Act, 15 U.S.C. 1601
- Regulation Z, 12 CFR Part 1026
- Fair Debt Collection Practices Act, 15 U.S.C. 1692
- Regulation F (debt collection), 12 CFR Part 1006
- Fair Credit Reporting Act, 15 U.S.C. 1681
- Equal Credit Opportunity Act, 15 U.S.C. 1691
- Electronic Fund Transfer Act, 15 U.S.C. 1693
- Regulation E (electronic transfers), 12 CFR Part 1005
- Military Lending Act, 10 U.S.C. 987
- Servicemembers Civil Relief Act, 50 U.S.C. 3901
- CFPB payday lending rule, 12 CFR Part 1041
Links go to the official text on government sites.
Check, verify or complain
Sources
- "Payday" Loans - Maryland Office of Financial Regulation labor.maryland.gov · primary source
- Maryland Commercial Law §12-306 (2026 statute text) mgaleg.maryland.gov · primary source
- HB 1297 (2018) Fiscal and Policy Note mgaleg.maryland.gov · primary source
- Court of Appeals of Maryland 2022 opinion on CL §12-314 mdcourts.gov · primary source
- HB 1294 (2025RS) - Maryland General Assembly mgaleg.maryland.gov · primary source
- Maryland Office of Financial Regulation Annual Report FY2025 labor.maryland.gov · primary source
- OFR Issues Order to Four Technologies labor.maryland.gov · primary source
- Maryland Licensing Workgroup slides, January 2026 labor.maryland.gov · primary source
- Maryland OFR Advisory on Debt Collection Exemptions labor.md.gov · primary source
- Maryland Courts - Judgments & Debt Collection mdcourts.gov · primary source
- DC OAG Testimony on B25-0609, Protecting Affordable Loans Amendment Act oag.dc.gov · primary source
- Maryland Commercial Law §12-314 (2023) law.justia.com
- Maryland Commercial Law §12-313 law.justia.com
- Maryland Enacts Earned Wage Access Legislation consumerfinancemonitor.com
- Maryland Enacts Reform of Payday Loan App Law - CRL responsiblelending.org
- Maryland Enacts Sweeping Earned Wage Access Reforms, Bans Tipping consumerfinancialserviceslawmonitor.com
- Maryland OFR Advisory 7-09 dllr.state.md.us
- OFR Consent Order - FovoPayday dllr.state.md.us
- OFR Advisory on Vehicle Title Loans dllr.state.md.us
- Maryland charges title company making unlicensed, usurious consumer loans infobytes.orrick.com
- Statute of Limitations on Debt in Maryland supermoney.com
- CFPB's 2026 Regulatory Agenda Tees Up NPRM to Reconsider Payday Lending Rule natlawreview.com
- A 36% Cap on Annual Interest Rate Stops the Payday Lending Debt Cycle - CRL responsiblelending.org

Elena writes about getting through a money emergency, assistance programs, budgeting on a tight income, banking basics and borrower rights. Her guides list the cheaper options first and link the agency or program that can actually help.
Ruth is US Financer's standards editor. Every article goes through her checks before and after it is published: each rate, fee, cap, deadline and rule is matched against its primary source, every law named is linked to its official text, and anything that cannot be…
Comments are closed