We are not a credit repair, debt relief or debt collection company and offer no services. Rules differ by state, so confirm with the agency or a nonprofit counselor before you act.
Debtors Anonymous is a free, member-run twelve-step fellowship for people who cannot stop borrowing or spending money they do not have. It is not a credit counselor, a lender or a debt settlement firm, and it offers no financial product of any kind. This profile explains how the program works, what happens at a meeting, what it can and cannot do for your debt, and how it compares with the regulated options.
What Debtors Anonymous is
Debtors Anonymous, usually shortened to DA, grew out of Alcoholics Anonymous. A group of AA members in New York began meeting in 1968 to talk about money the way they talked about drinking. The Debtors Anonymous name came later, in 1976. The fellowship now runs hundreds of registered groups across the United States and abroad, supported by a General Service Office in Needham, Massachusetts, and an annual World Service Conference.
The program treats compulsive debting as a disease rather than a math problem. The only requirement for membership, according to DA’s own literature, is a desire to stop incurring unsecured debt. Nobody checks your credit report at the door. Nobody asks how much you owe.
DA borrows its structure from AA almost wholesale: Twelve Steps, Twelve Traditions and Twelve Concepts for service. On top of those it adds its own Twelve Tools, Twelve Signposts of compulsive debting and Twelve Promises of recovery.
How DA defines debting
This is the part newcomers most often get wrong. DA does not ask members to pay off everything and live cash-only forever. It asks members to stop taking on new unsecured debt, one day at a time.
| Type of obligation | Counts as “debting” in DA | Why |
|---|---|---|
| Credit card balance you cannot pay in full | Yes | Unsecured borrowing |
| Payday loan, cash advance app, personal loan | Yes | Unsecured borrowing |
| Borrowing $20 from a friend | Yes | Unsecured, even if informal |
| Mortgage or auto loan | Generally no | Secured by collateral |
| Student loan | Members decide; often yes | Unsecured, though treated case by case |
| Paying a utility bill after the due date | Yes, in many groups | Using a creditor’s money without permission |
The “no new unsecured debt” line is why a member in DA cannot treat a payday loan or an emergency cash advance as a quick fix. The program’s answer to a cash crunch is a spending plan, a pressure relief meeting and, if needed, a request for help from people who are not creditors.
Secured debt such as a mortgage is usually considered outside the definition. Groups vary on student loans and medical bills. Members are encouraged to decide with a sponsor rather than argue the line in a meeting.
How Debtors Anonymous works
A DA meeting looks like any other twelve-step meeting. Someone reads the preamble and the Steps, a member shares their story for ten to twenty minutes, and then the floor opens for shares of about three minutes each. There is no cross-talk. Nobody gives financial advice during the meeting itself.
Meetings run in three formats: in-person at churches, libraries and community centers; by telephone conference line; and online by video. Phone and online meetings mean DA is reachable from every state, including rural areas with no local group.
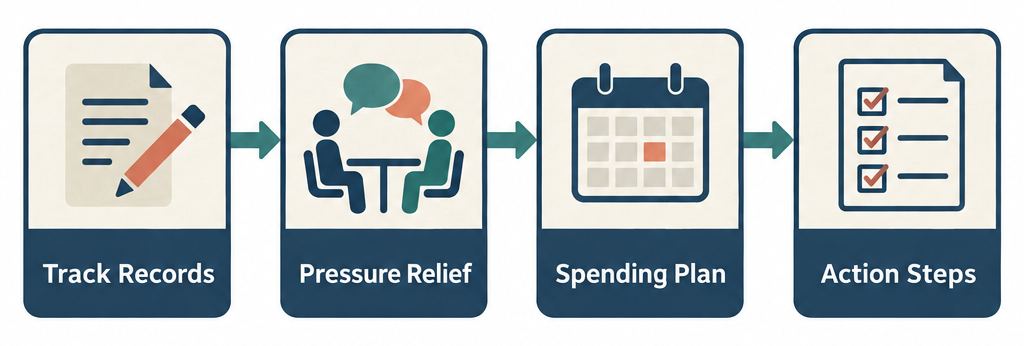
The real work happens outside the meeting through the Twelve Tools. The ones members use most are these.
| Tool | What it involves in practice |
|---|---|
| Meetings | Attending regularly, often several a week early on |
| Record maintenance | Writing down every dollar in and out, every day |
| Sponsorship | Working the Steps with a longer-term member |
| Pressure relief groups | Two experienced members review your numbers with you |
| Spending plan | A monthly plan built from your records, including savings and debt repayment |
| Telephone and internet | Calling or messaging members between meetings |
| Literature | DA pamphlets, the Twelve Steps and Twelve Traditions book, and the story collection “A Currency of Hope” |
| Awareness | Noticing vagueness, fear and avoidance around money as they happen |
| Service | Chairing meetings, treasurer duties, literature orders |
| Anonymity | No last names, no reporting who attends |
Record maintenance
New members are asked to track spending to the penny for at least thirty days before anything else. Many find this harder than the meetings. The point is to replace vagueness, which DA treats as the central symptom, with facts.
Pressure relief groups
After a stretch of records and a few weeks without new debt, a member asks two others who have been in the program longer to sit down with them. The pair review income, expenses and debts, then help draft a spending plan and an action plan. The action plan might include calling a creditor, asking for a raise, selling something or applying for a hardship program.
The two members are volunteers. They are not accountants, attorneys or licensed counselors, and DA’s literature says so plainly. Their advice carries no professional liability.
The spending plan
A DA spending plan is a monthly budget with a particular emphasis: basic needs come first, then savings, then debt repayment. The order matters. DA teaches that self-deprivation leads back to debting, so members are told not to starve themselves to pay creditors faster.
Members who owe money contact creditors with a repayment proposal they can actually keep. Creditors are under no obligation to accept it, and some do not.
What the Twelve Promises describe
The Twelve Promises are read at many meetings. In paraphrase, they describe hope replacing despair, clarity replacing vagueness, living within our means without being defined by them, a prosperous life free of fear and resentment, feeling that we are enough, fellowship replacing isolation, a sense that there is enough to share, an end to comparing ourselves with others, gratitude replacing regret, moving from denial into reality, honesty guiding our actions, and trusting a power greater than ourselves as the source of abundance.
Notice what the Promises do not say. They never promise a debt will be forgiven, a score will rise or a creditor will settle. DA is explicit that the program changes the member, not the balance sheet, and that the balance sheet follows.
What DA cannot do for your debt
Before you join
DA stops new debt from piling up but has no power over the debt already there. Interest keeps running, collectors keep calling and statutes of limitations keep ticking while you work the program, so the legal and financial side of your debt still needs handling.
DA does not negotiate with creditors, consolidate balances, lower interest rates, or stop collection calls. Those jobs belong to you, to a licensed nonprofit credit counselor, or to a bankruptcy attorney.
It also does not satisfy legal requirements. Under 11 U.S.C. § 109(h), anyone filing Chapter 7 or Chapter 13 bankruptcy must complete credit counseling from an agency approved by the U.S. Trustee Program within the 180 days before filing. DA is a fellowship, not an approved agency, so attendance does not count.
If a debt collector is contacting you, the Fair Debt Collection Practices Act still governs what they can and cannot do regardless of your DA membership. Our separate guide to what a debt collector may and may not do covers the specifics.
What the debt costs while you work the program
A spending plan has to face the interest math. Here is the same $5,000 credit card balance at a 24% APR, which is a common rate for cardholders with damaged credit, under three realistic scenarios. Interest compounds monthly at 2%.
| Scenario | Monthly payment | APR | Months to pay off | Total repaid |
|---|---|---|---|---|
| Keep card, pay $150 a month | $150 | 24% | about 56 | about $8,330 |
| DA spending plan frees $250 a month | $250 | 24% | about 26 | about $6,450 |
| Debt management plan, creditor cuts rate (illustrative) | $150 | 8% | about 38 | about $5,670 |
The math behind the first row: 24% divided by 12 is 2% a month, so the first month’s interest alone is $100 of the $150 payment. Only $50 reduces the balance. That is why minimum-style payments take years. The third row assumes a creditor concession through a nonprofit debt management plan; actual concessions vary by creditor and are never guaranteed. How card interest is calculated is covered in our piece on credit card APR explained.
The lesson DA members draw from this table is the second row. Stopping new charges and redirecting money found in the records does more than any trick.
Who DA can make sense for
The program fits people whose core problem is behavior: repeated borrowing, shopping to manage feelings, chronic vagueness about balances, or using one card to pay another. It fits people who have tried budgets and consolidation before and ended up back in the hole.
It is a weaker fit for someone whose debt came from a single event, such as a medical bill or job loss, and who simply needs a repayment structure. Those readers usually get more from a nonprofit credit counselor than from a weekly meeting.
Business owners have a dedicated branch, Business Debtors Anonymous, with the same Steps applied to cash flow and invoicing.
Free help alongside DA
Nonprofit credit counseling agencies offer free budget sessions and can propose a debt management plan.
Hardship programs from your own card issuer or servicer often lower rates without a third party.
Legal aid offices and 211 can connect you with local assistance for rent, utilities and food.
How to attend a first meeting
Finding and attending a DA meeting
- Go to the official site, debtorsanonymous.org, or call the General Service Office toll-free at 800-421-2383.
- Use the meeting finder to filter by state, phone or online.
- Pick a meeting marked open or for newcomers; some groups run beginner meetings.
- Arrive a few minutes early and tell the chair you are new.
- Collect phone numbers from a few members and start a spending record that night.
Many groups also hold a short newcomer welcome after the main meeting. You do not have to share at your first meeting.
Availability by state
DA groups exist in every state, but density varies. New York, California, Massachusetts and Illinois have the most in-person meetings. Rural states may have none, which is why the phone and video lists matter.
DA is not licensed in any state because it offers no service that triggers licensing. By contrast, nonprofit credit counselors, debt management plan providers and debt settlement companies are licensed or registered in most states through the banking or financial regulator, and many states cap the fees a debt management plan can charge. Before paying anyone for debt help, check your state regulator’s license lookup. Debt settlement companies that sell by phone are also covered by the FTC’s Telemarketing Sales Rule, 16 CFR 310.4(a)(5), which bans advance fees before a debt is actually settled.
DA compared with other debt help
| Option | Cost | Regulated by | Changes your debt | Best for |
|---|---|---|---|---|
| Debtors Anonymous | Free, optional contributions | None, self-governed | No | Behavior change, support |
| Nonprofit credit counseling and DMP | Free counseling; state-capped DMP fees | State regulators, IRS nonprofit rules | Yes, through creditor concessions | Unsecured debt with steady income |
| Debt settlement company | Percentage of enrolled debt | FTC Telemarketing Sales Rule, state laws | Yes, with credit damage | Last resort before bankruptcy |
| Bankruptcy attorney | Court filing fee plus attorney fees | Federal bankruptcy court | Yes, discharge or repayment | Debt beyond ability to repay |
| Underearners Anonymous | Free | None, self-governed | No | Income and time problems |
Readers under heavy collection pressure can use DA and a licensed counselor at the same time. Members frequently do.
Your rights while you work the program
Joining DA changes nothing about your legal protections, and it helps to know them while working a spending plan.
Under the Fair Debt Collection Practices Act, third-party collectors cannot call before 8 a.m. or after 9 p.m. in your time zone, cannot threaten action they do not intend to take, and must stop contacting you at a given address or number if you tell them in writing. Under the Fair Credit Reporting Act, you can dispute inaccurate accounts with the credit bureaus, which must investigate, generally within 30 days. The Truth in Lending Act and Regulation Z require card issuers to show you the APR and the minimum-payment payoff time on every statement, which is useful data for a spending record.
Complaints about collectors, card issuers or counseling firms go to the CFPB complaint portal. Suspected scams go to the FTC at ReportFraud. Any group that charges a fee, promises to erase debt or asks for payment before delivering a result is not DA and should be reported.
FAQ
Is Debtors Anonymous legit?
Yes. DA is a long-running nonprofit fellowship, organized since 1976 under that name, with a General Service Board, published literature and a public meeting directory. It charges nothing and sells nothing beyond literature at cost. The caution is about scope: it is peer support, not professional advice, and its volunteers carry no license or liability.
What are the 12 Promises of Debtors Anonymous?
The Promises describe the changes members report after working the Steps: hope replacing despair, clarity replacing vagueness, living within our means, prosperity without fear or resentment, self-worth, fellowship, a sense of enough, freedom from comparison, gratitude, honesty, living in reality rather than denial, and trust in a higher power as the source of abundance. None of them promises a specific financial outcome.
What is the difference between Debtors Anonymous and Underearners Anonymous?
DA focuses on stopping unsecured debt. Underearners Anonymous, founded in 2005, focuses on the habit of earning less than you need and on frittering away time, a pattern its members describe as being “time drunk.” Many people attend both. If your bills are covered but your income keeps falling short of your skills, UA addresses that more directly.
What are 12 signs of compulsive debting?
DA’s Twelve Signposts, paraphrased: vagueness about your balances and obligations; borrowing small items and money without returning them; poor saving habits and surprise at predictable bills; compulsive shopping and unused purchases; struggling to meet basic obligations; feeling more “grown up” when buying on credit than with cash; living in money chaos, such as paying one card with another; living on the edge with no insurance or paycheck to paycheck; embarrassment in normal money conversations; overworking or underearning; self-deprivation to pay creditors; and a quiet belief that someone will bail you out.
Does DA cost anything?
No. There are no dues or fees. Meetings pass a basket for voluntary contributions under the Seventh Tradition, usually a dollar or two, to cover rent and literature. Nobody is turned away for giving nothing.
Can I use DA and a debt management plan at the same time?
Yes, and many members do. DA handles the behavior; the counselor handles the creditors. The spending plan you build in DA should include the DMP payment as a fixed line item.
Laws and regulations referenced
- Truth in Lending Act, 15 U.S.C. 1601
- Regulation Z, 12 CFR Part 1026
- Fair Debt Collection Practices Act, 15 U.S.C. 1692
- Fair Credit Reporting Act, 15 U.S.C. 1681
- Bankruptcy Code, Chapter 13, 11 U.S.C. 1301
Links go to the official text on government sites.
Check, verify or complain
Sources
- debtorsanonymous.org › contact us debtorsanonymous.org
- codes.findlaw.com › us › title 11 bankruptcy › 11 usc sect 109 codes.findlaw.com
- debtorsanonymous.org › getting started › faq frequently asked questions debtorsanonymous.org
- ebsco.com › research starters › health and medicine › debtors anonymous ebsco.com

Marcus covers credit scores, credit reports and getting out of debt: consolidation, nonprofit counseling, settlement and what debt collectors may and may not do. He works from the federal laws that apply, CFPB guidance and the credit bureaus' published rules.