Author: Marcus Bell

  • Credit cards for bad credit and what to expect

    Credit cards for bad credit and what to expect

    You can get a credit card with a FICO score under 580, and the cheapest route is almost always a secured card with no annual fee and a $200 deposit. Unsecured cards marketed to people with bad credit usually cost $75 to $200 or more in first-year fees for a $300 limit, and the fees eat part of that limit before you spend a dollar. This ranking puts the lowest-cost options first and explains what each one really charges, what the law caps, and how to use any of them to move your score up.

    Bad credit FICO range300 to 579
    Cheapest optionno-fee secured card
    Typical starting deposit or limit$200 to $300
    Unsecured first-year fees$75 to $200 plus
    Federal fee cap25% of initial limit

    Before you apply

    The biggest risk with a bad-credit card is paying for credit you barely get: a card with a $300 limit and $170 in year-one fees leaves you $130 to spend and a new bill to miss. A missed payment on a card meant to rebuild your credit does more damage than having no card at all.

    What “bad credit” means to a card issuer

    Issuers do not use the phrase “bad credit” in their underwriting. They use score bands and the details inside your credit reports. FICO, whose scores most card issuers pull, publishes these ranges on its own site. VantageScore, used by many free score apps, labels the bands differently, which is why your “free score” and the score an issuer sees can land in different categories.

    Score band FICO 8 range VantageScore 4.0 range What card issuers typically offer
    Poor / Very Poor 300 to 579 300 to 600 Secured cards, high-fee unsecured cards
    Fair 580 to 669 601 to 660 Secured cards, some no-fee unsecured starter cards
    Good 670 to 739 661 to 780 Most mainstream cards
    Very Good / Excellent 740 to 850 781 to 850 Premium rewards cards, lowest APRs

    The score is only half the story. Two people with a 560 can get very different answers. A 560 caused by a single charged-off account from four years ago reads differently from a 560 with three accounts 60 days late right now. Issuers also look at recent inquiries, open collections, bankruptcy dates and whether you have any history at all. Someone with no credit file is a different case from someone with damaged credit, even though both get pushed toward the same cards.

    Under Regulation Z (12 CFR 1026.51), an issuer must also consider your ability to make the required minimum payments before opening the account. That is why every application asks for income. You can include income you have “reasonable expectation of access to,” which for most adults means wages, benefits, retirement income and, if you are 21 or older, a spouse’s or partner’s income you regularly use.

    The ranking, cheapest first

    We ranked by total first-year cost for a cardholder who pays in full, then by what happens if you carry a balance, then by how the card helps you move on to something better. Every option below reports to all three national credit bureaus. If a card does not report to Equifax, Experian and TransUnion, it cannot rebuild your credit, no matter what the marketing says.

    1. Secured cards with no annual fee

    A secured card holds a cash deposit as collateral. Your deposit normally becomes your credit limit. Put down $200, get a $200 limit. The deposit sits in an account at the bank and comes back to you when you close the card in good standing or when the issuer “graduates” you to an unsecured card.

    Discover’s published terms for the Discover it Secured list no annual fee, a $200 minimum deposit, 2% cash back at gas stations and restaurants on up to $1,000 in combined purchases each quarter, 1% on everything else, and automatic account reviews beginning at seven months to see if you qualify to get your deposit back. Capital One’s Quicksilver Secured, by the issuer’s disclosure, carries no annual fee, a $200 deposit and 1.5% cash back on purchases. Both carry variable purchase APRs near 30% at the time of writing, which only matters if you carry a balance.

    Strengths: zero fees if you pay in full, a deposit you get back, rewards on a card that most people with a 520 can qualify for, and a built-in path to an unsecured card from the same issuer.

    Weaknesses: you need $200 in cash you can live without, the APR is high, and Discover and Capital One still check your credit report. A recent bankruptcy that has not been discharged, or an unpaid balance owed to the same issuer from a prior charged-off card, can get you declined even for a secured product.

    2. Secured cards with a reduced deposit

    Capital One’s Platinum Secured is the main card in this category. Capital One’s disclosure states that, depending on your creditworthiness, a deposit of $49, $99 or $200 gets you an initial $200 credit limit. You can add deposits up to a $1,000 limit before the account is opened. There is no annual fee, and the issuer says it automatically considers you for a higher limit after six months.

    Strengths: the lowest cash outlay of any mainstream secured card, no annual fee, no foreign transaction fee.

    Weaknesses: no rewards, and the smaller deposit tiers are assigned by the issuer, not chosen by you. Many applicants with scores below 550 are assigned the full $200 deposit anyway.

    3. Credit union secured cards

    Credit unions are nonprofit, member-owned, and regulated by the National Credit Union Administration, which caps the interest rate federal credit unions can charge at 18% (the NCUA board has extended that temporary ceiling repeatedly; it is scheduled through at least September 2026 under the most recent extension). Many federal credit unions offer secured cards with APRs in the 12% to 18% range and no annual fee, roughly 10 to 15 percentage points below the big banks’ secured cards.

    Strengths: the lowest APR you will find anywhere in this category, plus a relationship with a lender that also offers payday alternative loans and small personal loans later.

    Weaknesses: you must qualify for membership, which can require living in a county, working for an employer, or joining an association. Credit union secured cards often have smaller rewards programs or none, and some require a $250 or $500 deposit instead of $200. Online application systems at smaller credit unions can be clunky.

    4. Deposit-free builder cards tied to a checking account

    Chime’s Credit Builder Visa works differently from a classic secured card. There is no credit check and no annual fee, and Chime states the card has no interest because you can only spend money you have already moved into the Credit Builder account. The card is issued by Stride Bank, N.A., Member FDIC. The catch is that you need a Chime Checking Account with a qualifying direct deposit of at least $200 to open it.

    Strengths: no fees, no interest, no hard inquiry, reports to all three bureaus, no fixed $200 deposit upfront.

    Weaknesses: utilization reporting is unusual. Chime reports the balance but does not report a traditional credit limit, which some scoring models treat as a zero limit and some ignore. You have to move your banking to a fintech, and if your employer’s direct deposit setup changes, so does your eligibility.

    5. No-credit-check secured cards with a small annual fee

    OpenSky’s Secured Visa does not pull your credit report at all. The issuer’s disclosure lists a $35 annual fee and a $200 minimum deposit. OpenSky also offers a Plus version with no annual fee but a $300 minimum deposit. First Progress secured cards from Synovus Bank charge annual fees in the $29 to $49 range depending on the version, with the higher-fee versions paired with lower APRs.

    Strengths: approval does not depend on your score, so these work for people with a bankruptcy that was discharged recently, a fresh charge-off, or an active collection that would block a Discover or Capital One application.

    Weaknesses: $35 to $49 a year for a card that is otherwise identical to a free secured card. You are paying the fee to skip the credit check, so only do that if you have actually been declined for the no-fee options or know your report has a recent bankruptcy.

    6. Unsecured “starter” cards with a $0 to $59 annual fee

    Mission Lane’s Visa is the clearest example here. Its published terms list an annual fee of $0 to $59, set at the time of approval based on your profile, and a variable APR in the high 20s to mid 30s. Initial limits run $300 to $1,000, and the issuer reviews accounts for limit increases after as little as seven months of on-time payments. Similar cards exist from several fintech partners of Celtic Bank, Sutton Bank and WebBank.

    Strengths: no deposit, limits that can start above $300, and some versions with no annual fee at all.

    Weaknesses: you have no control over which fee tier you get until after approval. The APR is punishing if you carry a balance, and many of these cards offer no rewards. These issuers decline more applicants in the 500 to 550 range than the secured cards do.

    7. High-fee unsecured cards for terrible credit

    This is the category where the ads say “$1,000 credit limit” and “instant approval.” The cards include Indigo and Milestone (Celtic Bank, serviced by Concora Credit), PREMIER Bankcard (First PREMIER Bank), Fortiva and Aspire (The Bank of Missouri), and Reflex, FIT and Surge (Celtic Bank, serviced by Continental Finance). Every one of them is a legitimate, licensed bank product. Every one of them is also the most expensive way to get a credit card.

    A representative fee stack, drawn from these issuers’ published cardholder agreements, looks like this:

    Fee type Typical range disclosed When it is charged
    Program or processing fee $55 to $95 one time Before the account opens, so not counted in the 25% cap
    Annual fee, year one $75 to $175 Charged to the card on opening, reduces available credit
    Annual fee, year two onward $45 to $125 Billed on the anniversary
    Monthly servicing or maintenance fee $6.25 to $12.50 per month Often waived in year one, then charged monthly
    Credit limit increase fee Up to 25% of the increase When the issuer raises your limit
    Purchase APR 29.99% to 36% On any balance carried past the due date

    Strengths: these issuers approve people the other six categories reject, including applicants with multiple active collections, a score in the 400s, or a bankruptcy in the past year.

    Weaknesses: the fees. A $300 limit with $170 in combined first-year fees is $130 of usable credit at a cost that, expressed as a percentage, would embarrass a payday loan storefront. Limit increases cost money. Customer service complaints about these issuers, in the CFPB’s public complaint database, cluster around fees the cardholder says were not clear and difficulty closing the account.

    If you are considering one of these, read the fee table in the Schumer box on the application page, add the program fee to the first-year annual fee, and subtract the total from the credit limit. That number is what the card actually lets you spend in month one.

    What a bad-credit card really costs

    The APR on these cards only bites if you carry a balance, and the fees only bite if you choose a card that has them. The table below shows four realistic first-year scenarios. The APRs are stated rates used for illustration, not a quote from any issuer.

    Scenario Amount used Fees APR and payment Interest paid Total repaid Cost of credit
    No-fee secured card, paid in full monthly $300 per month $0 29.99%, paid in full $0 $300 per month $0
    No-fee secured card, balance carried $500 once $0 29.99%, $50 per month about $83 about $583 over 12 months $83
    Unsecured starter card with $75 annual fee, balance carried $200 once $75 35.99%, $25 per month about $32 about $307 over 10 months plus $75 fee $107
    High-fee unsecured card, paid in full monthly $130 per month (what is left of a $300 limit) $95 program fee plus $75 annual fee 36%, paid in full $0 $130 per month plus $170 in fees $170

    Here is the plain-words math on the second row. A 29.99% APR means the issuer charges roughly 2.5% of your balance each month (29.99 divided by 12). On $500, that is about $12.50 in the first month. As you pay the balance down, the monthly interest shrinks, which is why the total comes to around $83 rather than $150. If you only paid the minimum, usually $25 or 3% of the balance, the payoff would stretch past three years and the interest would top $200. We walk through the full calculation in “credit card apr explained.”

    The fourth row is the one that matters for anyone searching for a credit card for the worst credit. You pay $170 to get $130 of spending room, with zero interest because you paid in full. Expressed as a percentage of the credit you actually received, that is a 131% charge in year one. A secured card gives you $300 of room for $0, and your deposit comes back.

    Cheaper options first

    A no-fee secured card from Discover, Capital One or a credit union costs nothing if you pay in full.
    Becoming an authorized user on a relative’s long-standing, low-balance card adds history for free.
    A credit union payday alternative loan, capped at 28% APR by the NCUA, covers a cash need without a fee-heavy card.

    The federal fee cap and what it leaves out

    The Credit Card Accountability Responsibility and Disclosure Act of 2009, implemented in Regulation Z at 12 CFR 1026.52(a), limits the fees an issuer can charge during the first year after an account opens to 25% of the initial credit limit. On a $300 limit, that is $75. The cap covers annual fees, monthly maintenance fees and similar account charges.

    Two gaps make the cap weaker than it sounds. First, late fees, over-the-limit fees and returned payment fees are excluded. Second, the CFPB amended the rule in 2013, after litigation brought by First Premier Bank, so that fees paid before the account opens do not count. That is why “program fees” and “processing fees” are collected before your card is issued: a $95 program fee plus a $75 annual fee on a $300 limit is legal because only the $75 lands inside the capped window.

    Late fees have their own federal rule. Regulation Z limits penalty fees to a “safe harbor” amount the CFPB adjusts for inflation, long set at $30 for a first late payment and $41 for another within six billing cycles; in March 2024 the CFPB issued a final rule cutting that safe harbor to a flat $8 for larger card issuers. The CFPB’s 2024 rule that would have cut large issuers’ late fees to $8 never took effect; a federal court in Texas vacated it in April 2025. So expect the $30 and $41 figures to apply, and expect a late payment to also raise your APR to a penalty rate on many subprime cards.

    If you or your spouse is on active duty, the Military Lending Act caps the total cost of consumer credit, including most fees, at a 36% Military Annual Percentage Rate. Several of the high-fee cards in category seven cannot be sold to covered borrowers on their standard terms. Issuers check the Defense Department’s database at application, but it never hurts to ask.

    The credit limit you will actually get

    Advertised limits are ceilings, not promises. In practice:

    • Secured cards: your deposit, usually $200 to $1,000, with some issuers allowing up to $2,500 or $5,000 if you can fund it.
    • Unsecured starter cards: $300 to $1,000 at opening, with $300 to $500 most common for scores under 580.
    • High-fee unsecured cards: $300 to $700 at opening. The “$1,000 credit limit” in the card’s name is a maximum reached after fee-paid increases and on-time history.

    The limit matters for your score because of utilization, the share of your available credit you are using. Scoring models reward balances under about 30% of the limit, and the best outcomes show up under 10%. On a $300 limit, that means keeping the reported balance under $90, and ideally under $30. The reported balance is whatever shows on your statement date, not what you owe at the due date. Paying most of the balance a few days before the statement closes keeps the reported number low even if you use the card heavily during the month.

    Graduation is the other reason limits matter. Discover reviews secured accounts from month seven. Capital One reviews Platinum Secured accounts at six months. Mission Lane reviews at seven months. An unsecured graduation from the same issuer gets you a higher limit without a new hard inquiry, and it keeps the account’s age, which is worth more to your score than a brand-new card.

    Using the card to raise your score
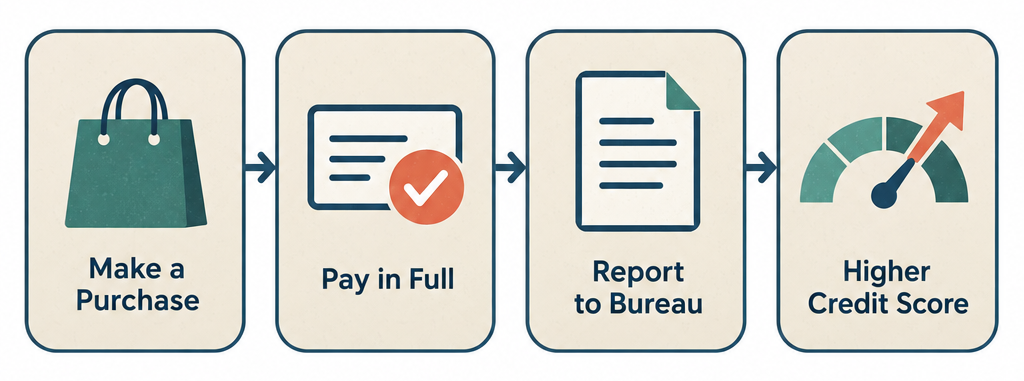
    Flow diagram showing four steps to rebuild credit: make small purchase, pay in full, bureau reports, score improves

    Payment history is 35% of a FICO score and utilization is about 30%, so a rebuilding card has exactly two jobs: pay on time every month, and keep the balance low. Everything else is optional.

    A rebuilding routine that works

    1. Set up autopay for at least the minimum the day the account opens, so a forgotten due date can never create a late mark.
    2. Put one small recurring charge on the card, such as a $15 streaming subscription, and nothing else for the first three months.
    3. Pay the full statement balance each month. Interest on these cards runs 25% to 36%, so carrying a balance costs more than any reward earns.
    4. Pull your free reports at AnnualCreditReport.com, which the Fair Credit Reporting Act entitles you to weekly, and confirm the new account appears at all three bureaus with the correct limit.
    5. At month six or seven, ask the issuer about a limit increase or graduation before applying anywhere else.

    Do not apply for three or four cards in a week hoping one sticks. Each application creates a hard inquiry, and FICO says a single inquiry typically costs fewer than five points, but a cluster of them on a thin, damaged file reads as desperation to the next underwriter. Pick the one card you are most likely to get, usually a secured card, and stop there.

    State availability and where to look

    Secured cards from Discover, Capital One and the big banks are offered in all 50 states and the District of Columbia. Credit union cards depend on the credit union’s field of membership, which can be a single county. Fintech-partnered cards sometimes exclude a handful of states; the exclusions appear in fine print on the application page, and they shift as issuers change bank partners, so check the current page rather than a review.

    The high-fee unsecured issuers in category seven route their cards through banks chartered in Utah, South Dakota and Missouri, states with no usury cap, which under federal law lets the bank export its home-state rate nationwide. That is why a 36% APR card can be sold to you in a state that caps small loan rates at 18%. Your state’s cap on a payday loan does not apply to a bank-issued credit card.

    If you were turned down everywhere, your state regulator’s license lookup, the FDIC’s BankFind tool and NMLS Consumer Access are the right places to confirm that any issuer you have not heard of is a real, supervised bank or a licensed partner before you share a Social Security number.

    Your rights as a bad-credit cardholder

    The same federal laws cover a $300 subprime card and a $30,000 premium card.

    Under the Truth in Lending Act and Regulation Z (12 CFR 1026), the issuer must give you the Schumer box before you apply, 45 days’ notice before raising your APR or fees on an existing account, and the right to reject a rate increase and pay off the balance under the old terms. The issuer cannot raise the APR on an existing balance in the first year unless you are 60 days late, and it must apply payments above the minimum to the highest-rate balance first.

    Under the Equal Credit Opportunity Act, a denial must come with a written adverse action notice within 30 days that states the specific reasons, such as “delinquent past or present credit obligations” or “insufficient income.” Under the Fair Credit Reporting Act, that notice must also tell you which bureau’s report was used, give you the score the issuer saw, and remind you that you can get a free copy of that report within 60 days. Read those reasons. They tell you exactly what to fix.

    Under the Electronic Fund Transfer Act and Regulation E, if you set up autopay from a checking account, you can stop a recurring debit by notifying your bank at least three business days before the scheduled date, and the issuer cannot condition approval on autopay.

    If an account charges off and goes to a debt collector, the Fair Debt Collection Practices Act controls how that collector can contact you, what it must disclose, and your right to dispute the debt in writing within 30 days of its first notice. We cover the details in “debt collector.”

    Complaints go to the CFPB’s consumer complaint portal, which forwards them to the issuer and requires a response within 15 days in most cases. For a suspected scam, the FTC’s ReportFraud site and the FBI’s IC3 portal take reports.

    Red flags that separate a card from a scam

    Every legitimate card for low credit scores is issued by an FDIC-insured bank or an NCUA-insured credit union, and that name appears in the Schumer box. Watch for these signs that something is wrong:

    • Any request for a fee paid by gift card, wire, cash app or crypto before approval. Real issuers charge program fees to the card or to a debit card after approval.
    • “Guaranteed approval” paired with a request for your Social Security number before you see any terms. The same language shows up in “urgent loans guaranteed approval” marketing for a reason.
    • A card that does not name its issuing bank, or names a bank you cannot find in FDIC BankFind.
    • A “card” that only works at one online store, sometimes called a merchandise or catalog card. These rarely report to the bureaus in a way that helps.
    • A monthly “credit repair” subscription bundled with the application. Under the Credit Repair Organizations Act, a credit repair firm cannot collect payment before it has performed the service.

    FAQ

    What is the easiest card to get with bad credit?

    A no-credit-check secured card is the easiest, because approval depends on your deposit rather than your score. OpenSky and Chime’s Credit Builder fall into that group, and OpenSky charges $35 a year for the privilege. The easiest card with a credit check is usually a secured card from Capital One or Discover, which approve many applicants in the 500 to 580 range who do not have a pending bankruptcy or a prior charge-off with the same bank.

    Can I get a $1,000 credit card with bad credit?

    Yes, through a secured card where you deposit $1,000; Capital One’s Platinum Secured allows deposits up to that amount before opening. Some unsecured cards that put “$1,000 credit limit” in their name, such as the Milestone Mastercard $1,000 Credit Limit, open at the full $1,000 for approved applicants, while others, such as the Surge Mastercard, open anywhere from $300 to $1,000 and carry an annual fee that can equal 25% of the minimum $300 limit. If you need $1,000 of credit on day one with a score under 580, the deposit route is the only reliable one.

    What credit card can I get with a 500 score?

    A 500 FICO score sits at the low end of the “poor” band. Realistic options are secured cards (Discover it Secured, Capital One Platinum Secured, a credit union secured card), no-credit-check secured cards (OpenSky), deposit-free builder cards (Chime Credit Builder), and the high-fee unsecured cards from issuers such as First PREMIER Bank and Celtic Bank. Mainstream unsecured cards and most no-fee starter cards decline at 500. If there is a recent bankruptcy or an unpaid charge-off on your report, start with the no-credit-check secured options.

    How to get $2,000 dollars fast with bad credit?

    A credit card is the wrong tool for this. No bad-credit card opens with a $2,000 limit unless you deposit $2,000, and cash advances on these cards carry fees of 3% to 5% plus interest from day one. Safer routes for a cash need: a credit union payday alternative loan ($200 to $2,000, APR capped at 28% by NCUA rule, membership required), a hardship plan or advance from your employer, a no-fee earned wage access app, a nonprofit credit counseling agency’s hardship referral, or local assistance through 211. A payday loan will produce $2,000 only in a handful of states and at APRs near 400%, so it belongs at the bottom of the list.

    Will a secured card hurt my score when I open it?

    The hard inquiry can shave a few points for a few months, and a brand-new account lowers your average account age. Both effects are small and fade. Within six months of on-time payments and low reported balances, most people with damaged credit see a net gain, because the new positive history and lower utilization outweigh the inquiry.

    Should I close a high-fee card once I qualify for something better?

    Usually yes, once the better card is open and you have confirmed it is reporting. The high-fee card’s annual and monthly fees will keep arriving, and the account’s age, typically a year or two at that point, is not worth $100 or more a year to preserve. Pay the balance to zero, call to close, get the closure confirmed in writing, and check your reports 60 days later to make sure it shows as “closed by consumer” with a zero balance.
  • Debtors Anonymous and how the support program works

    Debtors Anonymous and how the support program works

    Debtors Anonymous is a free, member-run twelve-step fellowship for people who cannot stop borrowing or spending money they do not have. It is not a credit counselor, a lender or a debt settlement firm, and it offers no financial product of any kind. This profile explains how the program works, what happens at a meeting, what it can and cannot do for your debt, and how it compares with the regulated options.

    Founded1968, New York City
    CostFree, voluntary contributions
    Core goalNo new unsecured debt
    FormatIn-person, phone, online
    OversightMember-run nonprofit, not a regulated service

    What Debtors Anonymous is

    Debtors Anonymous, usually shortened to DA, grew out of Alcoholics Anonymous. A group of AA members in New York began meeting in 1968 to talk about money the way they talked about drinking. The Debtors Anonymous name came later, in 1976. The fellowship now runs hundreds of registered groups across the United States and abroad, supported by a General Service Office in Needham, Massachusetts, and an annual World Service Conference.

    The program treats compulsive debting as a disease rather than a math problem. The only requirement for membership, according to DA’s own literature, is a desire to stop incurring unsecured debt. Nobody checks your credit report at the door. Nobody asks how much you owe.

    DA borrows its structure from AA almost wholesale: Twelve Steps, Twelve Traditions and Twelve Concepts for service. On top of those it adds its own Twelve Tools, Twelve Signposts of compulsive debting and Twelve Promises of recovery.

    How DA defines debting

    This is the part newcomers most often get wrong. DA does not ask members to pay off everything and live cash-only forever. It asks members to stop taking on new unsecured debt, one day at a time.

    Type of obligation Counts as “debting” in DA Why
    Credit card balance you cannot pay in full Yes Unsecured borrowing
    Payday loan, cash advance app, personal loan Yes Unsecured borrowing
    Borrowing $20 from a friend Yes Unsecured, even if informal
    Mortgage or auto loan Generally no Secured by collateral
    Student loan Members decide; often yes Unsecured, though treated case by case
    Paying a utility bill after the due date Yes, in many groups Using a creditor’s money without permission

    The “no new unsecured debt” line is why a member in DA cannot treat a payday loan or an emergency cash advance as a quick fix. The program’s answer to a cash crunch is a spending plan, a pressure relief meeting and, if needed, a request for help from people who are not creditors.

    Secured debt such as a mortgage is usually considered outside the definition. Groups vary on student loans and medical bills. Members are encouraged to decide with a sponsor rather than argue the line in a meeting.

    How Debtors Anonymous works

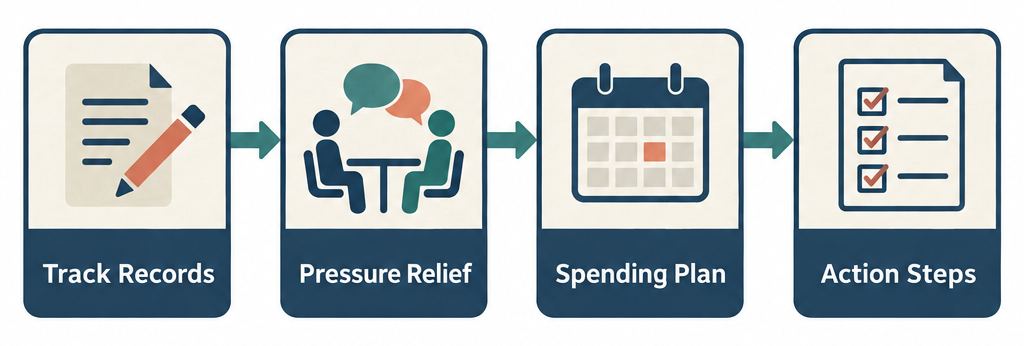
    Flow diagram showing the four-stage DA program process: Track Records, Pressure Relief, Spending Plan, Action Steps

    A DA meeting looks like any other twelve-step meeting. Someone reads the preamble and the Steps, a member shares their story for ten to twenty minutes, and then the floor opens for shares of about three minutes each. There is no cross-talk. Nobody gives financial advice during the meeting itself.

    Meetings run in three formats: in-person at churches, libraries and community centers; by telephone conference line; and online by video. Phone and online meetings mean DA is reachable from every state, including rural areas with no local group.

    The real work happens outside the meeting through the Twelve Tools. The ones members use most are these.

    Tool What it involves in practice
    Meetings Attending regularly, often several a week early on
    Record maintenance Writing down every dollar in and out, every day
    Sponsorship Working the Steps with a longer-term member
    Pressure relief groups Two experienced members review your numbers with you
    Spending plan A monthly plan built from your records, including savings and debt repayment
    Telephone and internet Calling or messaging members between meetings
    Literature DA pamphlets, the Twelve Steps and Twelve Traditions book, and the story collection “A Currency of Hope”
    Awareness Noticing vagueness, fear and avoidance around money as they happen
    Service Chairing meetings, treasurer duties, literature orders
    Anonymity No last names, no reporting who attends

    Record maintenance

    New members are asked to track spending to the penny for at least thirty days before anything else. Many find this harder than the meetings. The point is to replace vagueness, which DA treats as the central symptom, with facts.

    Pressure relief groups

    After a stretch of records and a few weeks without new debt, a member asks two others who have been in the program longer to sit down with them. The pair review income, expenses and debts, then help draft a spending plan and an action plan. The action plan might include calling a creditor, asking for a raise, selling something or applying for a hardship program.

    The two members are volunteers. They are not accountants, attorneys or licensed counselors, and DA’s literature says so plainly. Their advice carries no professional liability.

    The spending plan

    A DA spending plan is a monthly budget with a particular emphasis: basic needs come first, then savings, then debt repayment. The order matters. DA teaches that self-deprivation leads back to debting, so members are told not to starve themselves to pay creditors faster.

    Members who owe money contact creditors with a repayment proposal they can actually keep. Creditors are under no obligation to accept it, and some do not.

    What the Twelve Promises describe

    The Twelve Promises are read at many meetings. In paraphrase, they describe hope replacing despair, clarity replacing vagueness, living within our means without being defined by them, a prosperous life free of fear and resentment, feeling that we are enough, fellowship replacing isolation, a sense that there is enough to share, an end to comparing ourselves with others, gratitude replacing regret, moving from denial into reality, honesty guiding our actions, and trusting a power greater than ourselves as the source of abundance.

    Notice what the Promises do not say. They never promise a debt will be forgiven, a score will rise or a creditor will settle. DA is explicit that the program changes the member, not the balance sheet, and that the balance sheet follows.

    What DA cannot do for your debt

    Before you join

    DA stops new debt from piling up but has no power over the debt already there. Interest keeps running, collectors keep calling and statutes of limitations keep ticking while you work the program, so the legal and financial side of your debt still needs handling.

    DA does not negotiate with creditors, consolidate balances, lower interest rates, or stop collection calls. Those jobs belong to you, to a licensed nonprofit credit counselor, or to a bankruptcy attorney.

    It also does not satisfy legal requirements. Under 11 U.S.C. ยง 109(h), anyone filing Chapter 7 or Chapter 13 bankruptcy must complete credit counseling from an agency approved by the U.S. Trustee Program within the 180 days before filing. DA is a fellowship, not an approved agency, so attendance does not count.

    If a debt collector is contacting you, the Fair Debt Collection Practices Act still governs what they can and cannot do regardless of your DA membership. Our separate guide to what a debt collector may and may not do covers the specifics.

    What the debt costs while you work the program

    A spending plan has to face the interest math. Here is the same $5,000 credit card balance at a 24% APR, which is a common rate for cardholders with damaged credit, under three realistic scenarios. Interest compounds monthly at 2%.

    Scenario Monthly payment APR Months to pay off Total repaid
    Keep card, pay $150 a month $150 24% about 56 about $8,330
    DA spending plan frees $250 a month $250 24% about 26 about $6,450
    Debt management plan, creditor cuts rate (illustrative) $150 8% about 38 about $5,670

    The math behind the first row: 24% divided by 12 is 2% a month, so the first month’s interest alone is $100 of the $150 payment. Only $50 reduces the balance. That is why minimum-style payments take years. The third row assumes a creditor concession through a nonprofit debt management plan; actual concessions vary by creditor and are never guaranteed. How card interest is calculated is covered in our piece on credit card APR explained.

    The lesson DA members draw from this table is the second row. Stopping new charges and redirecting money found in the records does more than any trick.

    Who DA can make sense for

    The program fits people whose core problem is behavior: repeated borrowing, shopping to manage feelings, chronic vagueness about balances, or using one card to pay another. It fits people who have tried budgets and consolidation before and ended up back in the hole.

    It is a weaker fit for someone whose debt came from a single event, such as a medical bill or job loss, and who simply needs a repayment structure. Those readers usually get more from a nonprofit credit counselor than from a weekly meeting.

    Business owners have a dedicated branch, Business Debtors Anonymous, with the same Steps applied to cash flow and invoicing.

    Free help alongside DA

    Nonprofit credit counseling agencies offer free budget sessions and can propose a debt management plan.
    Hardship programs from your own card issuer or servicer often lower rates without a third party.
    Legal aid offices and 211 can connect you with local assistance for rent, utilities and food.

    How to attend a first meeting

    Finding and attending a DA meeting

    1. Go to the official site, debtorsanonymous.org, or call the General Service Office toll-free at 800-421-2383.
    2. Use the meeting finder to filter by state, phone or online.
    3. Pick a meeting marked open or for newcomers; some groups run beginner meetings.
    4. Arrive a few minutes early and tell the chair you are new.
    5. Collect phone numbers from a few members and start a spending record that night.

    Many groups also hold a short newcomer welcome after the main meeting. You do not have to share at your first meeting.

    Availability by state

    DA groups exist in every state, but density varies. New York, California, Massachusetts and Illinois have the most in-person meetings. Rural states may have none, which is why the phone and video lists matter.

    DA is not licensed in any state because it offers no service that triggers licensing. By contrast, nonprofit credit counselors, debt management plan providers and debt settlement companies are licensed or registered in most states through the banking or financial regulator, and many states cap the fees a debt management plan can charge. Before paying anyone for debt help, check your state regulator’s license lookup. Debt settlement companies that sell by phone are also covered by the FTC’s Telemarketing Sales Rule, 16 CFR 310.4(a)(5), which bans advance fees before a debt is actually settled.

    DA compared with other debt help

    Option Cost Regulated by Changes your debt Best for
    Debtors Anonymous Free, optional contributions None, self-governed No Behavior change, support
    Nonprofit credit counseling and DMP Free counseling; state-capped DMP fees State regulators, IRS nonprofit rules Yes, through creditor concessions Unsecured debt with steady income
    Debt settlement company Percentage of enrolled debt FTC Telemarketing Sales Rule, state laws Yes, with credit damage Last resort before bankruptcy
    Bankruptcy attorney Court filing fee plus attorney fees Federal bankruptcy court Yes, discharge or repayment Debt beyond ability to repay
    Underearners Anonymous Free None, self-governed No Income and time problems

    Readers under heavy collection pressure can use DA and a licensed counselor at the same time. Members frequently do.

    Your rights while you work the program

    Joining DA changes nothing about your legal protections, and it helps to know them while working a spending plan.

    Under the Fair Debt Collection Practices Act, third-party collectors cannot call before 8 a.m. or after 9 p.m. in your time zone, cannot threaten action they do not intend to take, and must stop contacting you at a given address or number if you tell them in writing. Under the Fair Credit Reporting Act, you can dispute inaccurate accounts with the credit bureaus, which must investigate, generally within 30 days. The Truth in Lending Act and Regulation Z require card issuers to show you the APR and the minimum-payment payoff time on every statement, which is useful data for a spending record.

    Complaints about collectors, card issuers or counseling firms go to the CFPB complaint portal. Suspected scams go to the FTC at ReportFraud. Any group that charges a fee, promises to erase debt or asks for payment before delivering a result is not DA and should be reported.

    FAQ

    Is Debtors Anonymous legit?

    Yes. DA is a long-running nonprofit fellowship, organized since 1976 under that name, with a General Service Board, published literature and a public meeting directory. It charges nothing and sells nothing beyond literature at cost. The caution is about scope: it is peer support, not professional advice, and its volunteers carry no license or liability.

    What are the 12 Promises of Debtors Anonymous?

    The Promises describe the changes members report after working the Steps: hope replacing despair, clarity replacing vagueness, living within our means, prosperity without fear or resentment, self-worth, fellowship, a sense of enough, freedom from comparison, gratitude, honesty, living in reality rather than denial, and trust in a higher power as the source of abundance. None of them promises a specific financial outcome.

    What is the difference between Debtors Anonymous and Underearners Anonymous?

    DA focuses on stopping unsecured debt. Underearners Anonymous, founded in 2005, focuses on the habit of earning less than you need and on frittering away time, a pattern its members describe as being “time drunk.” Many people attend both. If your bills are covered but your income keeps falling short of your skills, UA addresses that more directly.

    What are 12 signs of compulsive debting?

    DA’s Twelve Signposts, paraphrased: vagueness about your balances and obligations; borrowing small items and money without returning them; poor saving habits and surprise at predictable bills; compulsive shopping and unused purchases; struggling to meet basic obligations; feeling more “grown up” when buying on credit than with cash; living in money chaos, such as paying one card with another; living on the edge with no insurance or paycheck to paycheck; embarrassment in normal money conversations; overworking or underearning; self-deprivation to pay creditors; and a quiet belief that someone will bail you out.

    Does DA cost anything?

    No. There are no dues or fees. Meetings pass a basket for voluntary contributions under the Seventh Tradition, usually a dollar or two, to cover rent and literature. Nobody is turned away for giving nothing.

    Can I use DA and a debt management plan at the same time?

    Yes, and many members do. DA handles the behavior; the counselor handles the creditors. The spending plan you build in DA should include the DMP payment as a fixed line item.

  • Debt collectors and what they can and cannot do

    Debt collectors and what they can and cannot do

    A debt collector can call you, write to you, report the account to the credit bureaus and, in many cases, sue you. A collector cannot threaten you, lie about what you owe, call at odd hours or keep calling after you tell them in writing to stop. The Fair Debt Collection Practices Act and the CFPB’s Regulation F (12 CFR 1006) draw those lines, and this guide walks through where they fall.

    Main federal lawFair Debt Collection Practices Act
    RulebookRegulation F, 12 CFR 1006
    Call window8 a.m. to 9 p.m. your time
    Call limit7 attempts in 7 days per debt
    Dispute window30 days after validation notice
    Statutory damagesup to $1,000 per lawsuit

    What a debt collector actually is

    Under the Fair Debt Collection Practices Act (15 U.S.C. 1692a), a debt collector is any business whose main purpose is collecting debts, or that regularly collects debts owed to someone else. That covers collection agencies, debt buyers and law firms that regularly sue consumers. It does not usually cover the original creditor, meaning the bank, card issuer or hospital you first owed the money to.

    That distinction matters more than most people realize. Your card issuer calling about a late payment is a creditor, and the federal act’s conduct rules do not bind it. The same account sent to an outside agency, or sold to a debt buyer, is now in the hands of a debt collector who must follow every rule below. Some states close that gap: California’s Rosenthal Fair Debt Collection Practices Act extends most protections to original creditors as well.

    Here is how the players differ.

    Who is contacting you Do they own the debt? Covered by the FDCPA? What they typically want
    Original creditor (bank, card issuer, utility) Yes Generally no, unless using another name Payment to bring the account current
    Collection agency (contingency collector) No, works on commission for the creditor Yes Payment sent to them on the creditor’s behalf
    Debt buyer Yes, bought the account outright Yes Payment, often willing to settle for less
    Collection law firm Sometimes, usually represents a buyer or creditor Yes, if it regularly collects Payment or a court judgment

    Debt buyers deserve a closer look. They purchase charged-off accounts in bulk for a fraction of face value. The Federal Trade Commission’s 2013 study of the nine largest debt buyers found they paid an average of about 4 cents per dollar of the balance owed. A buyer holding a $5,000 account may have paid $200 for it, which explains why buyers are often open to settling well below the balance. It also explains why documentation can be thin: the FTC found buyers often received little more than a spreadsheet of names and balances.

    How an account ends up in collections

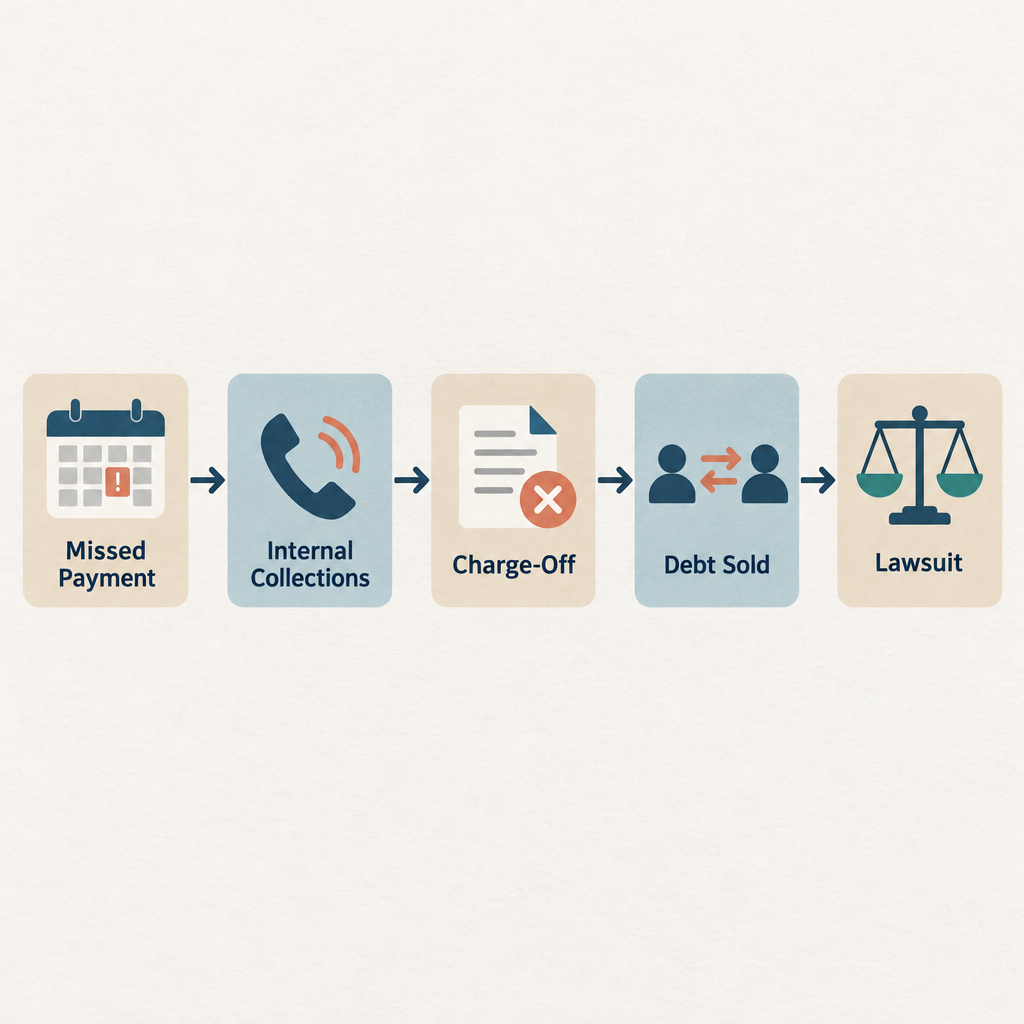
    Flow diagram showing five stages from missed payment through charge-off to debt sale to lawsuit to judgment

    Collection follows a fairly predictable timeline, and knowing where you are on it helps you plan.

    1. Delinquency. Most lenders start late fees after the due date and report a late payment to the credit bureaus once you are 30 days behind.
    2. Internal collections. For roughly the first 90 to 180 days, the creditor’s own staff call and write. These calls are not covered by the federal act.
    3. Charge-off. Credit card issuers write off the balance as a loss at about 180 days past due. Charge-off does not cancel the debt. You still owe it.
    4. Placement or sale. The creditor either hires an agency on commission or sells the account to a debt buyer. The account can be resold several times over the years.
    5. Lawsuit. If the balance justifies the cost, the collector may file suit before the state statute of limitations expires. A judgment opens the door to wage garnishment and bank levies in most states.

    What a debt collector can do

    Collectors have real tools, and ignoring them does not make those tools go away.

    • Contact you by phone, letter, email, text message and even private social media message. Regulation F, which took effect November 30, 2021, expressly allowed electronic contact as long as every message includes a simple way to opt out.
    • Call between 8 a.m. and 9 p.m. in your local time zone. Calls outside that window are presumed inconvenient and unlawful unless you agreed to them.
    • Leave a limited-content voicemail that states the caller’s name, asks you to call back and gives a number, without mentioning the debt.
    • Contact other people once to find your address or phone number. They cannot say you owe money or that they are collecting a debt.
    • Report the account to credit bureaus, but only after they have contacted you first. Regulation F (12 CFR 1006.30) bars “passive” collection, where a collector reports a debt without ever reaching out, and gives a 14-day safe harbor after sending a validation notice.
    • Charge interest and fees, but only if the original contract or state law allows them. A collector cannot invent a “collection fee” that the contract never authorized.
    • Sue you within the statute of limitations and, after winning a judgment, garnish wages or levy bank accounts within state and federal limits.

    What a debt collector cannot do

    The federal act lists prohibited practices under three headings: harassment (15 U.S.C. 1692d), false or misleading statements (1692e) and unfair practices (1692f). In plain terms, a collector cannot:

    • Call you more than seven times in seven days about one debt, or call again within seven days of having spoken with you about it. Regulation F treats more than that as presumptively harassing.
    • Call you at work after you say your employer does not allow it.
    • Contact you at all once you have sent a written request to stop, except to confirm they are stopping or to tell you they intend to take a specific action such as filing suit.
    • Contact you directly if they know a lawyer represents you on the debt.
    • Threaten arrest, jail, violence or harm to your reputation. Nonpayment of consumer debt is not a crime.
    • Threaten a lawsuit or wage garnishment they do not intend to pursue or legally cannot.
    • Claim to be a government agency, a law firm or a credit bureau when they are not.
    • Misstate the amount, add unauthorized interest or fees, or tell you a debt is yours when it is not.
    • Tell your family, friends, neighbors or coworkers about the debt.
    • Send mail with words or symbols on the envelope that reveal it comes from a collector.
    • Publish or threaten to publish a list of people who owe money.
    • Sue or threaten to sue on a debt that is past the statute of limitations. Regulation F (12 CFR 1006.26) made that an explicit violation even when the collector did not know the debt was too old.
    • Deposit a post-dated check early or accept one without proper notice.

    Contact limits at a glance

    Rule What Regulation F says
    Calling hours 8 a.m. to 9 p.m. in your local time, unless you consent otherwise
    Call frequency No more than 7 call attempts per debt in 7 consecutive days
    After a conversation No further calls about that debt for 7 days
    Email and text Allowed, must include an opt-out method, cannot use a work email they know is employer-provided
    Third parties One contact each, location information only, no mention of the debt
    Written cease request Collector must stop all contact except limited legal notices
    Attorney representation Collector must deal with the attorney, not you

    The frequency limit applies per debt. If one collector handles three of your accounts, the math allows more total calls than people expect, so track them.

    The validation notice: your 30-day window

    Within five days of first contacting you, a collector must send a validation notice. Regulation F (12 CFR 1006.34) spells out what it has to contain: the collector’s name and mailing address, the creditor’s name, an itemization date, the balance on that date, every interest, fee, payment and credit since, the current amount, your dispute rights and a tear-off response form. The CFPB publishes a model form, and most collectors now use it.

    You then have 30 days to dispute the debt or ask for the name of the original creditor. Do it in writing. If you dispute within the window, the collector must stop collecting until it mails you verification. Disputing after 30 days still has value, but the collector is not required to pause.

    What to do when a collector first contacts you

    1. Get the caller’s name, company, mailing address and phone number. Do not confirm your Social Security number or bank details.
    2. Ask for the validation notice if you have not received one. Do not pay anything until you have it.
    3. Compare the itemization with your own records. Check the creditor name, the balance and the dates.
    4. Send a written dispute within 30 days if anything looks wrong, and keep a copy with proof of mailing.
    5. Check your state’s statute of limitations before paying or promising to pay anything on an old debt.
    6. If the debt is valid, decide between full payment, a payment plan or a lump-sum settlement, and get any deal in writing before sending money.

    Time-barred debt and the statute of limitations

    Every state sets a deadline for suing over an unpaid debt. Once it passes, the debt is “time-barred.” The debt does not vanish, and a collector can still ask you to pay, but it cannot sue or threaten to sue. Typical ranges run from three to ten years, measured in most states from your last payment or last activity on the account.

    State Written contract or credit card (years) Note
    New York 3 Consumer credit transactions, since April 2022
    California 4 Code of Civil Procedure 337
    Texas 4 Civil Practice and Remedies Code 16.004
    Pennsylvania 4 Garnishment for most consumer debt is also barred
    Florida 5 Florida Statutes 95.11
    Ohio 6 Reduced from 8 years in 2021
    Illinois 5 to 10 Depends on whether the court treats the account as written or oral
    Kentucky 10 Written contracts signed after July 2014

    Check your state attorney general’s site for the current figure, because legislatures change these periods and courts sometimes classify credit cards differently.

    One trap deserves its own warning. In a number of states, a partial payment or a written promise to pay restarts the clock. A collector who asks for “just $25 to show good faith” on a nine-year-old account may be trying to revive the right to sue. Ask whether the debt is time-barred before you send anything.

    What a collection account can cost you

    A debt in collections is not a loan, but how you handle it changes the final cost dramatically. The table below walks through four ways a $5,000 charged-off credit card balance can play out. The numbers are illustrative; your contract, state law and tax situation set the real figures.

    Path What you pay Added costs Total out of pocket Other effects
    Pay in full $5,000 None, if the contract added no post-charge-off interest $5,000 Collection stays on report up to 7 years, shows paid
    Negotiate a 40% lump sum yourself $2,000 $3,000 forgiven; taxable as income unless insolvent, roughly $660 at a 22% rate About $2,660 Account shows settled; forgiven amount may bring a Form 1099-C
    Debt settlement company, 50% settlement $2,500 to collector Company fee of about 20% of the $5,000 enrolled ($1,000), plus roughly $550 tax on $2,500 forgiven About $4,050 Months of nonpayment while saving, extra credit damage, program often takes 2 to 4 years
    Ignore it and lose a lawsuit $5,000 judgment Court costs and contract attorney fees of perhaps $800, plus post-judgment interest at state rate (10% in California) Around $6,300 after a year, rising monthly Wage garnishment up to 25% of disposable pay in most states, judgment can be renewed

    The APR concept does not apply once a debt is charged off, but the judgment path behaves like a high-interest loan you never agreed to. California’s post-judgment rate is 10% a year, and some states let creditors renew judgments for a decade or longer.

    Canceled debt of $600 or more usually triggers a Form 1099-C, and the IRS treats the forgiven amount as ordinary income. IRS Publication 4681 explains the insolvency exclusion: if your debts exceeded your assets at the time of cancellation, you can exclude some or all of it using Form 982. Many people in collections qualify and never claim it.

    Before you pay or promise anything

    The biggest mistake is paying a collector before you have a validation notice, a written settlement agreement and a check of your state’s statute of limitations. A small “good faith” payment can restart the clock on a time-barred debt and give the collector the right to sue.

    Cheaper options first

    A nonprofit credit counseling agency (look for NFCC or FCAA members) can set up a debt management plan for a modest monthly fee, usually capped by state law.
    Negotiating directly with the collector costs nothing and avoids the 15% to 25% fees settlement companies charge.
    If a hardship caused the default, ask the original creditor about a hardship or re-aging program before the account is sold.

    Collections and your credit score

    Under the Fair Credit Reporting Act (15 U.S.C. 1681c), a collection account can stay on your credit report for seven years from the date the original account first went delinquent, plus 180 days. Paying it does not remove it early, though the account will show a zero balance.

    Scoring models treat paid collections differently. FICO 9, FICO 10 and VantageScore 3.0 and 4.0 ignore paid collections entirely. The older FICO 8 model, still used by many lenders, does not, though it ignores any collection with an original balance under $100.

    Medical collections follow their own path. The three nationwide bureaus removed paid medical collections, medical collections under $500 and medical collections less than a year old from reports in 2022 and 2023. The CFPB finalized a rule in January 2025 to remove the rest, but a federal court in Texas vacated that rule in July 2025. As a result, unpaid medical collections of $500 or more can still appear.

    What a collector can take after a judgment

    A judgment lets a collector ask the court for garnishment, a bank levy or a lien, depending on the state. Federal law sets a floor: Title III of the Consumer Credit Protection Act (15 U.S.C. 1673) limits garnishment for ordinary consumer debt to the lesser of 25% of your disposable earnings or the amount by which weekly disposable earnings exceed 30 times the federal minimum wage, which works out to $217.50 a week.

    States can go further. Texas, Pennsylvania, North Carolina and South Carolina bar wage garnishment for most consumer debts. Many others exempt a larger share of pay.

    Federal benefits are shielded. Social Security, SSI, VA, federal retirement and similar payments cannot be garnished for private consumer debt, and under 31 CFR Part 212 a bank must automatically protect two months’ worth of directly deposited federal benefits when it receives a garnishment order.

    State licensing and where collectors must register

    Federal law does not license collectors, but many states and some cities do. California’s Debt Collection Licensing Act, enforced by the Department of Financial Protection and Innovation, has required a license since January 1, 2022, with applications handled through NMLS. New York City requires a license from the Department of Consumer and Worker Protection. Texas requires collectors to file a surety bond with the Secretary of State. Massachusetts licenses agencies through its Division of Banks.

    You can check a company on NMLS Consumer Access, which lists state licenses for many collectors, or search your state regulator’s license lookup. A collector that is required to hold a license and does not is often barred from collecting in that state at all, which is a powerful defense if you are sued.

    “Account services” calls and collection scams

    Calls from a vague name like “account services,” “legal processing” or “resolution department” are a known pattern. Some are legitimate collectors using a trade name. Many are scammers working from leaked or purchased data. The CFPB consistently ranks debt collection among its most complained-about categories, and a large share of those complaints involve debts the consumer says they never owed.

    Red flags that point to a scam or a lawbreaking collector:

    • Refuses to mail a validation notice or give a physical address.
    • Demands payment by gift card, wire transfer, cryptocurrency or a payment app.
    • Threatens arrest, a warrant or deportation.
    • Pressures you to pay “today” to avoid a lawsuit that has supposedly already been filed.
    • Knows your name but cannot name the original creditor or the account’s open date.
    • Asks you to “confirm” your full Social Security number or bank login.

    To verify a caller, hang up and contact the original creditor using the number on an old statement to ask who holds the account. Pull your free credit reports from AnnualCreditReport.com to see whether the collector is listed. Search the company on NMLS Consumer Access and your state’s license lookup.

    Your rights and how to enforce them

    The Fair Debt Collection Practices Act gives you a private right of action. Under 15 U.S.C. 1692k, you can sue a collector within one year of a violation for actual damages, statutory damages of up to $1,000 per lawsuit, and your attorney’s fees and court costs. Because the law pays the lawyer’s fees, many consumer attorneys take these cases at no upfront cost, and the National Association of Consumer Advocates maintains a directory.

    Keep evidence. Save voicemails, screenshots of texts and emails, envelopes and letters. Log every call with the date, time, caller name and what was said. Several states let you record calls without telling the other party, while others require consent, so check your state’s rule before recording.

    Where to complain:

    • CFPB complaint portal. The bureau forwards complaints to the company, which must respond, and uses the data for enforcement.
    • FTC ReportFraud. Especially for scam collectors and fake debts.
    • Your state attorney general and, where the collector is licensed, the state licensing regulator.
    • FBI IC3 if the “collector” obtained money through fraud.

    If you are on active military duty, the Servicemembers Civil Relief Act adds protections, including a cap on interest for debts incurred before service and the right to seek a stay of civil proceedings.

    FAQ

    Can a debt collector call my family or my employer?

    A collector may contact other people only to locate you, once each, and cannot mention the debt. Calls to your employer must stop once you say the employer forbids them. Repeated calls to relatives, or any disclosure of the debt to them, violate the federal act.

    Does a debt collector have to prove I owe the money?

    After a timely written dispute, the collector must stop collecting until it sends verification, which is usually a copy of a statement or the signed agreement. In court, the burden is on the collector to prove ownership and the amount. Debt buyers with thin records sometimes drop cases when a consumer insists on proof.

    What happens if I never respond to a debt collector?

    The collector can keep contacting you within the legal limits, report the account and sue before the statute of limitations runs out. If you ignore a lawsuit, the court will usually enter a default judgment for the full amount plus costs. Responding, even just to dispute, is almost always better than silence.

    Can a debt collector contact me on social media?

    Yes, by private message only, and the message must identify the sender as a collector and include a way to opt out. Public posts, comments and friend requests that reveal the debt are prohibited under Regulation F.

    Will paying a collection remove it from my credit report?

    No. The account stays for up to seven years from the original delinquency but will show a zero balance. Some collectors agree to “pay for delete,” though the bureaus discourage the practice and the CFPB has not endorsed it. Newer FICO and VantageScore models ignore paid collections, which lessens the damage.

    Is a creditor the same as a debt collector?

    No. The creditor is the company you originally owed. A debt collector is a third party collecting on the creditor’s behalf or a buyer that purchased the account. Federal collection rules apply to the collector, not the original creditor, though several states, including California, cover both.