PROPOSEDConsumer alert, published October 19, 2026
The House Committee on Ways and Means voted 38 to 5 on 09/16/2026 to advance H.R. 10357, the Digital Asset Tax Certainty Act, according to Congress.gov. The bill would create a voluntary disclosure program for people who failed to report or misreported crypto in past tax years. It is a proposal only. It has not passed the House or the Senate and is not law.
What changed
Rep. Jason Smith (R-MO-8), who chairs Ways and Means, introduced H.R. 10357 on 09/14/2026. Congress.gov lists 8 cosponsors from both parties, including Rep. Horsford (D-NV). The bill was referred to Ways and Means.
Two days later, on 09/16/2026, the committee held its markup. Congress.gov records that the bill was “Ordered to be Reported in the Nature of a Substitute by the Yeas and Nays: 38 – 5.” That means the committee approved an amended version, not the original text.
In a press release dated 09/16/2026, Ways and Means said the bill would give Americans who own, trade and use crypto greater tax certainty and fewer compliance burdens. The committee’s posted substitute includes a section titled “Establishment of Digital Asset Voluntary Disclosure Program.”
The introduced bill text, published by GovInfo with a date of 09/14/2026, describes how that program would work. For violations properly disclosed under it, Treasury “shall not assert” further accuracy and fraud penalties under Internal Revenue Code sections 6662 and 6663. Treasury also could not use the disclosed information to refer a taxpayer for criminal investigation or prosecution under sections 7201, 7203 or 7206 (other than paragraph (2)).
The same text gives extra protection to a “certified eligible taxpayer,” barring further section 6662 penalties for that person. It also sets a penalty of 25 percent, or 0 percent for a certified eligible taxpayer, on an aggregate amount. The portion of the text available to us cuts off before saying what that amount is.
The Joint Committee on Taxation published a description of the bill and revenue estimates (JCX-47-26 and JCX-48-26, both dated 09/14/2026) ahead of the markup.
Who it affects
The program targets taxpayers who left crypto off past returns or reported it incorrectly. Ways and Means says about 67 million Americans, or one in four, hold some crypto.
The timing matters. Tax year 2025 is the first covered by the 1099-DA broker reporting rules, with forms furnished to taxpayers in early 2026. Those rules do not reach earlier years. That gap is what the proposed program is meant to address.
Today, the only option that exists is the IRS’s current Voluntary Disclosure Practice. Cointelegraph describes it as aimed at willful violators who face criminal exposure.
What happens next
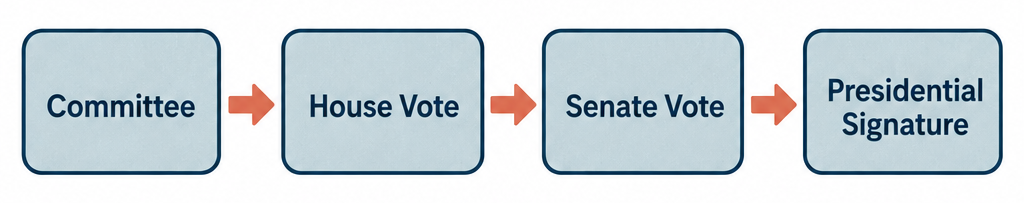
The bill still needs a vote by the full House, passage in the Senate and the President’s signature. As of 10/19/2026, Congress.gov shows none of those steps scheduled. Because the bill is not law, no effective date has been set for the disclosure program.
One other piece of the bill does carry a date. A de minimis exception for fees, with a $10 threshold according to the committee and law firm summaries, would apply to dispositions after 12/31/2027 if the bill becomes law.
This bill is separate from the Digital Asset Market Clarity Act. Dig.watch and Legis1 reported that the Senate failed a procedural vote on that bill, 49 to 50 with 60 needed, the day before the Ways and Means markup.
No crypto amnesty exists yet
Some outlets have called this the “Digital Asset Tax Clarification Act” and implied that a program is already running or that amnesty is available. Both claims are wrong. Congress.gov and GovInfo list the title as the Digital Asset Tax Certainty Act, and no program exists because the bill is not law. If anyone offers to enroll you in it now, report them to the FTC at ReportFraud.ftc.gov.
What you should do now
Do not plan around a program that may never pass, or may pass in a different form. Your obligations under current law have not changed.
If you have unreported crypto from past years, talk to a tax professional or a lawyer. They can review your own facts and the IRS options that exist today.
Keep your records. Exchange statements, wallet histories and past returns will matter under any program, current or future.
What we don’t know yet
The key details remain unconfirmed. Cointelegraph, as re-posted by crypto aggregators including Bloomingbit, KuCoin and ChainCatcher, reported that Section 502 would require Treasury to launch the program within 12 months of enactment and give taxpayers 24 months to amend returns. The same reports said certified non-willful filers who came forward in the first 12 months would pay 0 percent on the first $25,000 of underpaid tax per year and 5 percent above that.
We rate those reports grade D. Aggregators that re-post other outlets have not checked those tiers against the final committee text, and the substitute the committee adopted may differ from the original bill. A practitioner’s blog, CryptoTaxAudit by Clinton Donnelly, EA, describes a 3-year look-back for certified filers and 6 years for uncertified ones. That is one tax preparer’s reading, not an official source.
Investor Kevin O’Leary predicted in a CoinMarketCap piece, also grade D, that the crypto tax bill is moving forward. That is one public figure’s opinion. No official action backs a timeline.
Until Congress acts, the dollar tiers, deadlines and look-back periods are open questions. US Financer will update this alert when the official text or a floor vote settles them.
For the background, see our crypto scams and regulation guides.
Laws and regulations referenced
Links go to the official text on government sites.
Check, verify or complain
Sources
- Congress.gov, H.R.10357 All Info (119th Congress) congress.gov · primary source
- GovInfo, H.R. 10357 (Introduced in House), official bill text govinfo.gov · primary source
- House Committee on Ways and Means press release, 09/16/2026, and AINS PDF waysandmeans.house.gov · primary source
- Joint Committee on Taxation (Congress), JCX-47-26 / JCX-48-26 jct.gov · primary source

Leah writes US Financer's Consumer Alerts: scam warnings and money rule changes issued by federal agencies, state attorneys general, regulators and courts. Each alert starts from the official notice, says what is confirmed and what is not known yet, and lists the agency's own page…

Ruth is US Financer's standards editor. Every article goes through her checks before and after it is published: each rate, fee, cap, deadline and rule is matched against its primary source, every law named is linked to its official text, and anything that cannot be…
Comments are closed