We are not a credit repair, debt relief or debt collection company and offer no services. Rules differ by state, so confirm with the agency or a nonprofit counselor before you act.
A debt collector can call you, write to you, report the account to the credit bureaus and, in many cases, sue you. A collector cannot threaten you, lie about what you owe, call at odd hours or keep calling after you tell them in writing to stop. The Fair Debt Collection Practices Act and the CFPB’s Regulation F (12 CFR 1006) draw those lines, and this guide walks through where they fall.
What a debt collector actually is
Under the Fair Debt Collection Practices Act (15 U.S.C. 1692a), a debt collector is any business whose main purpose is collecting debts, or that regularly collects debts owed to someone else. That covers collection agencies, debt buyers and law firms that regularly sue consumers. It does not usually cover the original creditor, meaning the bank, card issuer or hospital you first owed the money to.
That distinction matters more than most people realize. Your card issuer calling about a late payment is a creditor, and the federal act’s conduct rules do not bind it. The same account sent to an outside agency, or sold to a debt buyer, is now in the hands of a debt collector who must follow every rule below. Some states close that gap: California’s Rosenthal Fair Debt Collection Practices Act extends most protections to original creditors as well.
Here is how the players differ.
| Who is contacting you | Do they own the debt? | Covered by the FDCPA? | What they typically want |
|---|---|---|---|
| Original creditor (bank, card issuer, utility) | Yes | Generally no, unless using another name | Payment to bring the account current |
| Collection agency (contingency collector) | No, works on commission for the creditor | Yes | Payment sent to them on the creditor’s behalf |
| Debt buyer | Yes, bought the account outright | Yes | Payment, often willing to settle for less |
| Collection law firm | Sometimes, usually represents a buyer or creditor | Yes, if it regularly collects | Payment or a court judgment |
Debt buyers deserve a closer look. They purchase charged-off accounts in bulk for a fraction of face value. The Federal Trade Commission’s 2013 study of the nine largest debt buyers found they paid an average of about 4 cents per dollar of the balance owed. A buyer holding a $5,000 account may have paid $200 for it, which explains why buyers are often open to settling well below the balance. It also explains why documentation can be thin: the FTC found buyers often received little more than a spreadsheet of names and balances.
How an account ends up in collections
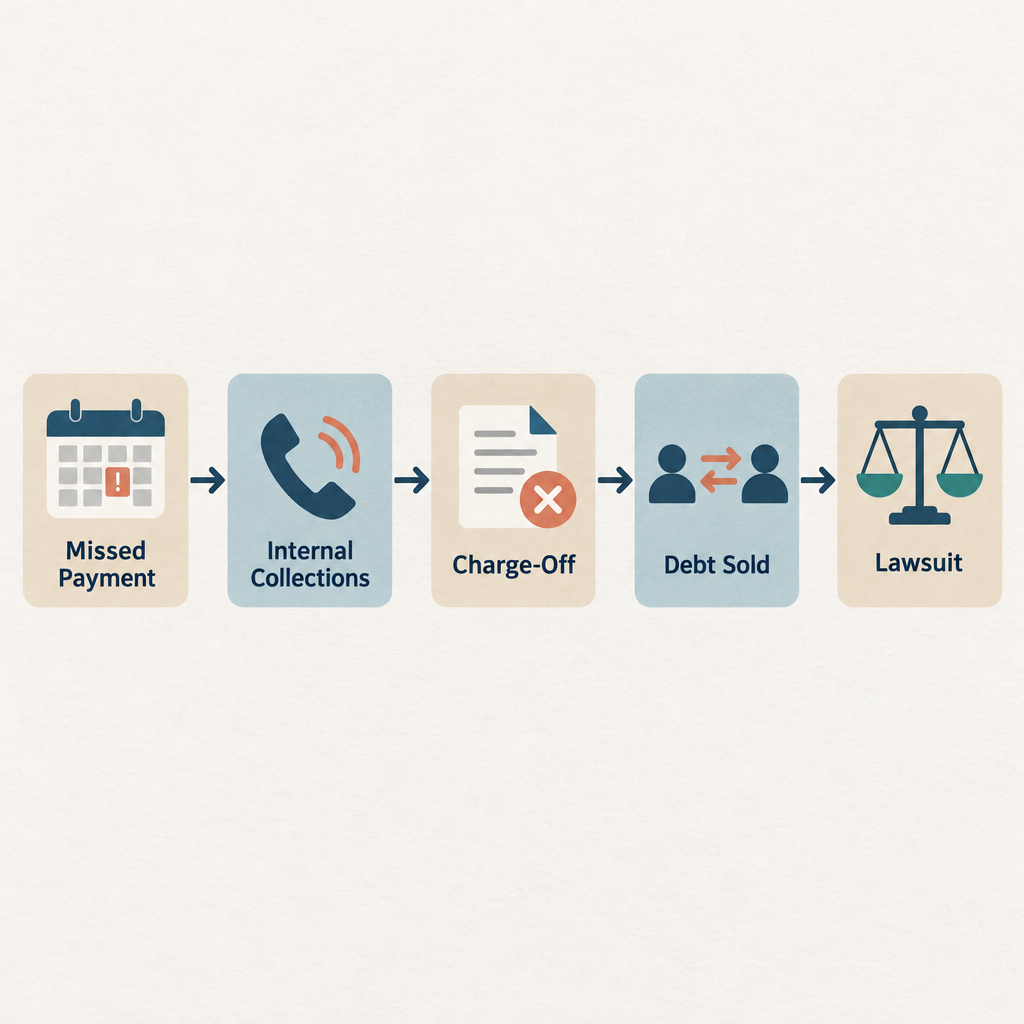
Collection follows a fairly predictable timeline, and knowing where you are on it helps you plan.
- Delinquency. Most lenders start late fees after the due date and report a late payment to the credit bureaus once you are 30 days behind.
- Internal collections. For roughly the first 90 to 180 days, the creditor’s own staff call and write. These calls are not covered by the federal act.
- Charge-off. Credit card issuers write off the balance as a loss at about 180 days past due. Charge-off does not cancel the debt. You still owe it.
- Placement or sale. The creditor either hires an agency on commission or sells the account to a debt buyer. The account can be resold several times over the years.
- Lawsuit. If the balance justifies the cost, the collector may file suit before the state statute of limitations expires. A judgment opens the door to wage garnishment and bank levies in most states.
What a debt collector can do
Collectors have real tools, and ignoring them does not make those tools go away.
- Contact you by phone, letter, email, text message and even private social media message. Regulation F, which took effect November 30, 2021, expressly allowed electronic contact as long as every message includes a simple way to opt out.
- Call between 8 a.m. and 9 p.m. in your local time zone. Calls outside that window are presumed inconvenient and unlawful unless you agreed to them.
- Leave a limited-content voicemail that states the caller’s name, asks you to call back and gives a number, without mentioning the debt.
- Contact other people once to find your address or phone number. They cannot say you owe money or that they are collecting a debt.
- Report the account to credit bureaus, but only after they have contacted you first. Regulation F (12 CFR 1006.30) bars “passive” collection, where a collector reports a debt without ever reaching out, and gives a 14-day safe harbor after sending a validation notice.
- Charge interest and fees, but only if the original contract or state law allows them. A collector cannot invent a “collection fee” that the contract never authorized.
- Sue you within the statute of limitations and, after winning a judgment, garnish wages or levy bank accounts within state and federal limits.
What a debt collector cannot do
The federal act lists prohibited practices under three headings: harassment (15 U.S.C. 1692d), false or misleading statements (1692e) and unfair practices (1692f). In plain terms, a collector cannot:
- Call you more than seven times in seven days about one debt, or call again within seven days of having spoken with you about it. Regulation F treats more than that as presumptively harassing.
- Call you at work after you say your employer does not allow it.
- Contact you at all once you have sent a written request to stop, except to confirm they are stopping or to tell you they intend to take a specific action such as filing suit.
- Contact you directly if they know a lawyer represents you on the debt.
- Threaten arrest, jail, violence or harm to your reputation. Nonpayment of consumer debt is not a crime.
- Threaten a lawsuit or wage garnishment they do not intend to pursue or legally cannot.
- Claim to be a government agency, a law firm or a credit bureau when they are not.
- Misstate the amount, add unauthorized interest or fees, or tell you a debt is yours when it is not.
- Tell your family, friends, neighbors or coworkers about the debt.
- Send mail with words or symbols on the envelope that reveal it comes from a collector.
- Publish or threaten to publish a list of people who owe money.
- Sue or threaten to sue on a debt that is past the statute of limitations. Regulation F (12 CFR 1006.26) made that an explicit violation even when the collector did not know the debt was too old.
- Deposit a post-dated check early or accept one without proper notice.
Contact limits at a glance
| Rule | What Regulation F says |
|---|---|
| Calling hours | 8 a.m. to 9 p.m. in your local time, unless you consent otherwise |
| Call frequency | No more than 7 call attempts per debt in 7 consecutive days |
| After a conversation | No further calls about that debt for 7 days |
| Email and text | Allowed, must include an opt-out method, cannot use a work email they know is employer-provided |
| Third parties | One contact each, location information only, no mention of the debt |
| Written cease request | Collector must stop all contact except limited legal notices |
| Attorney representation | Collector must deal with the attorney, not you |
The frequency limit applies per debt. If one collector handles three of your accounts, the math allows more total calls than people expect, so track them.
The validation notice: your 30-day window
Within five days of first contacting you, a collector must send a validation notice. Regulation F (12 CFR 1006.34) spells out what it has to contain: the collector’s name and mailing address, the creditor’s name, an itemization date, the balance on that date, every interest, fee, payment and credit since, the current amount, your dispute rights and a tear-off response form. The CFPB publishes a model form, and most collectors now use it.
You then have 30 days to dispute the debt or ask for the name of the original creditor. Do it in writing. If you dispute within the window, the collector must stop collecting until it mails you verification. Disputing after 30 days still has value, but the collector is not required to pause.
What to do when a collector first contacts you
- Get the caller’s name, company, mailing address and phone number. Do not confirm your Social Security number or bank details.
- Ask for the validation notice if you have not received one. Do not pay anything until you have it.
- Compare the itemization with your own records. Check the creditor name, the balance and the dates.
- Send a written dispute within 30 days if anything looks wrong, and keep a copy with proof of mailing.
- Check your state’s statute of limitations before paying or promising to pay anything on an old debt.
- If the debt is valid, decide between full payment, a payment plan or a lump-sum settlement, and get any deal in writing before sending money.
Time-barred debt and the statute of limitations
Every state sets a deadline for suing over an unpaid debt. Once it passes, the debt is “time-barred.” The debt does not vanish, and a collector can still ask you to pay, but it cannot sue or threaten to sue. Typical ranges run from three to ten years, measured in most states from your last payment or last activity on the account.
| State | Written contract or credit card (years) | Note |
|---|---|---|
| New York | 3 | Consumer credit transactions, since April 2022 |
| California | 4 | Code of Civil Procedure 337 |
| Texas | 4 | Civil Practice and Remedies Code 16.004 |
| Pennsylvania | 4 | Garnishment for most consumer debt is also barred |
| Florida | 5 | Florida Statutes 95.11 |
| Ohio | 6 | Reduced from 8 years in 2021 |
| Illinois | 5 to 10 | Depends on whether the court treats the account as written or oral |
| Kentucky | 10 | Written contracts signed after July 2014 |
Check your state attorney general’s site for the current figure, because legislatures change these periods and courts sometimes classify credit cards differently.
One trap deserves its own warning. In a number of states, a partial payment or a written promise to pay restarts the clock. A collector who asks for “just $25 to show good faith” on a nine-year-old account may be trying to revive the right to sue. Ask whether the debt is time-barred before you send anything.
What a collection account can cost you
A debt in collections is not a loan, but how you handle it changes the final cost dramatically. The table below walks through four ways a $5,000 charged-off credit card balance can play out. The numbers are illustrative; your contract, state law and tax situation set the real figures.
| Path | What you pay | Added costs | Total out of pocket | Other effects |
|---|---|---|---|---|
| Pay in full | $5,000 | None, if the contract added no post-charge-off interest | $5,000 | Collection stays on report up to 7 years, shows paid |
| Negotiate a 40% lump sum yourself | $2,000 | $3,000 forgiven; taxable as income unless insolvent, roughly $660 at a 22% rate | About $2,660 | Account shows settled; forgiven amount may bring a Form 1099-C |
| Debt settlement company, 50% settlement | $2,500 to collector | Company fee of about 20% of the $5,000 enrolled ($1,000), plus roughly $550 tax on $2,500 forgiven | About $4,050 | Months of nonpayment while saving, extra credit damage, program often takes 2 to 4 years |
| Ignore it and lose a lawsuit | $5,000 judgment | Court costs and contract attorney fees of perhaps $800, plus post-judgment interest at state rate (10% in California) | Around $6,300 after a year, rising monthly | Wage garnishment up to 25% of disposable pay in most states, judgment can be renewed |
The APR concept does not apply once a debt is charged off, but the judgment path behaves like a high-interest loan you never agreed to. California’s post-judgment rate is 10% a year, and some states let creditors renew judgments for a decade or longer.
Canceled debt of $600 or more usually triggers a Form 1099-C, and the IRS treats the forgiven amount as ordinary income. IRS Publication 4681 explains the insolvency exclusion: if your debts exceeded your assets at the time of cancellation, you can exclude some or all of it using Form 982. Many people in collections qualify and never claim it.
Before you pay or promise anything
The biggest mistake is paying a collector before you have a validation notice, a written settlement agreement and a check of your state’s statute of limitations. A small “good faith” payment can restart the clock on a time-barred debt and give the collector the right to sue.
Cheaper options first
A nonprofit credit counseling agency (look for NFCC or FCAA members) can set up a debt management plan for a modest monthly fee, usually capped by state law.
Negotiating directly with the collector costs nothing and avoids the 15% to 25% fees settlement companies charge.
If a hardship caused the default, ask the original creditor about a hardship or re-aging program before the account is sold.
Collections and your credit score
Under the Fair Credit Reporting Act (15 U.S.C. 1681c), a collection account can stay on your credit report for seven years from the date the original account first went delinquent, plus 180 days. Paying it does not remove it early, though the account will show a zero balance.
Scoring models treat paid collections differently. FICO 9, FICO 10 and VantageScore 3.0 and 4.0 ignore paid collections entirely. The older FICO 8 model, still used by many lenders, does not, though it ignores any collection with an original balance under $100.
Medical collections follow their own path. The three nationwide bureaus removed paid medical collections, medical collections under $500 and medical collections less than a year old from reports in 2022 and 2023. The CFPB finalized a rule in January 2025 to remove the rest, but a federal court in Texas vacated that rule in July 2025. As a result, unpaid medical collections of $500 or more can still appear.
What a collector can take after a judgment
A judgment lets a collector ask the court for garnishment, a bank levy or a lien, depending on the state. Federal law sets a floor: Title III of the Consumer Credit Protection Act (15 U.S.C. 1673) limits garnishment for ordinary consumer debt to the lesser of 25% of your disposable earnings or the amount by which weekly disposable earnings exceed 30 times the federal minimum wage, which works out to $217.50 a week.
States can go further. Texas, Pennsylvania, North Carolina and South Carolina bar wage garnishment for most consumer debts. Many others exempt a larger share of pay.
Federal benefits are shielded. Social Security, SSI, VA, federal retirement and similar payments cannot be garnished for private consumer debt, and under 31 CFR Part 212 a bank must automatically protect two months’ worth of directly deposited federal benefits when it receives a garnishment order.
State licensing and where collectors must register
Federal law does not license collectors, but many states and some cities do. California’s Debt Collection Licensing Act, enforced by the Department of Financial Protection and Innovation, has required a license since January 1, 2022, with applications handled through NMLS. New York City requires a license from the Department of Consumer and Worker Protection. Texas requires collectors to file a surety bond with the Secretary of State. Massachusetts licenses agencies through its Division of Banks.
You can check a company on NMLS Consumer Access, which lists state licenses for many collectors, or search your state regulator’s license lookup. A collector that is required to hold a license and does not is often barred from collecting in that state at all, which is a powerful defense if you are sued.
“Account services” calls and collection scams
Calls from a vague name like “account services,” “legal processing” or “resolution department” are a known pattern. Some are legitimate collectors using a trade name. Many are scammers working from leaked or purchased data. The CFPB consistently ranks debt collection among its most complained-about categories, and a large share of those complaints involve debts the consumer says they never owed.
Red flags that point to a scam or a lawbreaking collector:
- Refuses to mail a validation notice or give a physical address.
- Demands payment by gift card, wire transfer, cryptocurrency or a payment app.
- Threatens arrest, a warrant or deportation.
- Pressures you to pay “today” to avoid a lawsuit that has supposedly already been filed.
- Knows your name but cannot name the original creditor or the account’s open date.
- Asks you to “confirm” your full Social Security number or bank login.
To verify a caller, hang up and contact the original creditor using the number on an old statement to ask who holds the account. Pull your free credit reports from AnnualCreditReport.com to see whether the collector is listed. Search the company on NMLS Consumer Access and your state’s license lookup.
Your rights and how to enforce them
The Fair Debt Collection Practices Act gives you a private right of action. Under 15 U.S.C. 1692k, you can sue a collector within one year of a violation for actual damages, statutory damages of up to $1,000 per lawsuit, and your attorney’s fees and court costs. Because the law pays the lawyer’s fees, many consumer attorneys take these cases at no upfront cost, and the National Association of Consumer Advocates maintains a directory.
Keep evidence. Save voicemails, screenshots of texts and emails, envelopes and letters. Log every call with the date, time, caller name and what was said. Several states let you record calls without telling the other party, while others require consent, so check your state’s rule before recording.
Where to complain:
- CFPB complaint portal. The bureau forwards complaints to the company, which must respond, and uses the data for enforcement.
- FTC ReportFraud. Especially for scam collectors and fake debts.
- Your state attorney general and, where the collector is licensed, the state licensing regulator.
- FBI IC3 if the “collector” obtained money through fraud.
If you are on active military duty, the Servicemembers Civil Relief Act adds protections, including a cap on interest for debts incurred before service and the right to seek a stay of civil proceedings.
FAQ
Can a debt collector call my family or my employer?
A collector may contact other people only to locate you, once each, and cannot mention the debt. Calls to your employer must stop once you say the employer forbids them. Repeated calls to relatives, or any disclosure of the debt to them, violate the federal act.
Does a debt collector have to prove I owe the money?
After a timely written dispute, the collector must stop collecting until it sends verification, which is usually a copy of a statement or the signed agreement. In court, the burden is on the collector to prove ownership and the amount. Debt buyers with thin records sometimes drop cases when a consumer insists on proof.
What happens if I never respond to a debt collector?
The collector can keep contacting you within the legal limits, report the account and sue before the statute of limitations runs out. If you ignore a lawsuit, the court will usually enter a default judgment for the full amount plus costs. Responding, even just to dispute, is almost always better than silence.
Can a debt collector contact me on social media?
Yes, by private message only, and the message must identify the sender as a collector and include a way to opt out. Public posts, comments and friend requests that reveal the debt are prohibited under Regulation F.
Will paying a collection remove it from my credit report?
No. The account stays for up to seven years from the original delinquency but will show a zero balance. Some collectors agree to “pay for delete,” though the bureaus discourage the practice and the CFPB has not endorsed it. Newer FICO and VantageScore models ignore paid collections, which lessens the damage.
Is a creditor the same as a debt collector?
No. The creditor is the company you originally owed. A debt collector is a third party collecting on the creditor’s behalf or a buyer that purchased the account. Federal collection rules apply to the collector, not the original creditor, though several states, including California, cover both.
Laws and regulations referenced
- Fair Debt Collection Practices Act, 15 U.S.C. 1692
- Regulation F (debt collection), 12 CFR Part 1006
- Fair Credit Reporting Act, 15 U.S.C. 1681
- Servicemembers Civil Relief Act, 50 U.S.C. 3901
Links go to the official text on government sites.
Check, verify or complain

Marcus covers credit scores, credit reports and getting out of debt: consolidation, nonprofit counseling, settlement and what debt collectors may and may not do. He works from the federal laws that apply, CFPB guidance and the credit bureaus' published rules.